Tax year and partnership details
The tax year beginning and ending dates, the name of the partnership, its taxpayer ID number (TIN) and its address.
15288
Request to Revoke Partnership Election under IRC Section 6221(b) or Request to Revoke Election under 1101(g)(4)
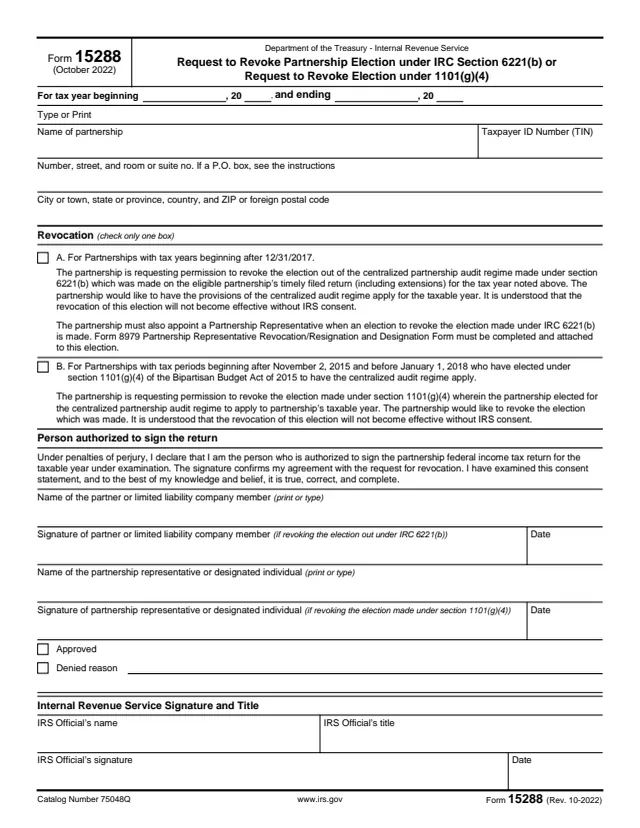
Form 15288, Request to Revoke Partnership Election under IRC Section 6221(b) or Request to Revoke Election under 1101(g)(4), is filed by a partnership, not by an individual. The instructions say it is used only by an eligible partnership that made a valid election out of the centralized audit regime on a timely filed return (including extensions), or by a partnership that elected under section 1101(g)(4) of the Bipartisan Budget Act of 2015 (BBA) to have the centralized audit regime apply.
If the IRS approves a request to revoke an election out under section 6221(b), the centralized partnership audit regime under BBA applies to that tax year. If it approves a request to revoke an election in under section 1101(g)(4), the instructions say either the TEFRA unified partnership audit procedures or deficiency procedures will apply, as appropriate. The form says a revocation does not become effective without IRS consent.
The request goes to the person named on Letter 2205-D, the examination notice. You can fill out Form 15288 free in your browser on this page and download the result without an account.
The tax year beginning and ending dates, the name of the partnership, its taxpayer ID number (TIN) and its address.
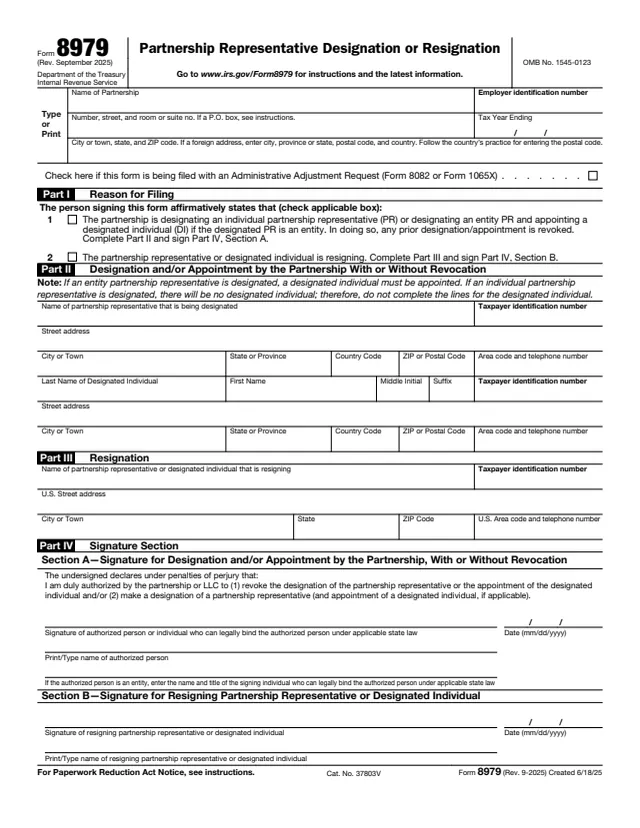
A request to revoke the election out of the centralized partnership audit regime made under section 6221(b). The form says Form 8979 is completed and attached.
A request to revoke the election made under section 1101(g)(4) to have the centralized partnership audit regime apply.
A penalties of perjury statement, then names, signatures and dates for a partner or LLC member (Box A) or the partnership representative or designated individual (Box B).
Approved and Denied boxes, a denial reason, and the IRS official's name, title, signature and date.
Enter the beginning and ending dates of the tax year the request covers.
Enter the partnership's name, TIN and address. The form says to see the instructions if the address is a P.O. box.
The form says to check only one box: A for a section 6221(b) election out, or B for a section 1101(g)(4) election in.
When revoking an election out under section 6221(b), the form and instructions say Form 8979 is provided with Form 15288 to appoint a partnership representative.
For Box A, a partner or LLC member prints their name, signs and dates. For Box B, the partnership representative or designated individual does.
The last section, with the Approved and Denied boxes and the IRS official's name, title and signature, is completed by the IRS.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the request is submitted to the person whose name is on Letter 2205-D, the notice that the partnership is under examination.
The instructions say the request should be made within 30 days of receipt of Letter 2205-D.
The instructions say a request is accepted past the 30 days only under certain circumstances and when it is administratively convenient for the IRS.
The form says the revocation does not become effective without IRS consent. The instructions say notice of acceptance or denial will be mailed to the partnership.
The signer declares under penalties of perjury that they are authorized to sign the partnership's return for the taxable year under examination.
The form is filed by a partnership under examination and signed by the person the instructions name for the box checked. The IRS approves or denies it.
No tool matches that search.
The instructions say only an eligible partnership that made a valid election out of the centralized audit regime, or a partnership that elected in under section 1101(g)(4) of the BBA, uses it.
The instructions say the request should be made within 30 days of receiving Letter 2205-D, which tells the partnership it is under examination.
To the person whose name is on Letter 2205-D, according to the instructions.
For a Box A request to revoke an election out under section 6221(b), the form and instructions say Form 8979 is completed and provided with Form 15288.
For Box A, any person authorized to sign Form 1065, including any partner or LLC member. For Box B, the partnership representative or designated individual.
No. The form says it does not become effective without IRS consent, and the instructions say the partnership is notified by mail of acceptance or denial.