Header and items A to E
The tax year, fund name and EIN, the name and identifying number of a trustee or disqualified person, who the return is filed for, change boxes and where the books are kept.
1120-ND
Return for Nuclear Decommissioning Funds and Certain Related Persons
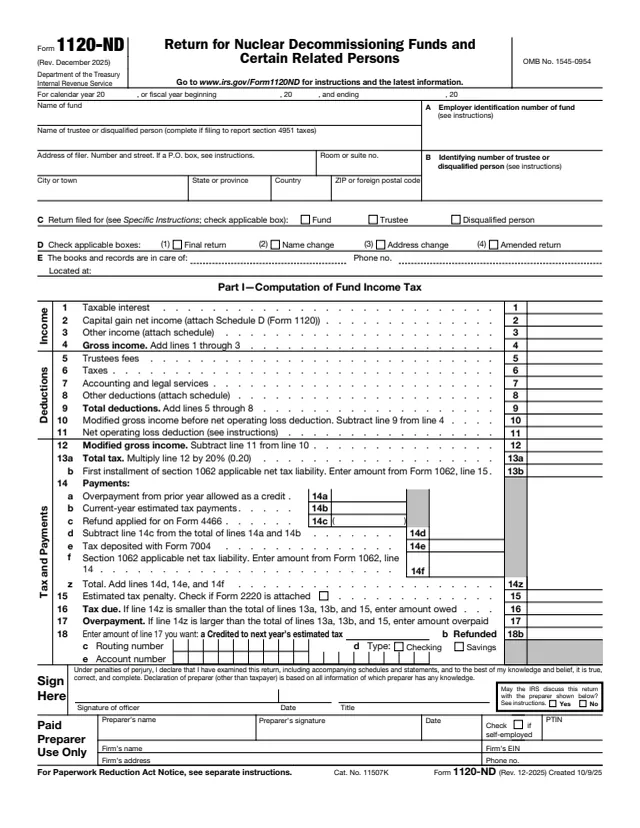
Form 1120-ND, Return for Nuclear Decommissioning Funds and Certain Related Persons, is the return a nuclear decommissioning fund files with the IRS. The IRS says nuclear decommissioning funds use it to report contributions received, income earned, the administrative expenses of operating the fund, the tax on modified gross income, and the section 4951 initial taxes on self-dealing.
The instructions explain that taxpayers electing under section 468A are allowed deductions for amounts contributed to a qualified fund, up to 100% of the present value of the nuclear power plant's decommissioning costs. The fund itself then reports its income on this form, and the form figures the fund's tax at 20% of modified gross income. Trustees and disqualified persons who owe the section 4951 tax on self-dealing file their own Form 1120-ND.
The instructions say to use the December 2025 revision for 2025 and later years until a superseding revision is issued. You can fill out Form 1120-ND free in your browser on this page and download it without an account.
The tax year, fund name and EIN, the name and identifying number of a trustee or disqualified person, who the return is filed for, change boxes and where the books are kept.
Lines 1 to 12 list taxable interest, capital gain net income and other income, then trustee fees, taxes, accounting and legal services, other deductions and any NOL deduction.
Line 13a is the total tax at 20% of modified gross income. Lines 13b to 18 cover section 1062 amounts, payments, the estimated tax penalty, tax due, overpayment and direct deposit.
Assets such as cash, certificates of deposit and government obligations, then liabilities and fund balance, at the beginning and end of the year.
The electing taxpayer's name and EIN, contributions, the ruling amount, distributions, tax-exempt interest, and yes or no questions on the use of fund assets and self-dealing.
Section A lists each act with its date, description, the persons liable and the amount involved. Section B totals the section 4951 taxes, payments with Form 7004 and the tax due.
Enter the fund's true name, address and EIN. In item C, check Fund for the fund's income tax return, or Trustee or Disqualified person for a section 4951 return. The instructions say item B is not completed on the fund's return.
Enter taxable interest (tax-exempt interest goes on Schedule M, line 2d), capital gains from Schedule D (Form 1120), other income and the deductions. The instructions say decommissioning costs are not included in other deductions.
Multiply line 12 by 20% (0.20) on line 13a, enter payments on lines 14a to 14z, check the box on line 15 if Form 2220 is attached, then figure tax due or overpayment and any direct deposit.
The instructions say the balance sheets should agree with the fund's books and records. On Schedule M, enter the electing taxpayer and the contribution amounts, and answer the questions on lines 3, 4 and 5.
List each act and the amount involved. The form figures the tax on a self-dealing disqualified person at 10% of column (f) and the tax on a trustee at 2 1/2% of column (f).
An authorized trustee signs and dates the fund's return. The instructions say a person who engaged in self-dealing, or the individual authorized to sign for that person, signs that person's return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say a fund generally files by the 15th day of the 4th month after the end of its tax year. A fund with a fiscal year ending June 30 files by the 15th day of the 3rd month.
If the fund's principal business, office or agency is in the United States: Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0012. In a foreign country or U.S. territory: Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The instructions say to file Form 7004 to request an extension of time to file, generally by the regular due date. Trustees and disqualified persons reporting section 4951 taxes also use Form 7004.
The instructions say nuclear decommissioning funds use electronic funds transfer (EFT) for all federal tax deposits, through EFTPS or the fund's IRS business tax account. Section 4951 tax due in Part II is paid in full with the return.
The instructions say the fund makes installment payments if it expects its total tax for the year to be $500 or more, due by the 15th day of the 4th, 6th, 9th and 12th months of the tax year.
The instructions say a late return may be penalized 5% of the unpaid tax for each month or part of a month, up to 25%. For a return more than 60 days late, the minimum is the lesser of the tax due or $525 (adjusted for inflation).

7004
26 fields, 1 page
2220
322 fields, 4 pages
4466
43 fields, 1 page
1120
48 fields, 1 page
8822-B
22 fields, 2 pages
1062
26 fields, 1 page
This is a return for funds and certain related persons, not for individuals filing their own income tax. Item C on the form says who the return is filed for: the fund, a trustee or a disqualified person.
No tool matches that search.
The instructions describe it as a qualified fund under section 468A to which an electing taxpayer contributes amounts, deductible up to 100% of the present value of a nuclear power plant's decommissioning costs.
The form says to multiply modified gross income on line 12 by 20% (0.20) to get the total tax on line 13a.
The disqualified person or trustee who owes it, on a separate Form 1120-ND. The instructions say the initial tax is 10% of the amount involved for a disqualified person and 2 1/2% for a trustee who participates.
The instructions say the initial tax on an act of self-dealing is not imposed if the acts are corrected within the tax period.
Yes. Lines 18c to 18e hold the routing number, account type and account number. The instructions say direct deposit is not available to a foreign bank or a foreign branch of a U.S. bank.
The instructions say to use the December 2025 revision for 2025 and subsequent years until a superseding revision is issued.