Header and Schedules A count
Name, identifying number, and the total number of Schedules A (Form 1062) being filed. A separate Schedule A is filed for each qualified sale or exchange.
1062
Deferral of Tax on Gain From the Sale or Exchange of Qualified Farmland Property to Qualified Farmers
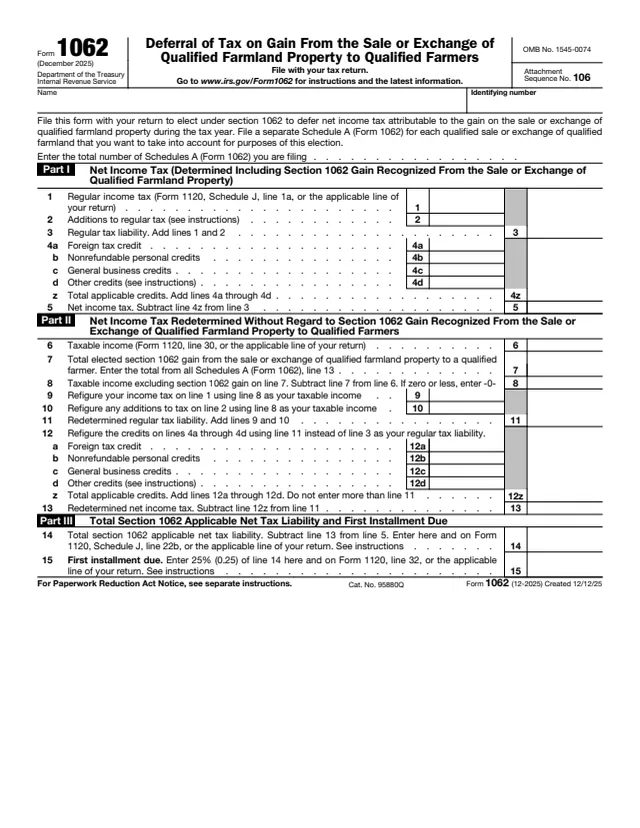
Form 1062 is used to elect to defer payment of the net income tax attributable to gain from a qualified sale or exchange of qualified farmland property to qualified farmers. The instructions say that for tax years beginning after July 4, 2025, P.L. 119-21, commonly known as the One Big Beautiful Bill Act, created section 1062, which allows that tax to be paid in four equal annual installments beginning in the year of the qualified sale or exchange.
The election is made by filing Form 1062, a Schedule A (Form 1062) for each qualified sale or exchange, and a copy of the section 1062 covenant for each. The form figures net income tax with the farmland gain (Part I) and without it (Part II), and the difference is the section 1062 applicable net tax liability. Line 15 shows the first installment, 25% of that amount.
The form is filed with the seller's own income tax return. You can fill out Form 1062 free in your browser on this page and download it without an account.
Name, identifying number, and the total number of Schedules A (Form 1062) being filed. A separate Schedule A is filed for each qualified sale or exchange.
Lines 1 to 5: regular income tax, additions to regular tax, regular tax liability, and the foreign tax credit, nonrefundable personal credits, general business credits and other credits, ending in net income tax.
Lines 6 to 13: taxable income, the total elected section 1062 gain from all Schedules A, line 13, and the tax and credits refigured on taxable income without that gain.
Line 14 is the total section 1062 applicable net tax liability, line 5 minus line 13. Line 15 is the first installment due, 25% (0.25) of line 14.
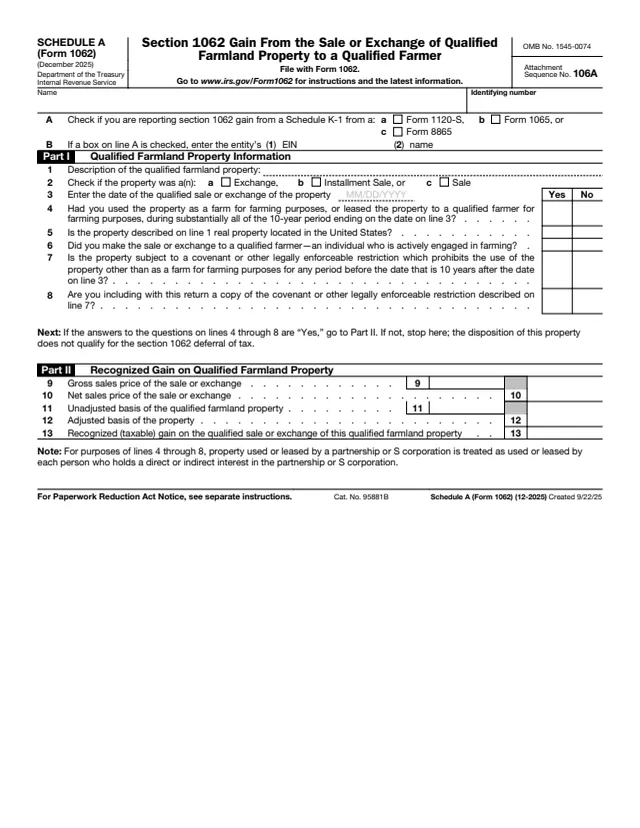
Fill out a Schedule A (Form 1062) for each qualified sale or exchange. The instructions say that if any answer on Schedule A lines 4 through 8 is No, the sale does not qualify and is not included on Form 1062.
Enter the regular income tax from your return, for example Form 1120, Schedule J, line 1a, or Form 1040, line 16, then additions to tax and credits. Line 5 is line 3 minus line 4z.
Enter taxable income including the section 1062 gain, for example Form 1040, line 15. On line 7 enter the total from all Schedules A, line 13. Line 8 is line 6 minus line 7, and -0- if zero or less.
Refigure the regular tax, additions to tax and credits using line 8 as taxable income. Line 13 is the net income tax without the gain.
Subtract line 13 from line 5 for line 14, and enter -0- if zero or less. Multiply line 14 by 25% (0.25) for line 15. Both amounts also go on the applicable lines of your return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 1062, Schedule(s) A (Form 1062) and a copy of each section 1062 covenant to your income tax return and file by its due date, including extensions.
The instructions say the first installment is paid by the return due date for the year of the qualified sale or exchange, without extension, even if the election is made on a return filed by the extended due date.
Each succeeding installment is paid by the return due date, without regard to any extension, for each of the 3 subsequent years.
The instructions say the unpaid installments become due early in some cases, such as a failure to timely pay an installment, the death of an individual taxpayer, or the liquidation or cessation of business of a C corporation.
The instructions define it as a legally enforceable restriction that prohibits using the property for any purpose other than farming during the 10-year period that begins on the day after the sale or exchange.
1062 Sch. A
27 fields, 1 page

1040
199 fields, 2 pages

1120
481 fields, 6 pages

1065
111 fields, 1 page
1120-S
114 fields, 1 page

3800
1,921 fields, 9 pages
The instructions say individuals and entities that elect to defer payment of the net income tax attributable to gain from a qualified sale or exchange file Form 1062.
No tool matches that search.
The instructions say it allows the net income tax attributable to gain from selling qualified farmland property to a qualified farmer to be paid in four equal annual installments beginning in the year of the sale or exchange.
The instructions say it is real property in the United States used as a farm for farming purposes, or leased to a qualified farmer, during substantially all of the 10-year period ending on the sale date, and subject to a section 1062 covenant.
The instructions define a qualified farmer as any individual who is actively engaged in farming within the meaning of 7 U.S.C. 1308-1(b) and (c).
No. The instructions say partnerships and S corporations file Schedule A (Form 1062) with their return, and each partner or shareholder who elects files Form 1062 and their own Schedule A.
Line 15 says to enter 25% (0.25) of line 14, the total section 1062 applicable net tax liability.
The instructions say no later than the due date, including extensions, of the income tax return for the year of the qualified sale or exchange.