1120-FSC

U.S. Income Tax Return of a Foreign Sales Corporation

Agency
IRS
Revision
Rev. December 2025
Fillable fields
612
Pages
6
Official source
IRS form page
Checked
October 21, 2026
Fill 1120-FSC online
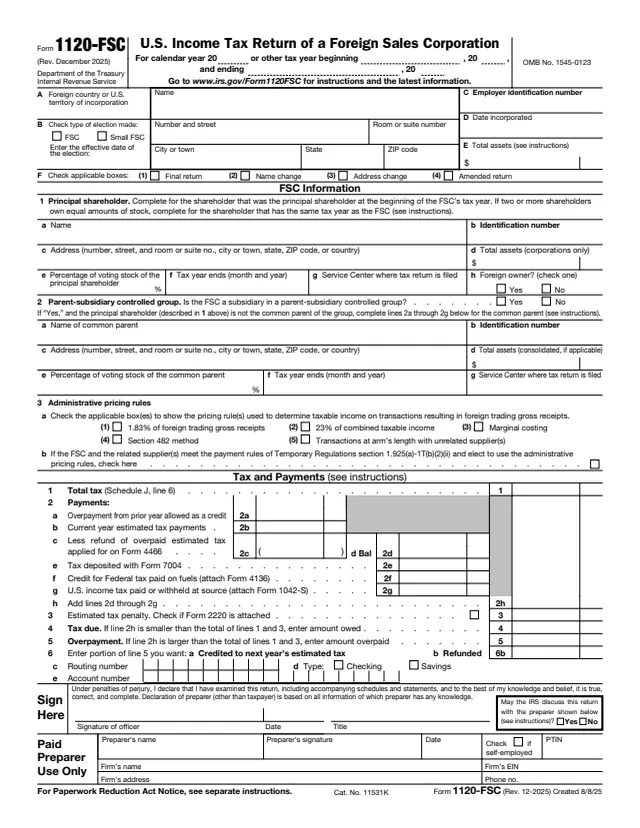
Page 1 of form 1120-FSC

Form 1120-FSC: U.S. Income Tax Return of a Foreign Sales Corporation

Form 1120-FSC, U.S. Income Tax Return of a Foreign Sales Corporation, is the annual return of a foreign sales corporation (FSC). The IRS About page says corporations electing to be treated as a FSC or small FSC file this form to report their income, deductions, gains, losses, credits and income tax liability.

The FSC rules were repealed in 2000, with transition rules for existing FSCs. The instructions say no corporation may elect to be a FSC or a small FSC after September 30, 2000, so the form is used by FSCs whose election is still in effect. It runs six pages: page 1 with FSC information and tax and payments, then Schedules A, B, E, F, G, J, L, M-1 and M-2 and an Additional Information section.

You can fill out Form 1120-FSC free in your browser on this page and download it without an account.

What's on Form 1120-FSC

Header and FSC Information

Items A to F ask for the country or U.S. territory of incorporation, the type of election, EIN, date incorporated and total assets. Lines 1 to 3 cover the principal shareholder, any parent-subsidiary controlled group and the administrative pricing rules used.
Tax and payments

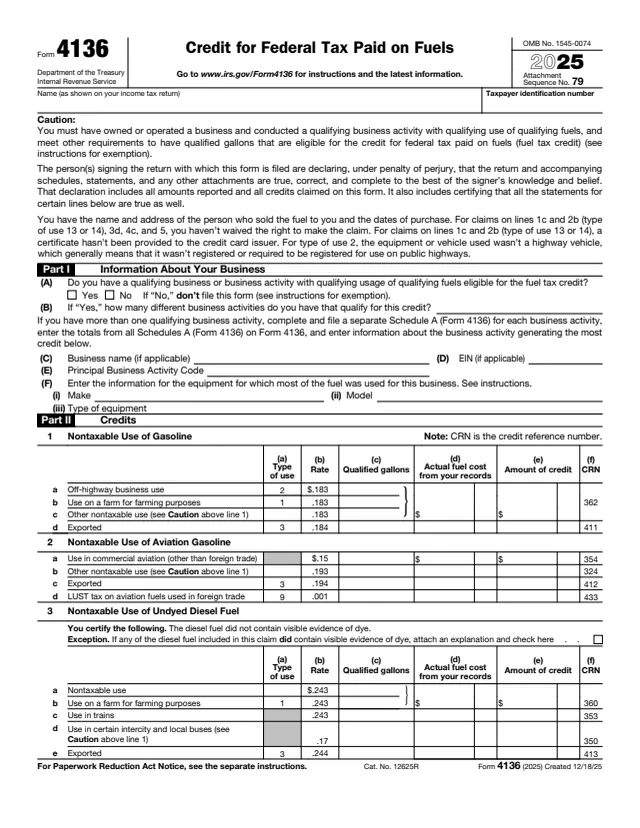
Lines 1 to 6 show total tax from Schedule J, payments such as estimated tax, tax deposited with Form 7004 and the fuel tax credit from Form 4136, then tax due or overpayment and the direct deposit fields.

Schedule A and Additional Information

Schedule A figures cost of goods sold related to foreign trading gross receipts. Additional Information asks yes or no questions on business activity, shareholders, books and records, foreign management rules and foreign economic process rules.

Schedule B: taxable income

Part I lists foreign trading gross receipts, the small FSC limitation, foreign trade income and exempt foreign trade income. Part II figures taxable income or loss after the net operating loss and dividends-received deductions.

Schedules E, F and G

Schedule E figures the exemption percentages. Schedule F reports net income from nonexempt foreign trade income and taxable nonforeign trade income. Schedule G lists deductions allocated or apportioned to foreign trade income.

Schedules J, L, M-1 and M-2

Schedule J is the tax computation. Schedule L holds balance sheets per books, Schedule M-1 reconciles book income with income per return, and Schedule M-2 analyzes unappropriated retained earnings.

How to fill out Form 1120-FSC

  1. 1

    Enter the header

    Enter the tax year, name, address, EIN, the foreign country or U.S. territory of incorporation and the election type. For item E, the instructions say to enter total assets from Schedule L, column (d), line 15, or -0- if there are none.

  2. 2

    Complete FSC Information

    Describe the principal shareholder at the beginning of the tax year, answer the parent-subsidiary question, and check the pricing rule boxes on line 3a used to figure taxable income on foreign trading gross receipts.

  3. 3

    Work through the schedules

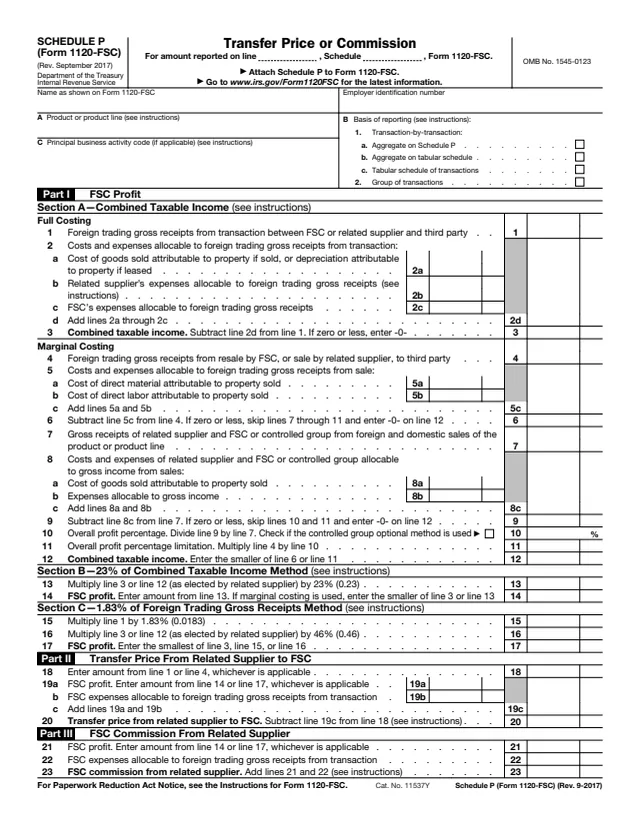
    Schedules A, B, F and G have column (a) for transactions using the administrative pricing rules and column (b) for those not using them, and Schedule E figures an exemption percentage for each. The instructions point to Schedule P (Form 1120-FSC) for those rules.

  4. 4

    Figure the tax

    Complete Schedule J and carry its total tax to line 1 on page 1. Then complete the payment lines and enter tax due on line 4 or the overpayment on line 5.

  5. 5

    Finish the balance sheets and sign

    Complete Schedules L, M-1 and M-2, then an authorized officer signs and dates the return. The instructions say not to enter See Attached or Available Upon Request instead of completing an entry space.

Why fill Form 1120-FSC on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

When and where to file Form 1120-FSC

Due date

The instructions say a corporation generally files by the 15th day of the 4th month after the end of its tax year. A FSC with a fiscal tax year ending June 30 files by the 15th day of the 3rd month after the end of its tax year.

Where to file

The instructions say to file with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.

Extension

The instructions say a FSC files Form 7004 by the return due date to request an extension of time to file.

Late filing penalty

The instructions say the penalty may be 5% of the unpaid tax for each month or part of a month the return is late, up to 25%. For a return required to be filed in 2026 that is more than 60 days late, the minimum is the smaller of the tax due or $525.

Assembling the return

Attach schedules and forms after page 6: Form 4136 first, then additional schedules in alphabetical order, additional forms in numerical order, and supporting statements last.

Who fills out Form 1120-FSC?

  • FSCs and small FSCs with an election in effect

    The instructions say to file Form 1120-FSC if the corporation elected to be treated as a FSC or small FSC, and the election is still in effect.

  • Small FSCs

    Item B asks whether the election made was FSC or small FSC. The instructions say a small FSC is exempt from the foreign management and foreign economic process requirements, and it completes only lines 1 through 8f of Additional Information.

  • Not for FSCs treated as domestic

    The instructions say a FSC that elects to be treated as a domestic corporation under section 943(e)(1) does not file Form 1120-FSC. It files Form 1120 instead.

  • Officers who sign

    The instructions list the president, vice president, treasurer, assistant treasurer, chief accounting officer or any other corporate officer authorized to sign. A receiver, trustee or assignee filing for the FSC signs instead.

  • Paid preparers

    Anyone paid to prepare the return generally signs it and completes the Paid Preparer Use Only section with a PTIN. If an employee of the FSC completes the form, that section stays blank.

The FSC itself files this return, signed by a corporate officer. The instructions describe who files it, who does not, and who signs.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 1120-FSC

Can a corporation still elect to be a FSC?

No. The instructions say no corporation may elect to be a FSC or a small FSC after September 30, 2000.

Does a FSC that elected domestic treatment file Form 1120-FSC?

No. The instructions say a FSC that elects to be treated as a domestic corporation under section 943(e)(1) files Form 1120 instead.

What is the small FSC limit?

The instructions say foreign trading gross receipts of a small FSC that exceed $5 million are generally not considered in determining its exempt foreign trade income. Line 6b of Schedule B shows $5,000,000.

When does a FSC stop being treated as a FSC?

The instructions say a FSC with no foreign trade income for any 5 consecutive tax years beginning after December 31, 2001, is no longer treated as a FSC for any tax year beginning after that period.

Can a FSC claim tax treaty benefits?

No. The instructions say a FSC may not claim any benefits under any income tax treaty between the United States and any foreign country.

Where do I send Form 1120-FSC?

The instructions give the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.