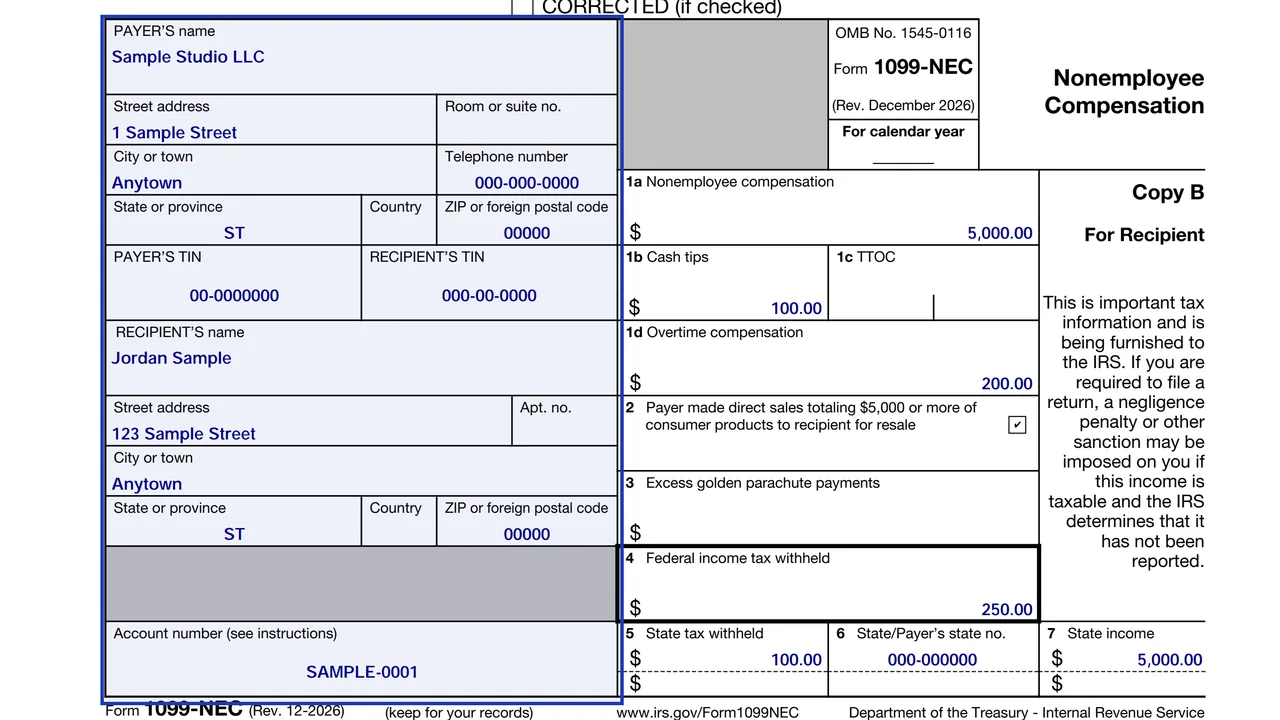
Payer and recipient blocks
The payer's name, address and TIN, and the recipient's name, address and TIN, plus an account number if you file more than one form for the recipient.
1099-NEC
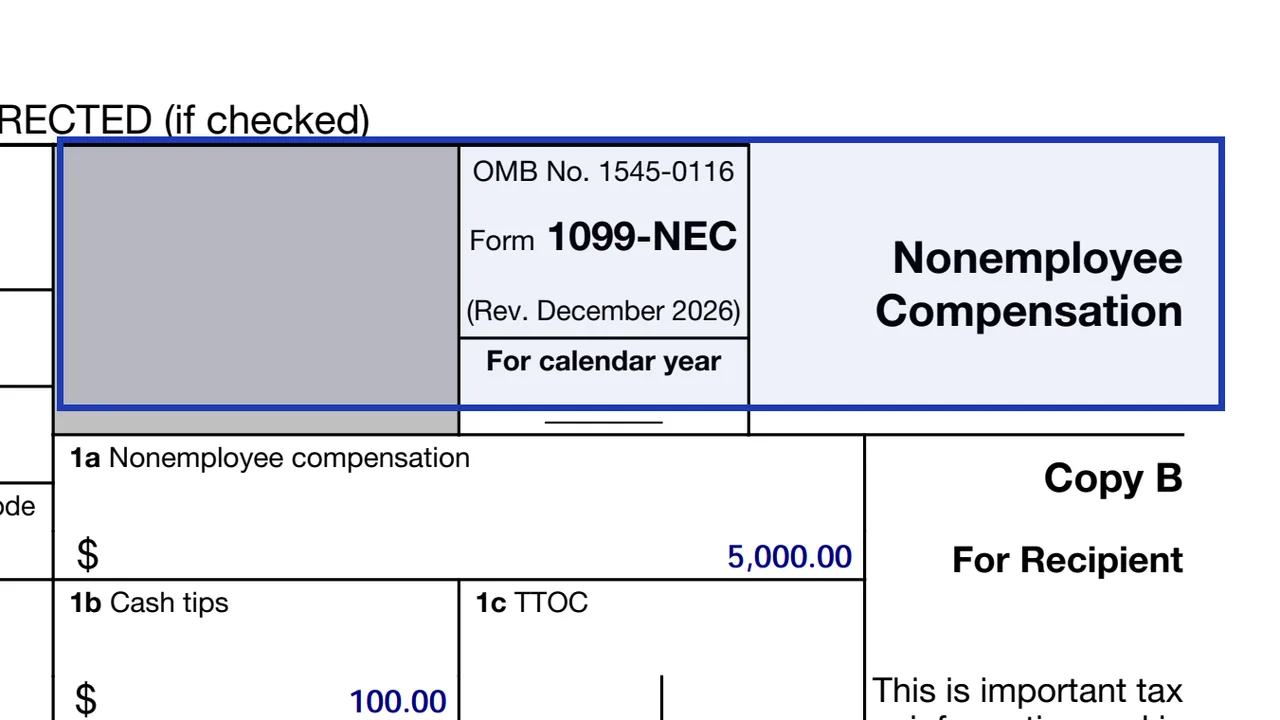
Nonemployee Compensation
Form 1099-NEC reports nonemployee compensation: money a business paid to someone who is not its employee for services. A freelancer, consultant or independent contractor who earned enough from one client gets this form from that client, and the client files a copy with the IRS.
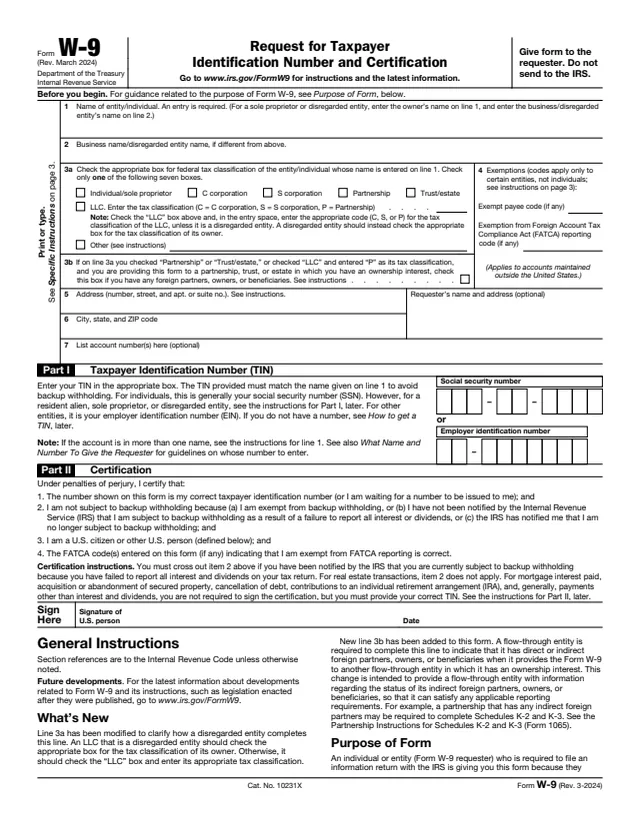
The payer fills it out, not the person who was paid. If you received one, use the amount in box 1a to report your self-employment income. If you are the payer, you collect the contractor's name and taxpayer identification number on Form W-9 before you pay them, so you have what you need in January.
The IRS says to use this form to report nonemployee compensation. Wages for employees go on Form W-2 instead.
The payer's name, address and TIN, and the recipient's name, address and TIN, plus an account number if you file more than one form for the recipient.
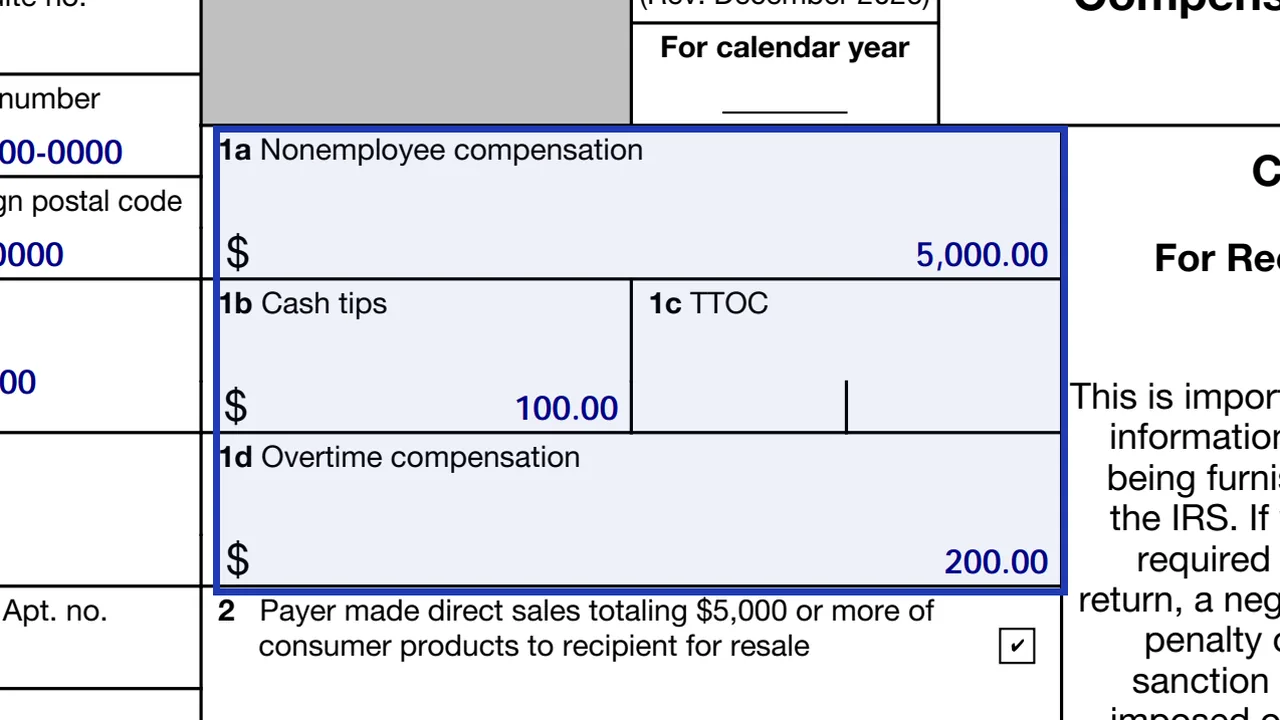
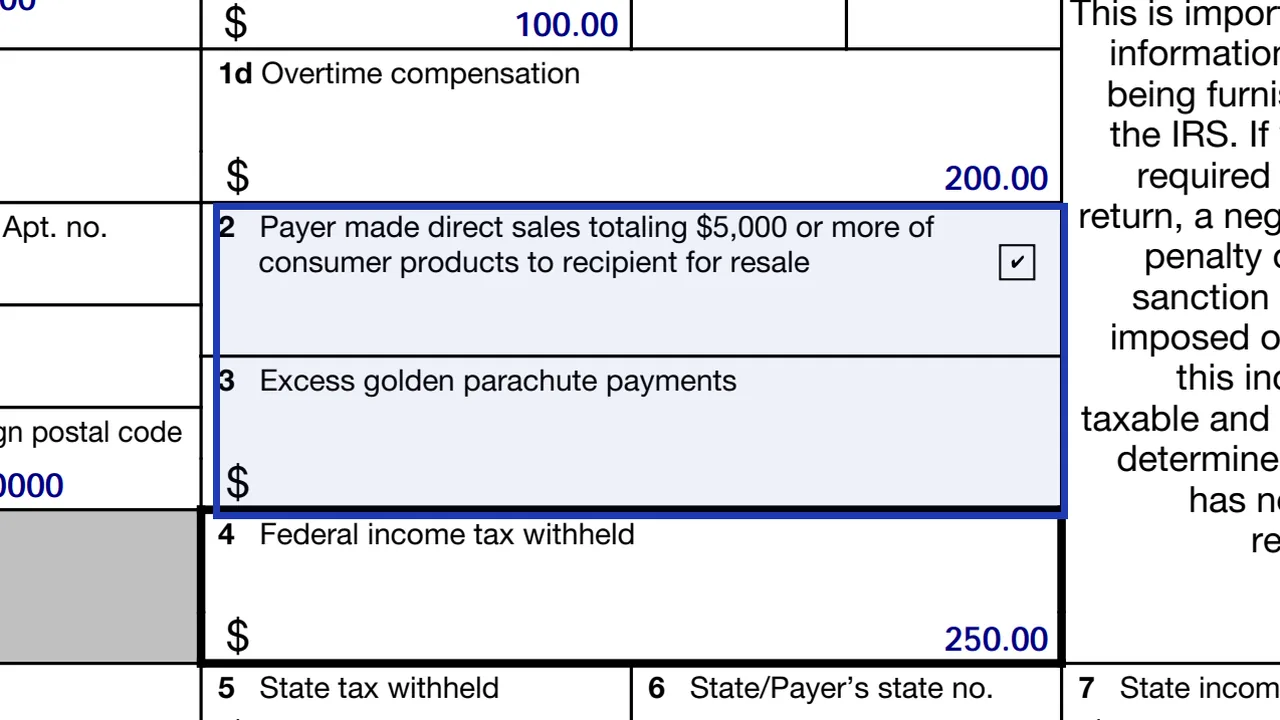
1a is nonemployee compensation. 1b is cash tips included in 1a. 1c is Treasury Tipped Occupation Code(s). 1d is qualified overtime compensation included in 1a.
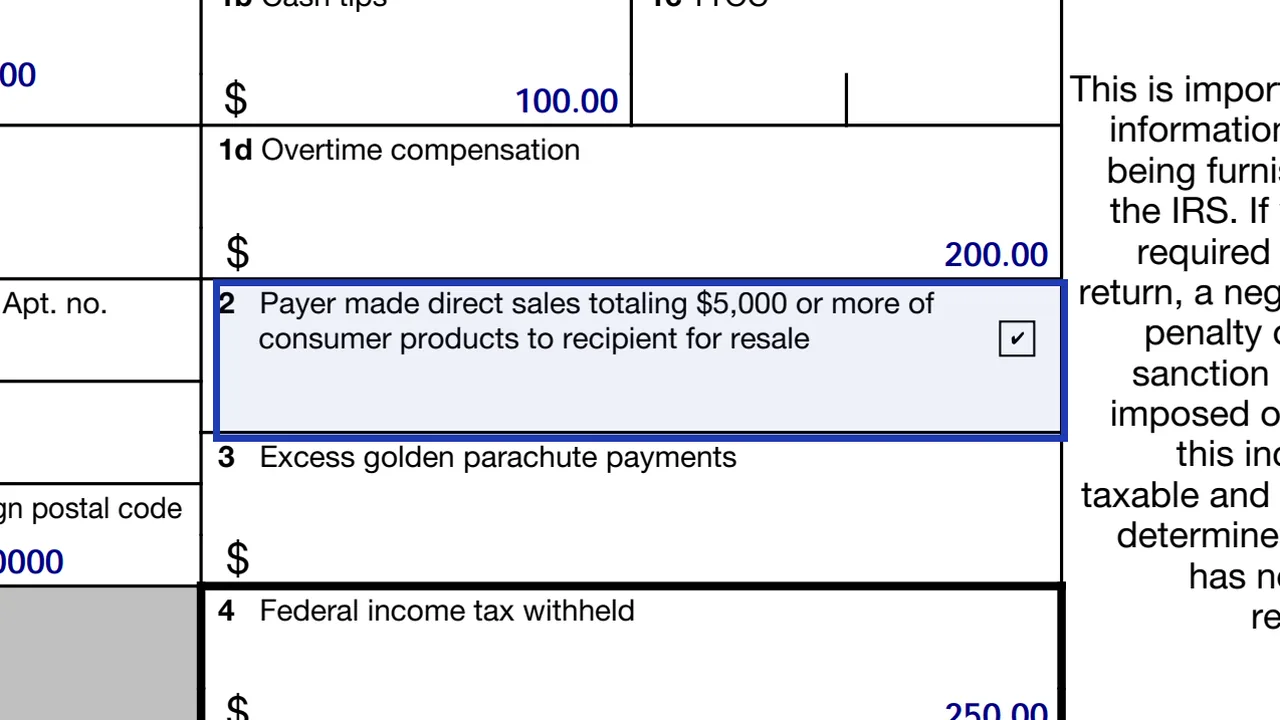
Checkbox for direct sales of $5,000 or more of consumer products for resale, made somewhere other than a permanent retail establishment.
Excess golden parachute payments.
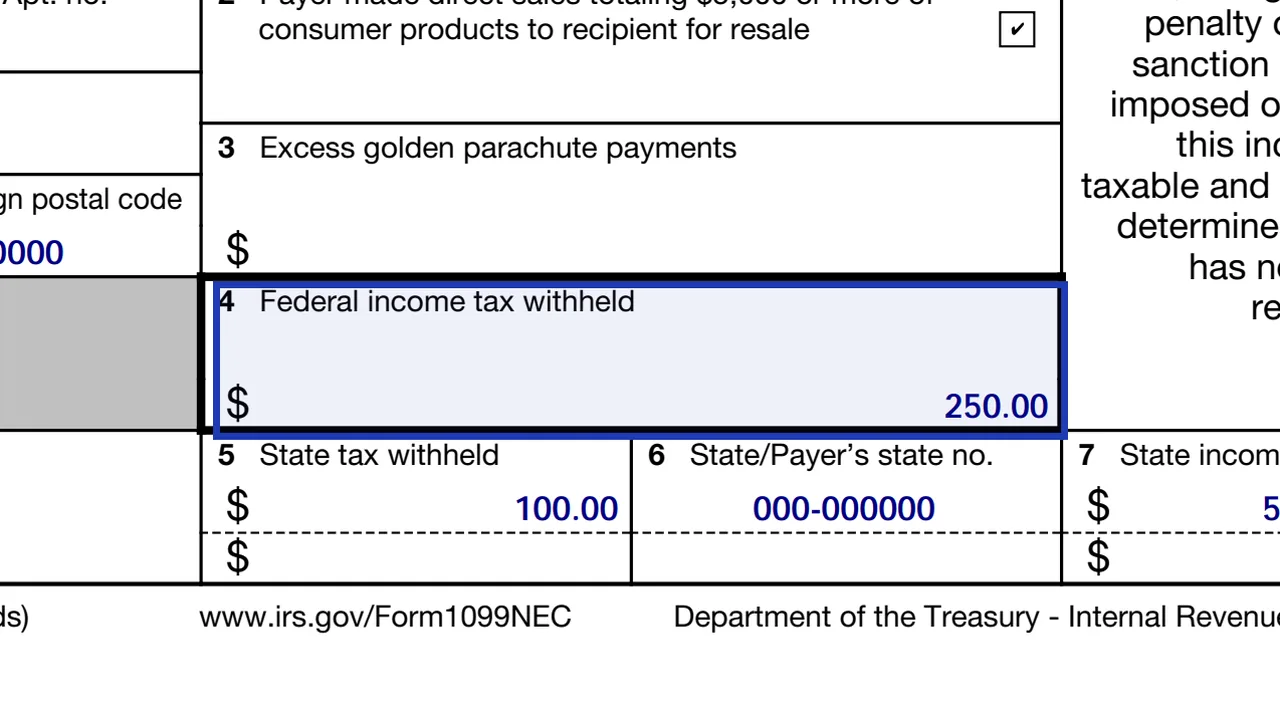
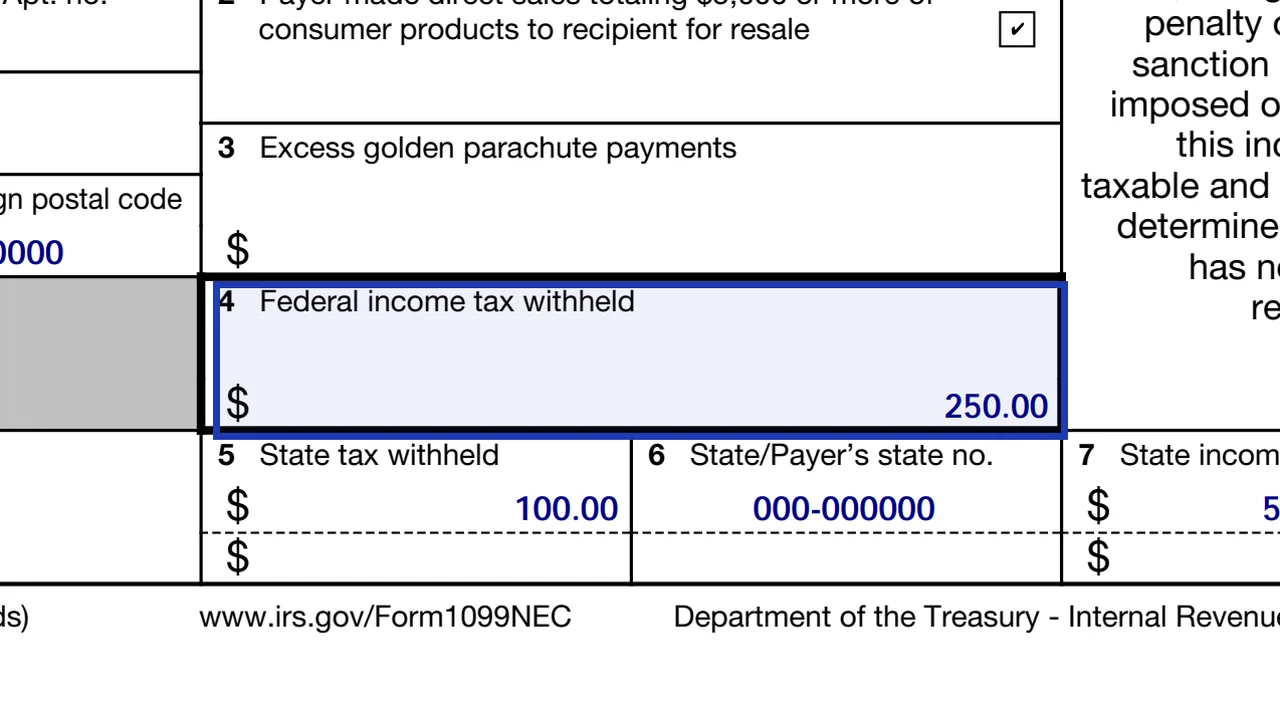
Federal income tax withheld as backup withholding.
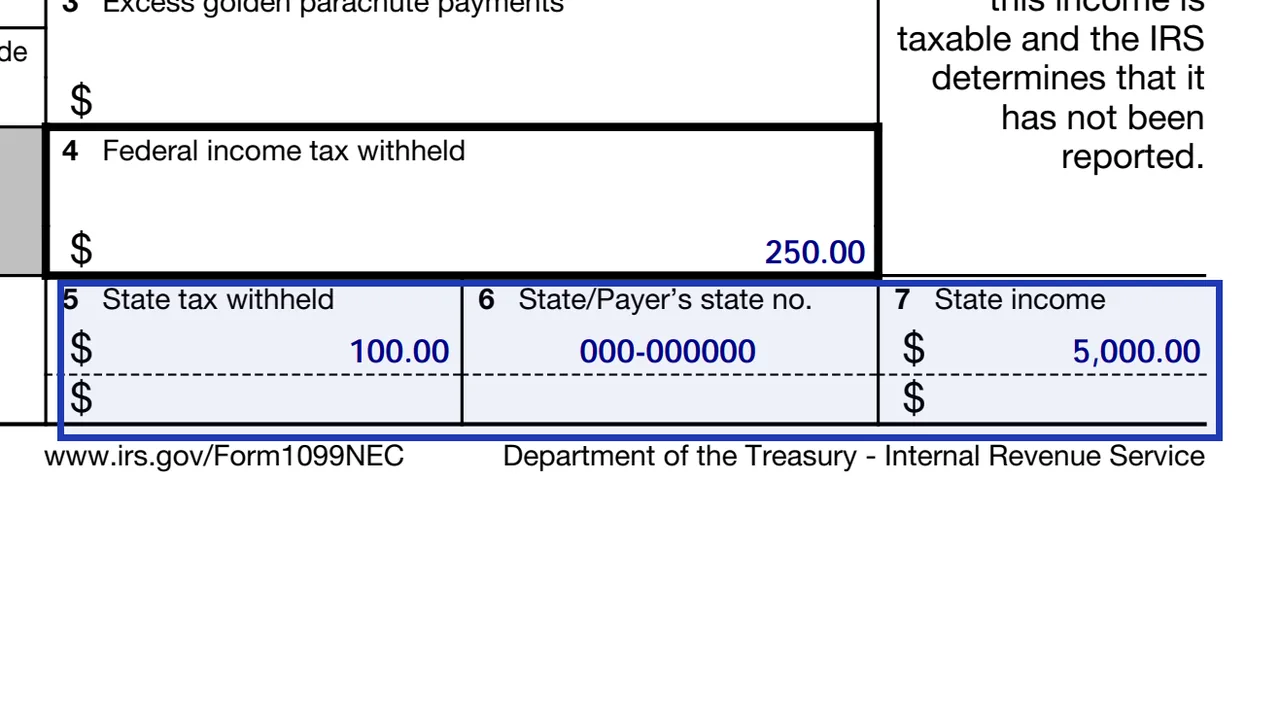
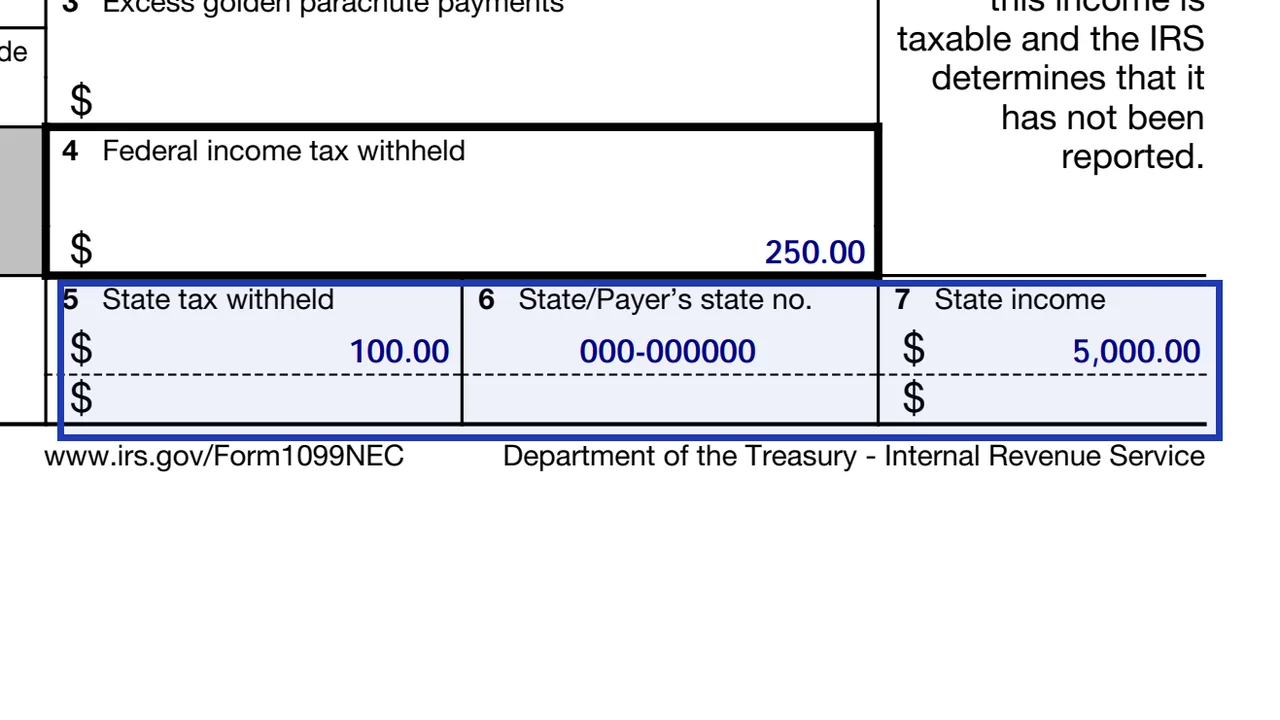
State tax withheld, payer's state number and state income. They are optional for the IRS and cover up to two states.
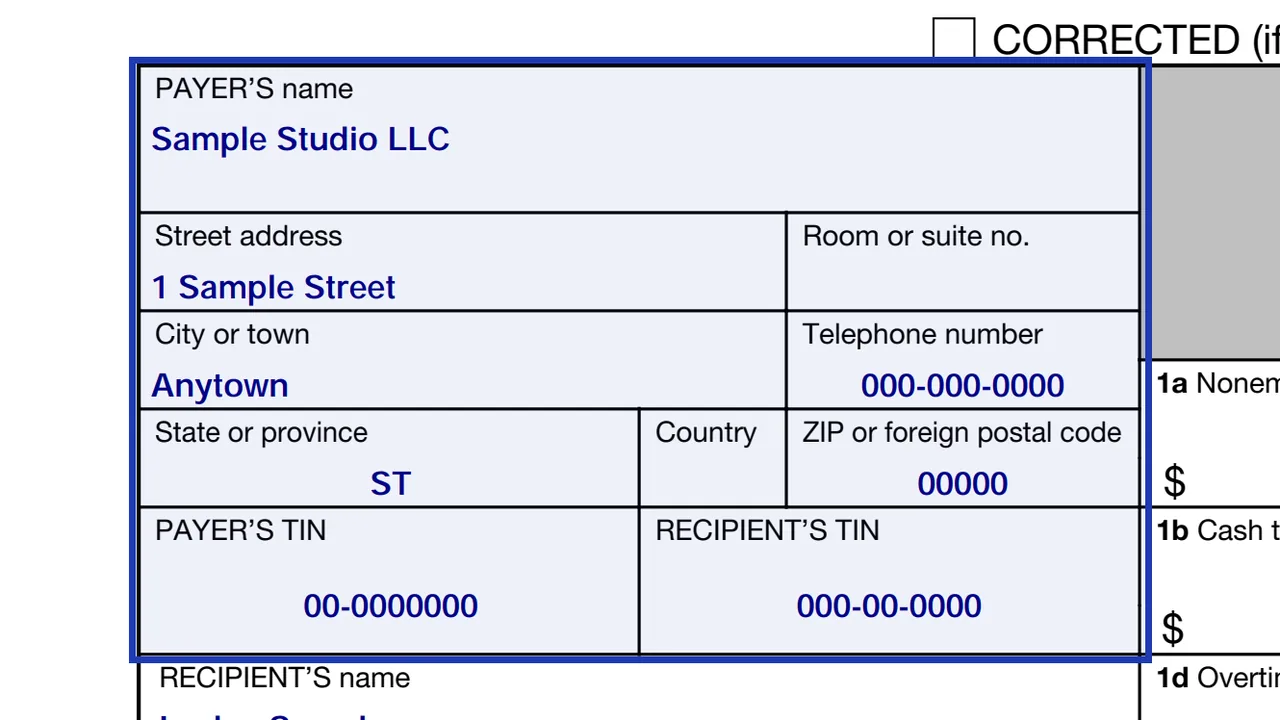
Enter your name, address and TIN. Use the exact name and number you use for your own tax filings.
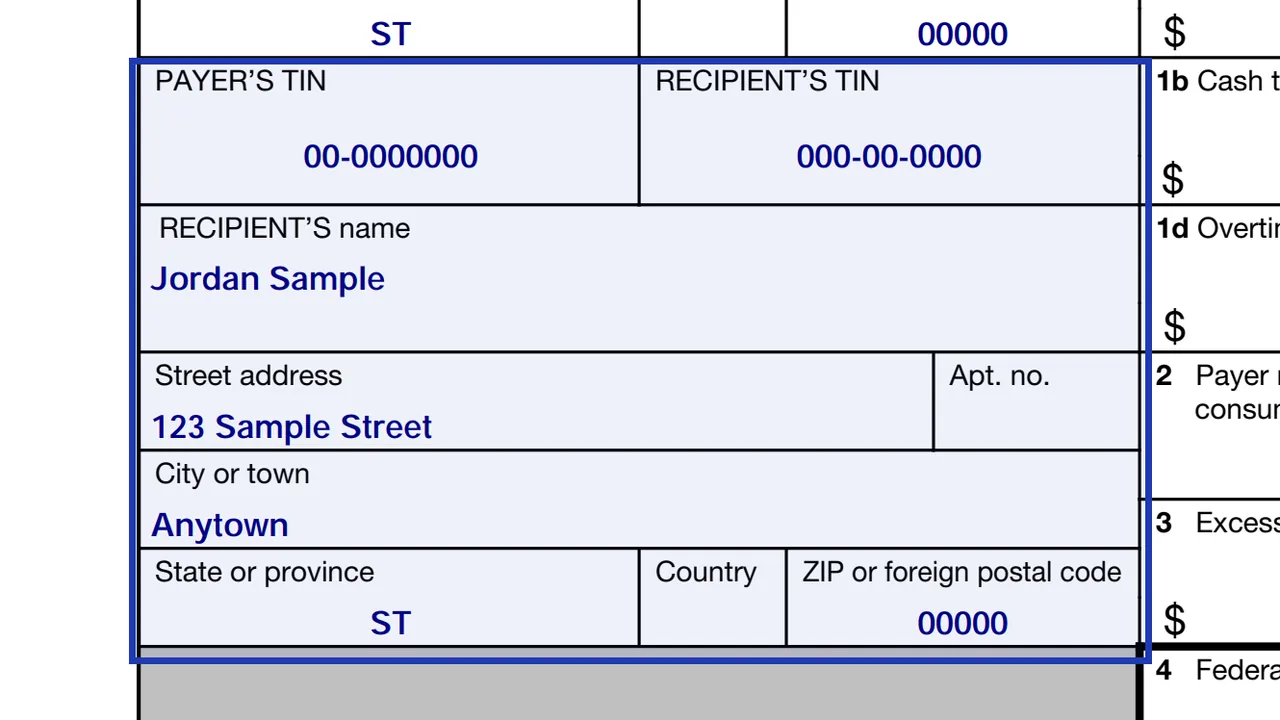
Copy the recipient's name and TIN from their Form W-9. The recipient's TIN may be truncated on the copy given to them but not on the IRS copy.
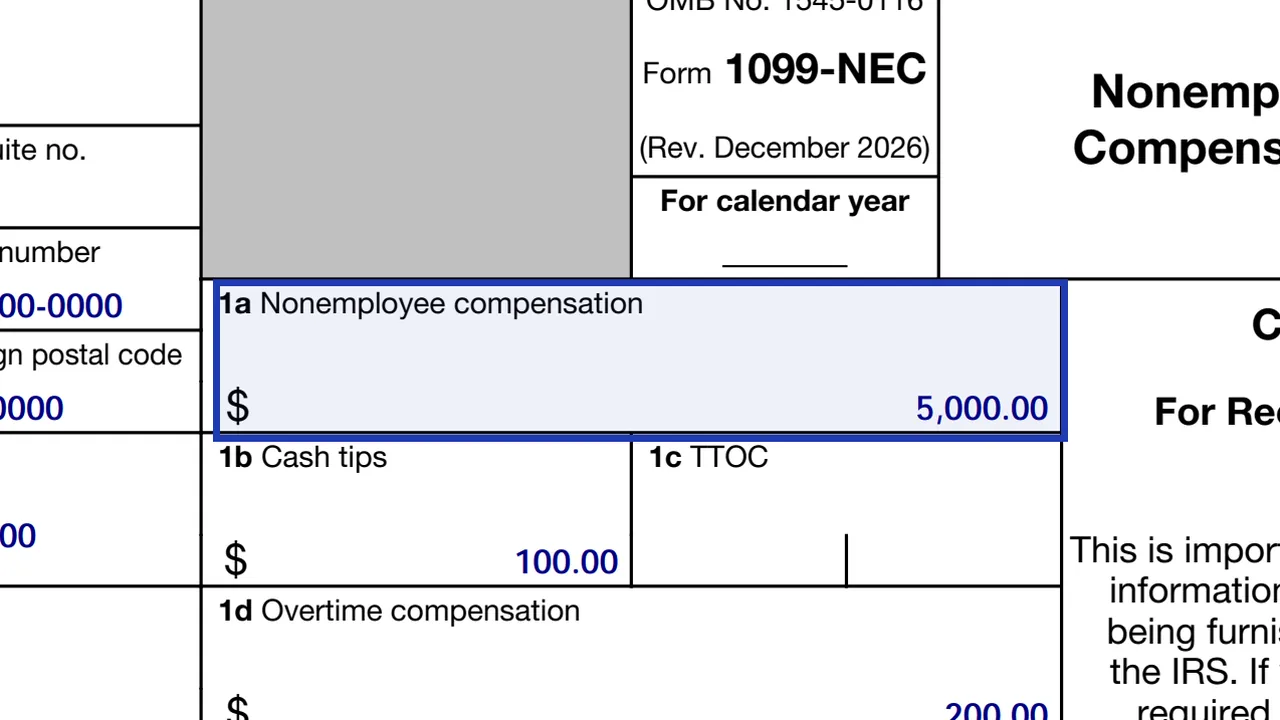
Enter the total paid for services during the year, including parts and materials supplied.
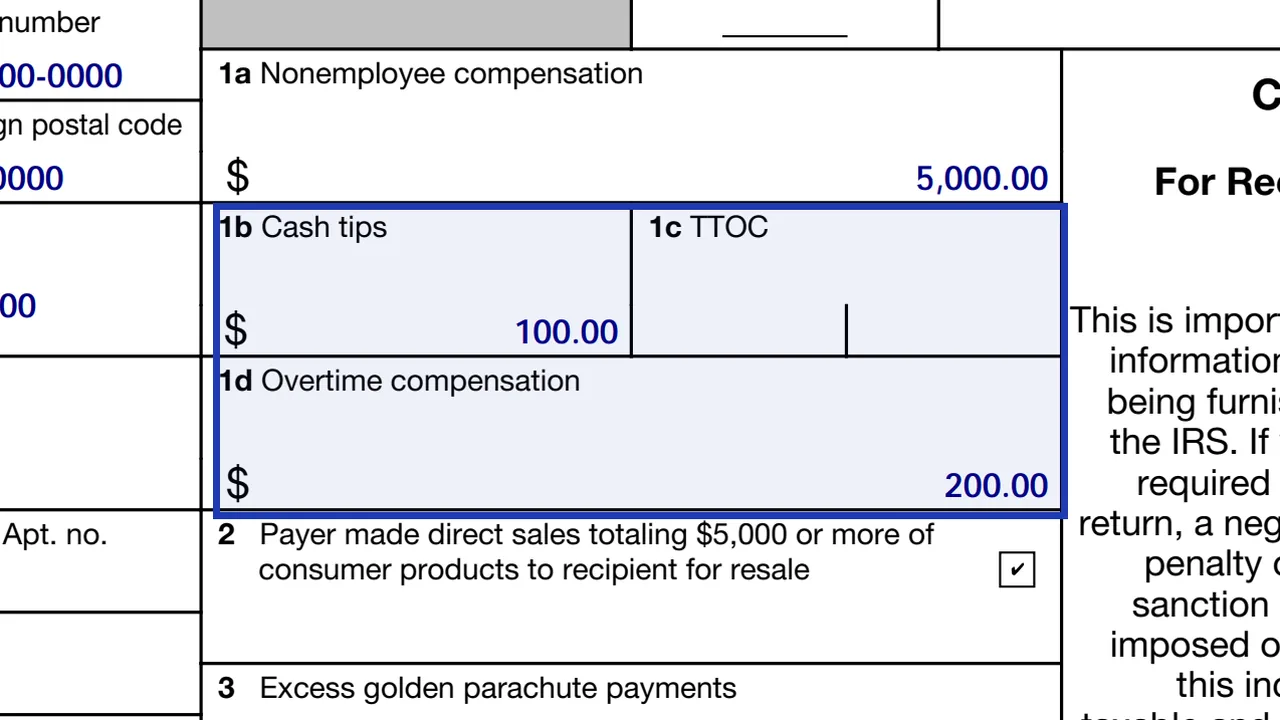
Fill in the tip and overtime amounts only when they apply, remembering they are already inside the 1a total.
Check box 2 for qualifying direct sales. Use box 3 only for excess golden parachute payments.
Enter any backup withholding you took, which applies when a payee did not provide a TIN.
Complete only if you participate in a state reporting program or a state requires it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to furnish the recipient's copy and file with the IRS by January 31. When that date falls on a weekend or legal holiday, the next business day applies; for 2025 payments the General Instructions listed February 2, 2026.
You must e-file if you file 10 or more information returns in total, counting all types. The IRS names IRIS as its online portal. Paper filers send Copy A with Form 1096.
Where a state requires a paper copy, Copy 1 goes to the state tax department. Copy 2 goes to the recipient for their state return.
The instructions refer to Publication 1099 and the General Instructions for penalty amounts, and mention a separate penalty for attorneys who fail to supply a TIN.
Reporting an employee's pay here instead of on Form W-2, reporting card or payment-app payments that belong on Form 1099-K, and missing a TIN because no W-9 was collected.
W-9
23 fields, 6 pages
1099-MISC
179 fields, 6 pages
1099-K
207 fields, 6 pages
W-2
568 fields, 11 pages
1096
55 fields, 3 pages
W-4
48 fields, 5 pages
According to the instructions, you file for each person you paid for services in the course of your trade or business who is not an employee.
No tool matches that search.
The payer fills it out for the person it paid. The contractor receives a copy and does not complete it.
The instructions give $2,000 for nonemployee compensation and attorney payments, plus any amount where backup withholding applied.
Furnish it to the recipient and file with the IRS by January 31. Weekends and holidays move the due date to the next business day.
Corporations are generally excluded, with exceptions such as attorneys' fees. How an LLC is taxed decides the answer, so check the W-9 the LLC gave you.
The 1099-NEC reports nonemployee compensation. Form 1099-MISC reports other kinds of payments.
Payments made by credit card or a third-party network are reported by the processor on Form 1099-K, so do not include them on the 1099-NEC.