Tax year and identification
Calendar year 2025 or fiscal year dates, the name of the trust or decedent's estate, and its employer identification number.
1041-T
Allocation of Estimated Tax Payments to Beneficiaries (Under Code section 643(g))
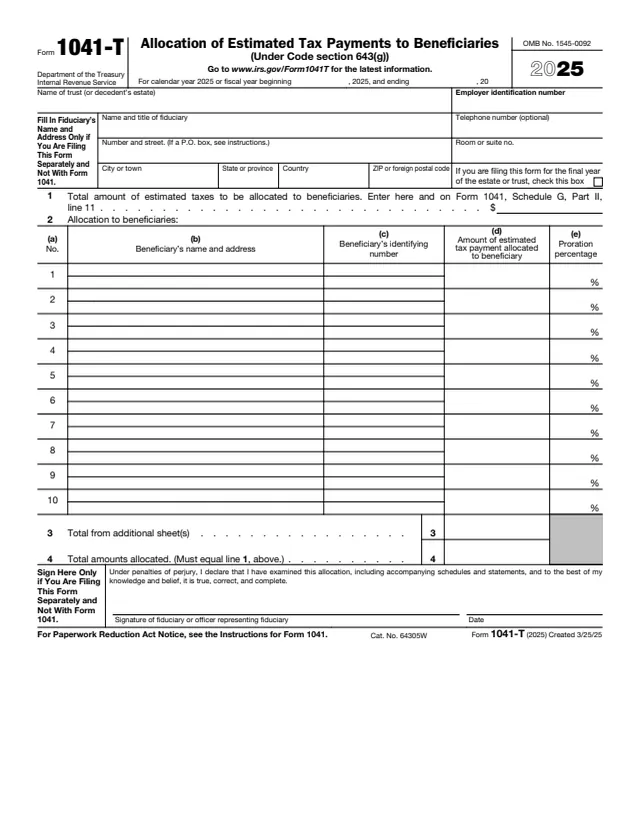
Form 1041-T is the Allocation of Estimated Tax Payments to Beneficiaries under Code section 643(g). The IRS says a trust or, for its final tax year, a decedent's estate may elect to have any part of its estimated tax payments (but not income tax withheld) treated as made by a beneficiary or beneficiaries. The fiduciary files this form to make the election.
The form lists the total estimated tax being allocated, then each beneficiary's name, address, identifying number, allocated amount and proration percentage. The instructions say that once made, the election is irrevocable.
This page covers the 2025 form, used for calendar year 2025 and fiscal years beginning in 2025 and ending in 2026. Its instructions are printed on page 2. You can fill out Form 1041-T free in your browser on this page and download the result without an account.
Calendar year 2025 or fiscal year dates, the name of the trust or decedent's estate, and its employer identification number.
Filled in only when the form is filed separately and not with Form 1041: fiduciary's name and title, optional phone number, address and the final year box.
The total estimated taxes to be allocated to beneficiaries, also entered on Form 1041, Schedule G, Part II, line 11.
Ten rows with columns for number, beneficiary's name and address, identifying number, amount allocated and proration percentage.
Line 3 holds the total from any additional sheets. Line 4 is the total allocated, which the form says must equal line 1.
Signed only when filed separately and not with Form 1041, by the fiduciary or an officer representing the fiduciary, under penalties of perjury.
For a fiscal or short tax year, fill in the tax year space at the top. When filing separately, include the suite or room number, or a P.O. box only if the post office does not deliver to the street address.
Enter the estimated tax payments the fiduciary elects to treat as paid by the beneficiaries. The instructions say to include it on Form 1041, Schedule B, line 10. Tax withheld from income cannot be allocated.
List the individual beneficiaries first, then all other beneficiaries. Enter each one's TIN, generally an SSN for individuals or an EIN for other entities. A joint filer's spouse SSN is an optional entry.
Enter the amount allocated to each beneficiary, then divide it by line 1 and enter the result as a percentage.
With more than 10 beneficiaries, list the rest on an attached sheet in the line 2 format and enter its total on line 3. Add everything on line 4 so it equals line 1.
If the form is not attached to Form 1041, the fiduciary or an officer representing the fiduciary signs and dates it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the form is filed by the 65th day after the close of the tax year for the election to be valid. For a 2025 calendar year decedent's estate or trust, that date is March 6, 2026.
If the due date falls on a Saturday, Sunday or legal holiday, the instructions say to file on the next business day.
Attach it to Form 1041 only when making the election with Form 1041; otherwise it is filed separately. The instructions say filing it with Form 1041 does not change its due date.
The form's chart sends a separately filed form to Kansas City, MO 64999 or Ogden, UT 84201, depending on where the trust or estate is located.
The instructions say tax withheld, such as from gambling winnings or salary or pension payments reported on Form 1041, is reported on Form 1041, Schedule G, Part II, line 14 instead.
The IRS About page says the fiduciary files this form to make the section 643(g) election for a trust or, for its final tax year, a decedent's estate.
No tool matches that search.
The fiduciary of a trust or, for its final tax year, of a decedent's estate files it to make the section 643(g) election.
The instructions say by the 65th day after the close of the tax year. For a 2025 calendar year decedent's estate or trust, that date is March 6, 2026.
The instructions say that once made, the election is irrevocable.
No. The form allocates estimated tax payments only, and the instructions say withholding is reported on Form 1041, Schedule G, Part II, line 14.
The instructions say each beneficiary's amount from column (d) is also reported in box 13 of Schedule K-1 (Form 1041), using code A.