1041-N

U.S. Income Tax Return for Electing Alaska Native Settlement Trusts

Agency
IRS
Revision
Rev. December 2025
Fillable fields
226
Pages
4
Official source
IRS form page
Checked
October 21, 2026
Fill 1041-N online
Page 1 of form 1041-N

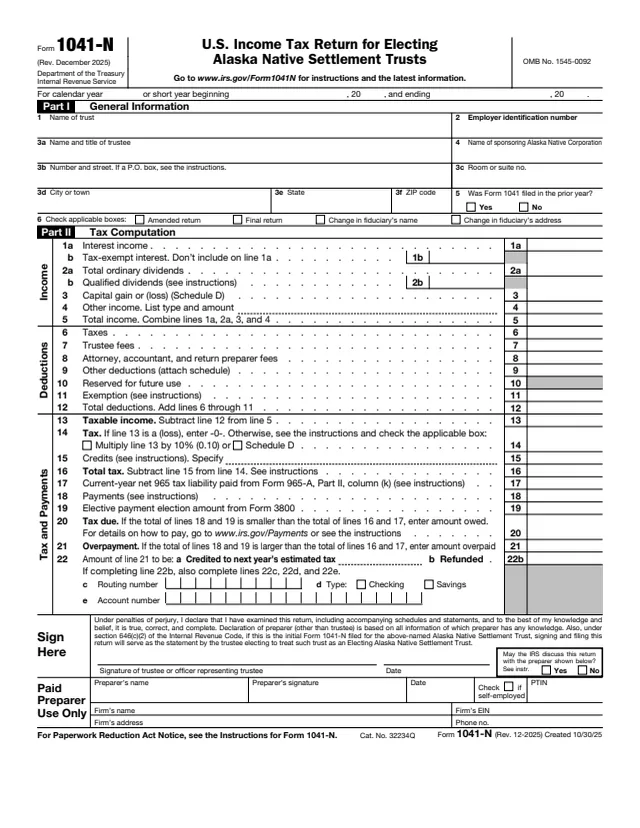
Form 1041-N: U.S. Income Tax Return for Electing Alaska Native Settlement Trusts

Form 1041-N, U.S. Income Tax Return for Electing Alaska Native Settlement Trusts, is the return of an Alaska Native Settlement Trust (ANST) that elects the special income tax treatment of Internal Revenue Code section 646. The IRS says this one-time election is made by filing Form 1041-N, and the same form reports the trust's income, deductions, gains and losses and figures and pays any income tax.

The instructions say an electing ANST pays tax on its taxable income at the lowest rate specified for single individuals (10%), and uses Part IV of Schedule D when it has net capital gain or qualified dividends. The form also carries the special information reporting for ANSTs on Schedule K, Distributions to Beneficiaries.

This page has the Rev. December 2025 edition. You can fill it out free in your browser on this page and download the result without an account.

What's on Form 1041-N

Part I: General Information

Name of trust, EIN, trustee name and title, address, name of the sponsoring Alaska Native Corporation, whether Form 1041 was filed in the prior year, and boxes for an amended or final return or a change in the fiduciary's name or address.

Part II: Tax Computation

Income on lines 1a to 5, deductions on lines 6 to 12 and taxable income on line 13, then tax, credits, net 965 tax liability, payments, elective payment election, tax due or overpayment and direct deposit on lines 14 to 22e.

Signature

Signed by the trustee or an officer representing the trustee. The form says that on the initial Form 1041-N, signing and filing serves as the trustee's statement electing to treat the trust as an Electing Alaska Native Settlement Trust.

Part III: Other Information

Five yes or no questions: property or income assignments received from an Alaska Native Corporation, foreign trust transactions, foreign financial accounts, Form 8938 and the section 643(e)(3) election.

Schedule D: Capital Gains and Losses

Short-term and long-term transactions, a summary in Part III, and a Part IV tax computation using maximum capital gains rates whose result goes to page 1, line 14.

Schedule K: Distributions to Beneficiaries

For each beneficiary: name and address, SSN, Tier I, Tier II, Tier III and Tier IV distributions, and total distributions.

How to fill out Form 1041-N

  1. 1

    Tax year and Part I

    Enter the calendar year or short year. The instructions say all electing ANSTs adopt a calendar year. On line 1, enter the exact name used to apply for the trust's EIN, then the trustee, address and sponsoring ANC, and check every line 6 box that applies.

  2. 2

    Lines 1a to 5: income

    Report interest, ordinary and qualified dividends, capital gain or loss from Schedule D, and other income. The instructions say taxable contributions received from an ANC go on line 4.

  3. 3

    Lines 6 to 13: deductions

    Enter taxes, trustee fees and professional fees, attach a schedule for line 9 and leave line 10 blank. The instructions say line 11 is $300 for a trust whose governing instrument requires all income to be distributed currently and $100 for all other trusts.

  4. 4

    Line 14: tax

    With no net capital gain or qualified dividends, multiply line 13 by 10% (0.10) and check the first box. Otherwise complete Part IV of Schedule D, enter its line 28 and check the Schedule D box.

  5. 5

    Lines 15 to 22e: credits and payments

    Enter credits, total tax, any net 965 tax liability paid from Form 965-A, payments and any elective payment election amount from Form 3800. Then figure tax due on line 20 or the overpayment on line 21, and for a refund add the bank details on lines 22c to 22e.

  6. 6

    Part III and Schedule K

    Answer the five questions and attach the statements the instructions list for Question 1. Then list on Schedule K the distributions made to each beneficiary, by tier.

Why fill Form 1041-N on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

When and where to file, signatures and payment

Due date

The instructions say ANSTs file Form 1041-N by the 15th day of the 4th month following the close of the tax year. If that date falls on a Saturday, Sunday or legal holiday, file on the next business day.

Where to file

The instructions list this address: Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0027.

Extension

Form 7004 requests an automatic extension of time to file. The instructions say an extension of time to file doesn't extend the time to pay the tax.

Who signs

The trustee or an authorized representative signs. Checking Yes in the signature area lets the IRS discuss the return with the paid preparer who signed it.

Paying a balance

The instructions say payments made to the federal government must be processed electronically, and point to IRS.gov/Payments, EFTPS and same-day wire.

Late filing penalty

The instructions describe a penalty of 5% of the tax due for each month or part of a month the return isn't filed, up to 25%. If it is more than 60 days late, the minimum is the smaller of $525 or the tax due.

Who files Form 1041-N?

  • Trustees of electing ANSTs

    The instructions say the trustee of any electing ANST having any taxable income, or having gross income of at least $600 for the tax year, files Form 1041-N for that year.

  • Trusts making the section 646 election

    The trustee makes the election by signing Form 1041-N for the trust's first tax year, filed by the due date including extensions. The instructions say it then applies to all later years and can't be revoked.

  • Sponsoring Alaska Native Corporation

    The ANST gives a copy of Schedule K to the sponsoring Alaska Native Corporation (ANC) by the Form 1041-N due date. The instructions say the sponsoring ANC, not the ANST, gives beneficiaries any required information.

  • Paid preparers

    A person paid to prepare the return signs the Paid Preparer Use Only section and enters the PTIN and the firm's name, address, EIN and phone number.

  • Not for periods of exemption

    The instructions say an ANST recognized as exempt under section 501(a) uses Form 990-T for an elective payment election and should not file Form 1041-N for a period in which the trust is exempt.

The instructions say any reference to "you" means the trustee of the trust. The return is filed for the trust by its trustee; it is not an individual return.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 1041-N

What is an Alaska Native Settlement Trust?

The instructions define an ANST as a settlement trust within the meaning of section 3(t) of the Alaska Native Claims Settlement Act (ANCSA).

How is the section 646 election made?

The trustee signs Form 1041-N in the signature block on page 1, and the return is filed by the due date, including extensions, for the trust's first tax year. The instructions say the election then applies to all later years and can't be revoked.

What tax rate does Form 1041-N use?

The instructions say an electing ANST pays tax at the lowest rate specified for single individuals (10%). With net capital gain or qualified dividends, Part IV of Schedule D applies a 0% rate on adjusted net capital gain.

Do beneficiaries get a copy of Schedule K?

The instructions say the ANST gives a copy of Schedule K to the sponsoring ANC and isn't required to provide information to beneficiaries. The sponsoring ANC gives beneficiaries any required information.

Can the trust deduct its distributions?

No. The instructions say an electing ANST isn't allowed an income distribution deduction, though it can claim an exemption deduction, and that no deduction is allowed for distributions to beneficiaries on line 9.

Does an electing ANST pay estimated tax?

The instructions say an ANST generally pays estimated income tax if it expects to owe at least $1,000 after subtracting withholding and credits, and refer to Form 1041-ES.

What if the trust's address changes after filing?

The instructions point to Form 8822-B to notify the IRS of the new address.