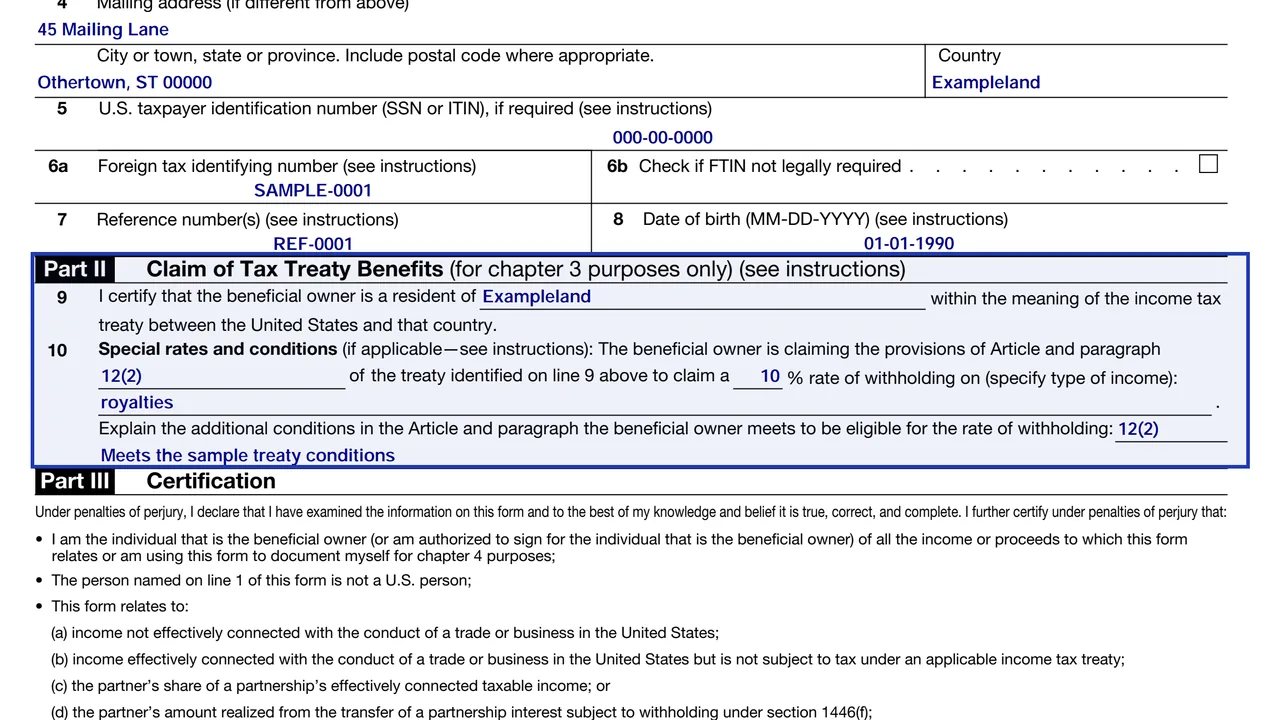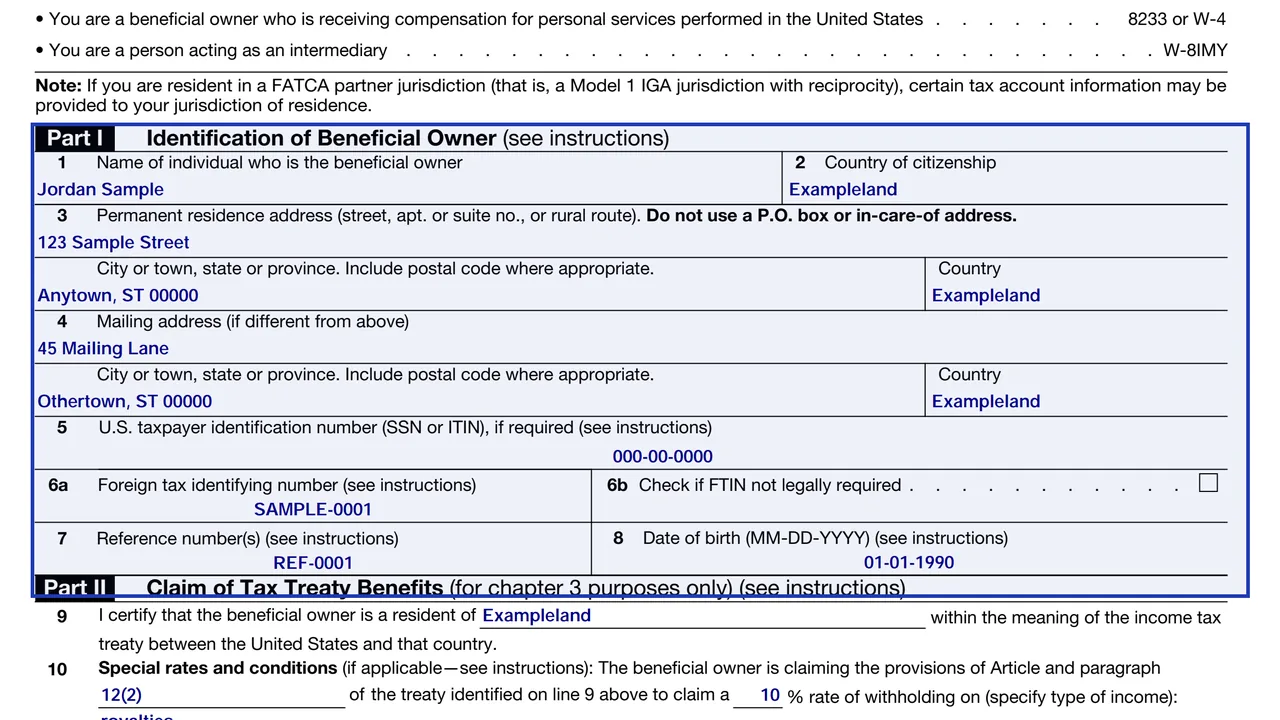
Part I: Identification of beneficial owner
Lines 1 to 8: your name, country of citizenship, permanent residence address, mailing address, U.S. taxpayer identification number, foreign tax identification number, reference numbers and date of birth.
W-8
Certificate of Foreign Status of Beneficial Owner for United States Tax Withholding and Reporting (Individuals)
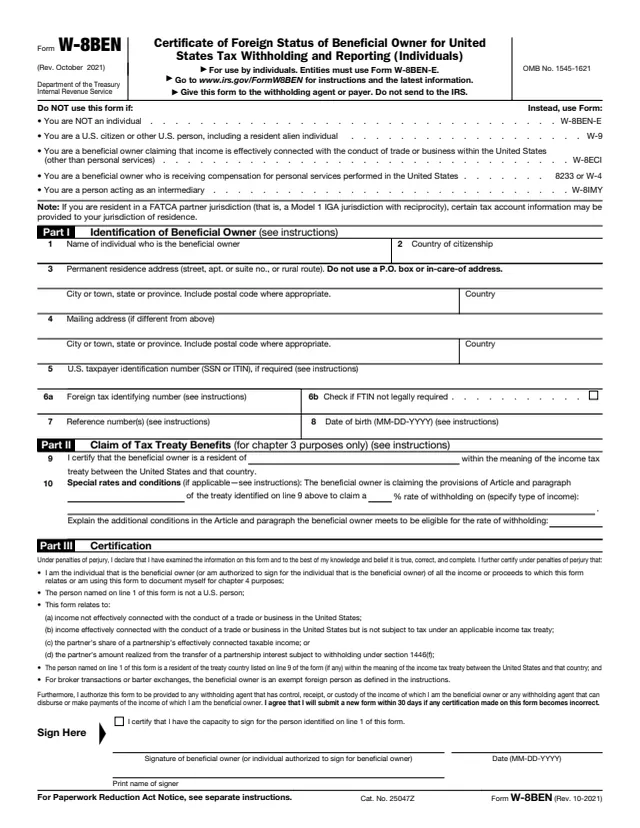
Form W-8BEN is how a foreign individual tells a U.S. payer that they are not a U.S. person, so the payer can apply the correct U.S. tax withholding. It also lets you claim a reduced rate or exemption under a tax treaty between the United States and your country of residence.
You give the form to the person who asked for it: a payer, a platform crediting your account, a bank or brokerage, or a partnership allocating income to you. You do not send it to the IRS. It should be provided before the payment is made or credited, and a separate form is generally needed for each withholding agent.
It is the foreign counterpart of Form W-9. If you are a U.S. citizen or resident alien, you give a W-9 instead.
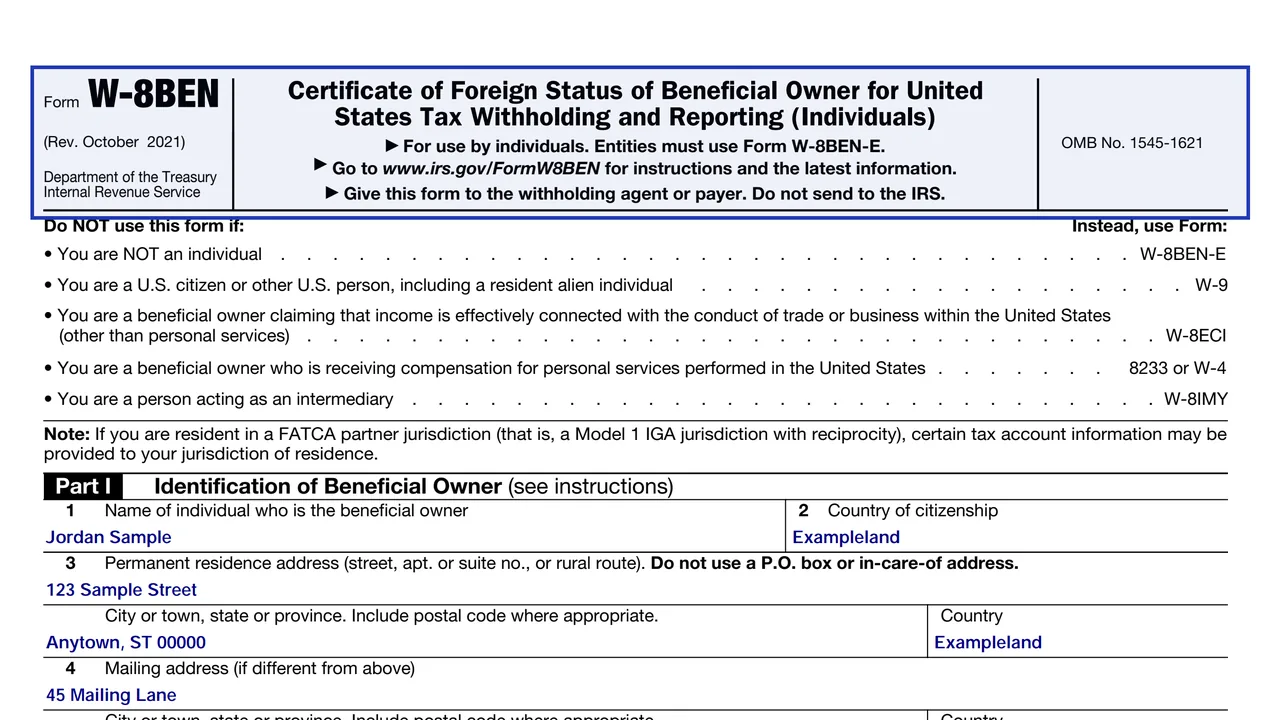
Lines 1 to 8: your name, country of citizenship, permanent residence address, mailing address, U.S. taxpayer identification number, foreign tax identification number, reference numbers and date of birth.
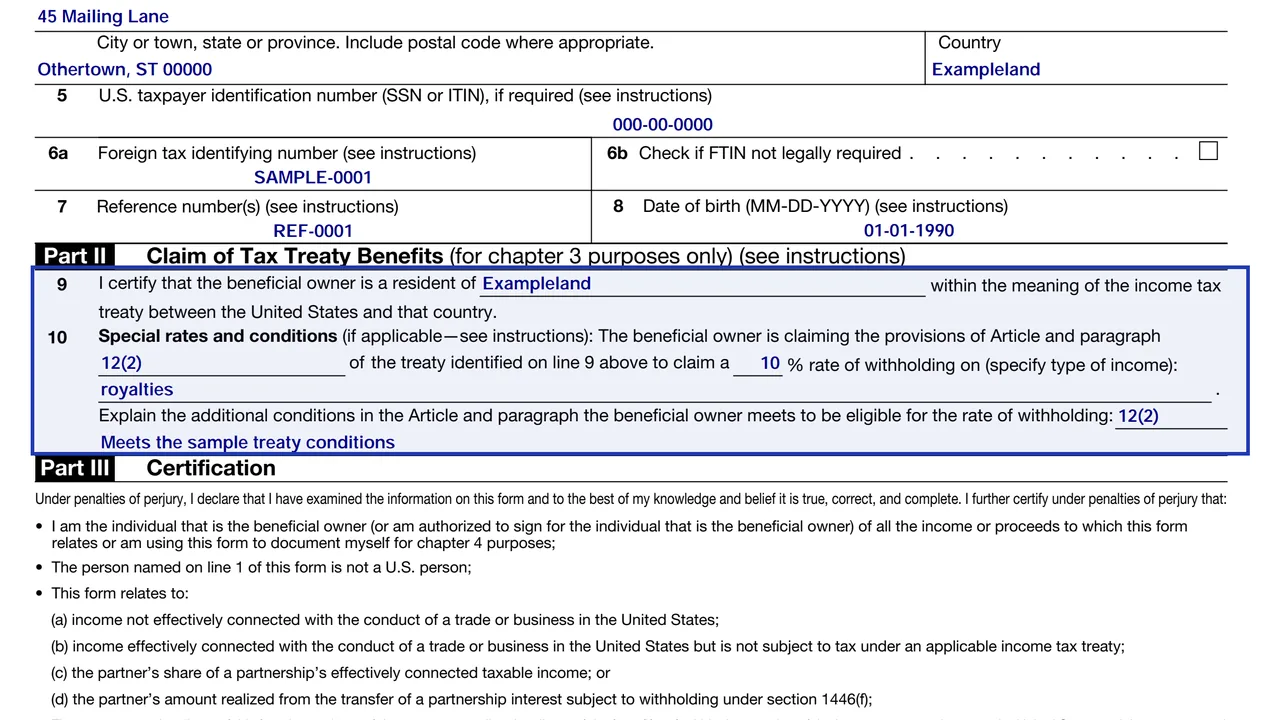
Line 9 is the country where you claim residence for treaty purposes. Line 10 is the special rates and conditions explanation, required only for certain treaty claims.
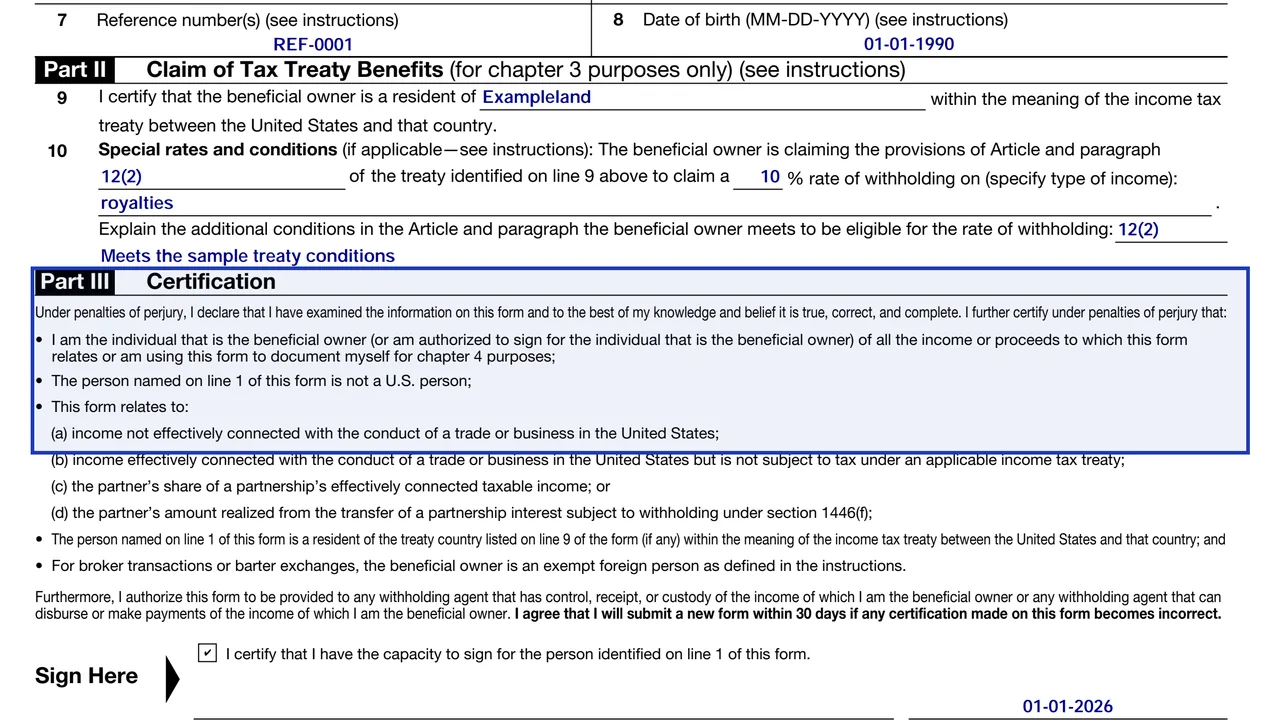
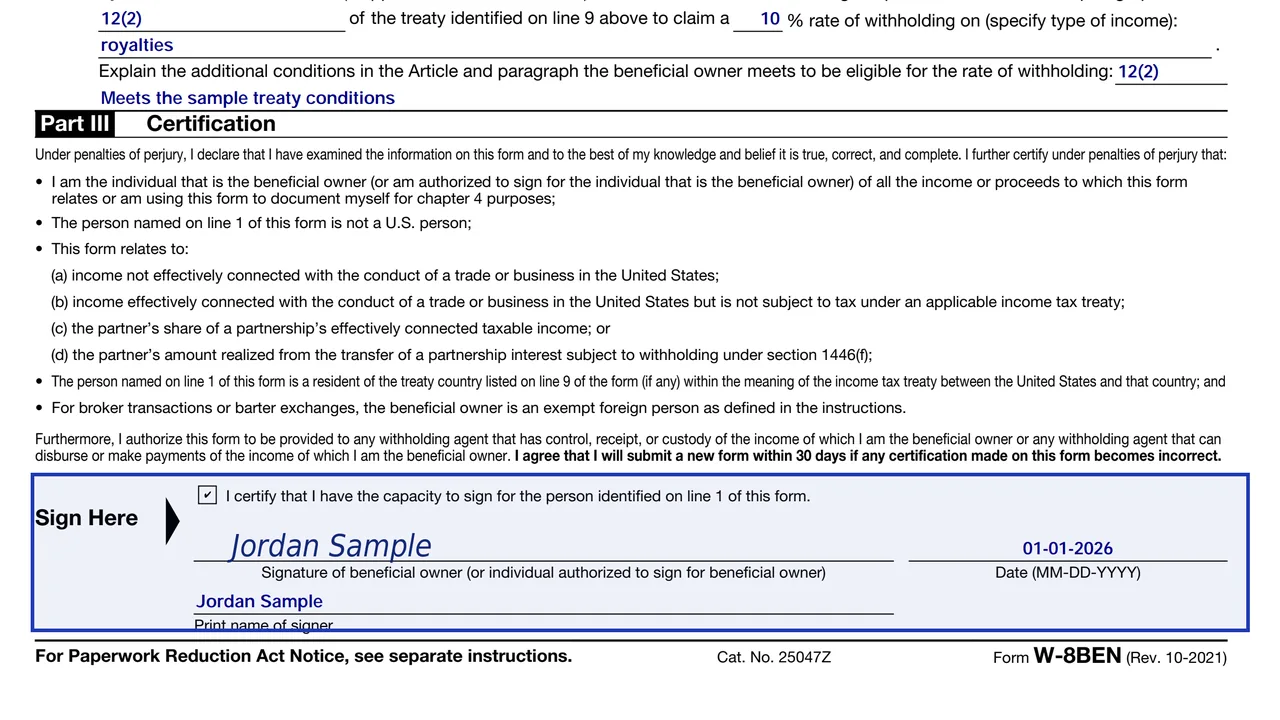
Your signature and date under penalties of perjury, or that of an authorized agent with a valid power of attorney.
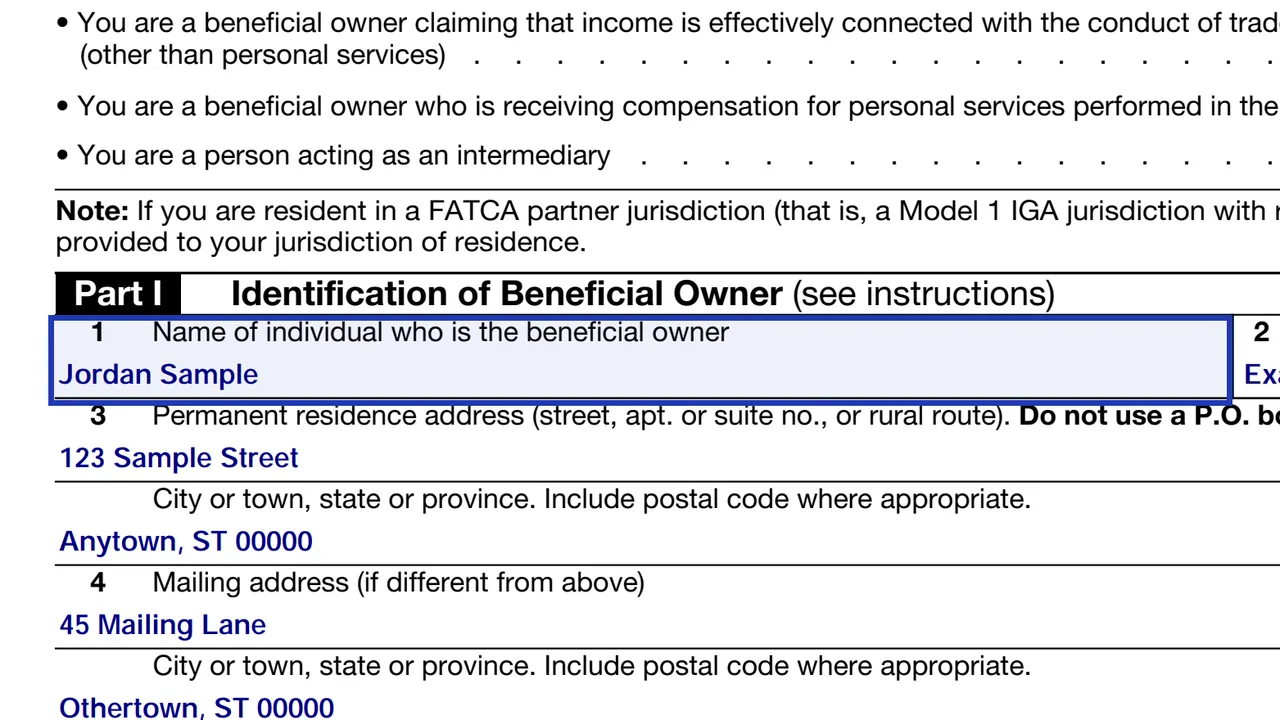
Enter your name.
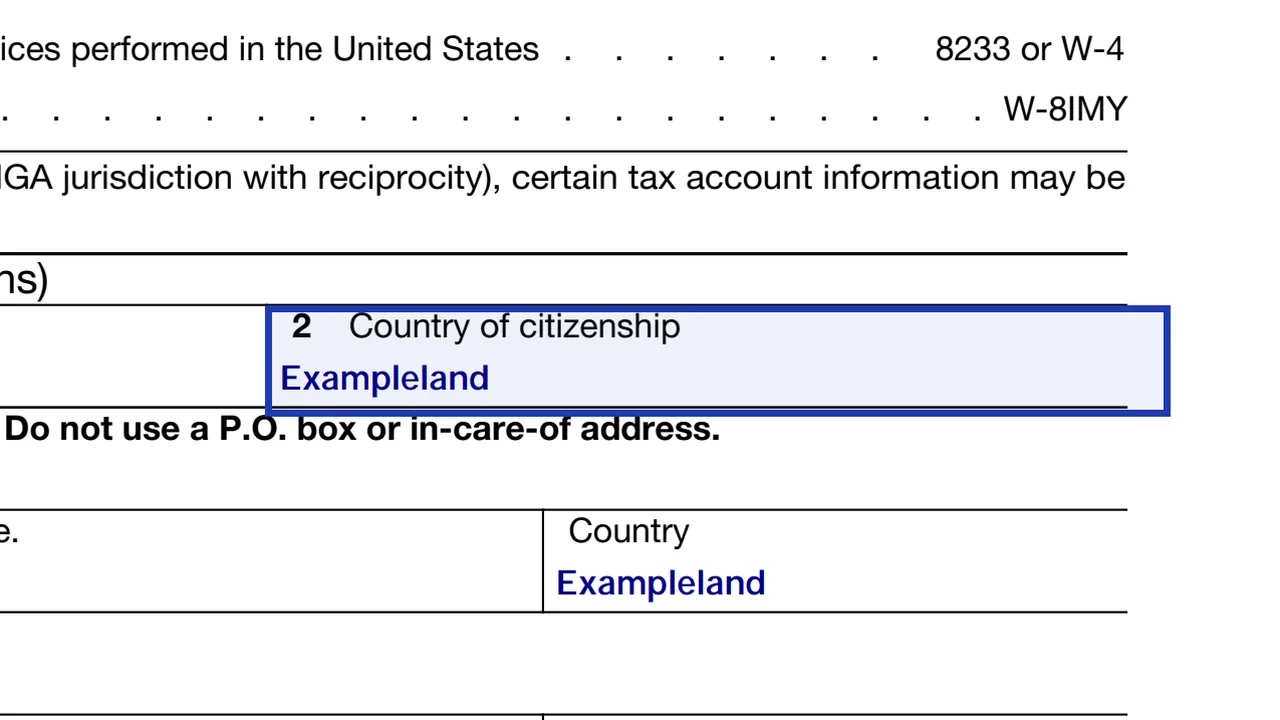
Enter your country of citizenship.
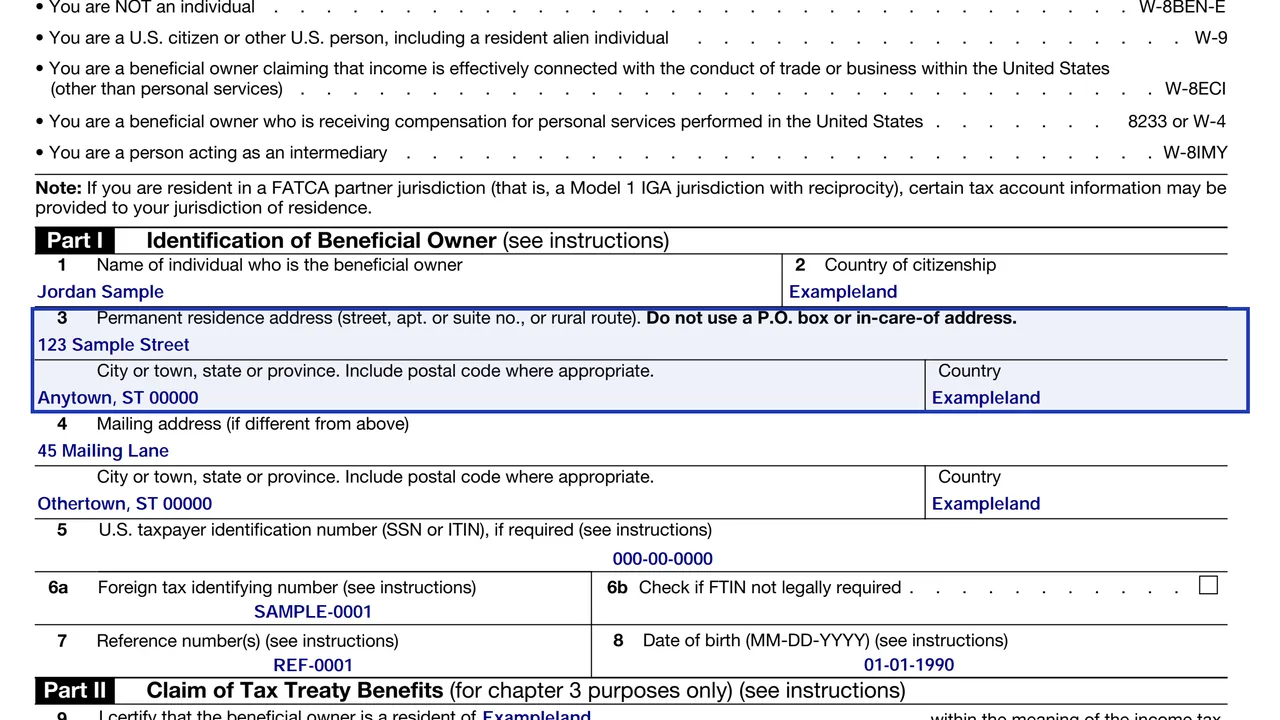
Enter your permanent residence address. It cannot be a post office box or the address of a financial institution.
Enter a mailing address only if it differs from line 3.
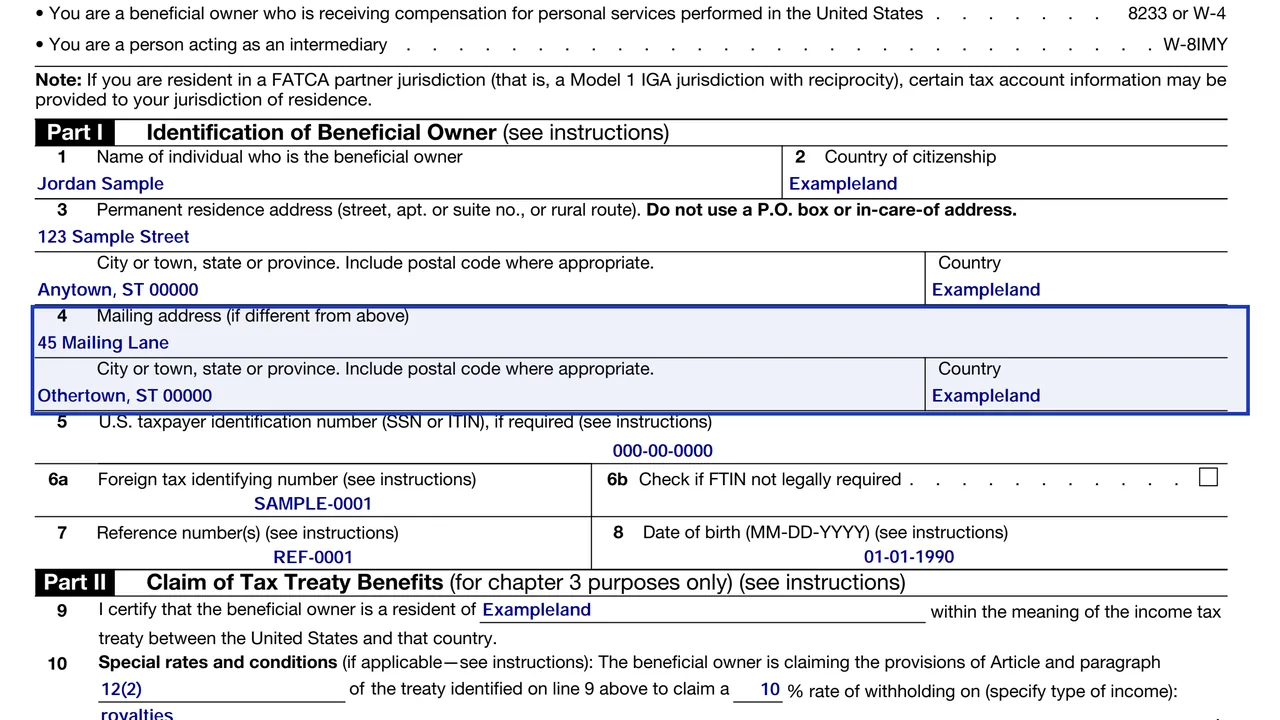
Enter your U.S. Social Security number or ITIN if you have one. An ITIN is generally required for certain treaty claims and for partners in U.S. partnerships.
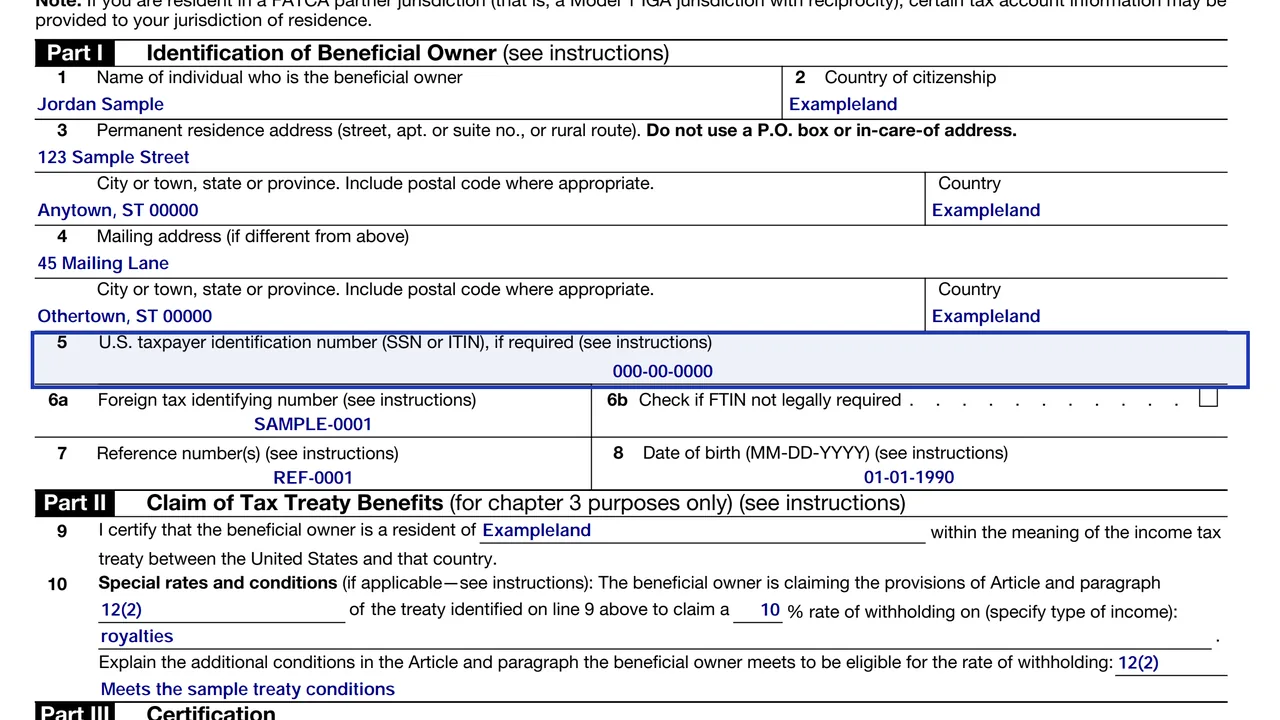
Enter your foreign tax identification number if you hold an account with a U.S. financial institution and receive reportable U.S. source income, unless an exception applies. Check 6b if you are not legally required to obtain one.
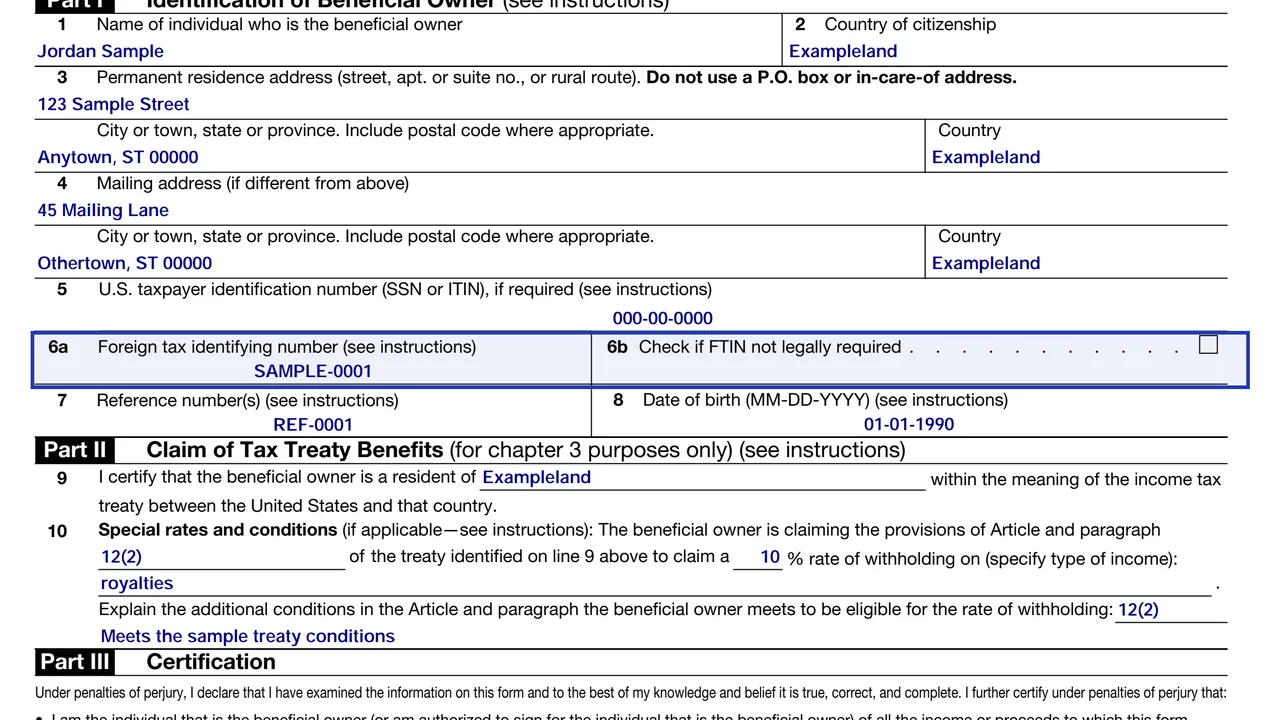
Line 7 is optional reference information for the payer. Line 8 is your date of birth in MM-DD-YYYY format, needed for certain account holders.
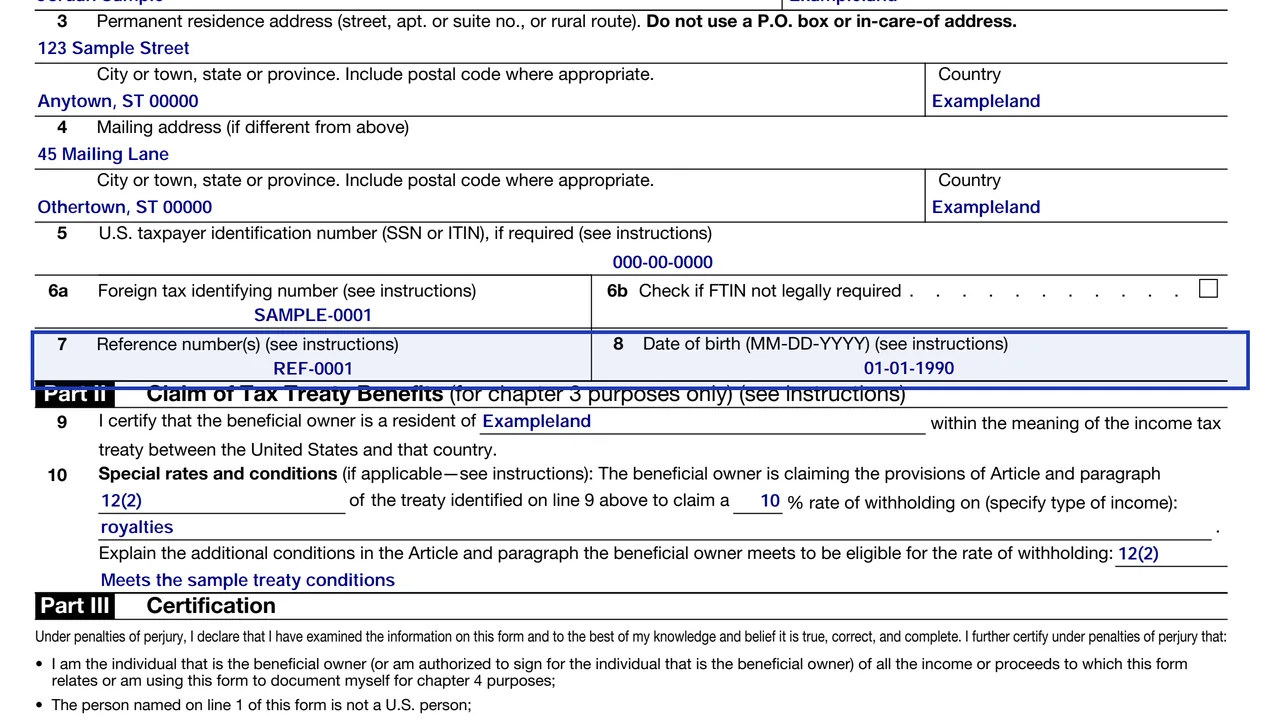
Complete these only if you claim a treaty benefit. Line 10 applies to specific claims such as royalties with multiple rates, business profits not attributable to a permanent establishment, and students and researchers.
Sign and date. Electronic signatures may be accepted, but typing your name alone does not count.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
To the payer or withholding agent that asked for it. Not to the IRS.
A form generally stays valid from the signing date through the last day of the third succeeding calendar year, unless circumstances change. Some forms remain valid indefinitely under certain conditions.
If information on the form becomes incorrect, tell the withholding agent within 30 days and give a new form. Becoming a U.S. citizen or resident alien is one example.
The beneficial owner or an agent with a valid power of attorney must sign and date.
Using a P.O. box as the permanent address, claiming treaty benefits without the required line 10 explanation, and giving this form when a W-9 or W-8BEN-E applies.
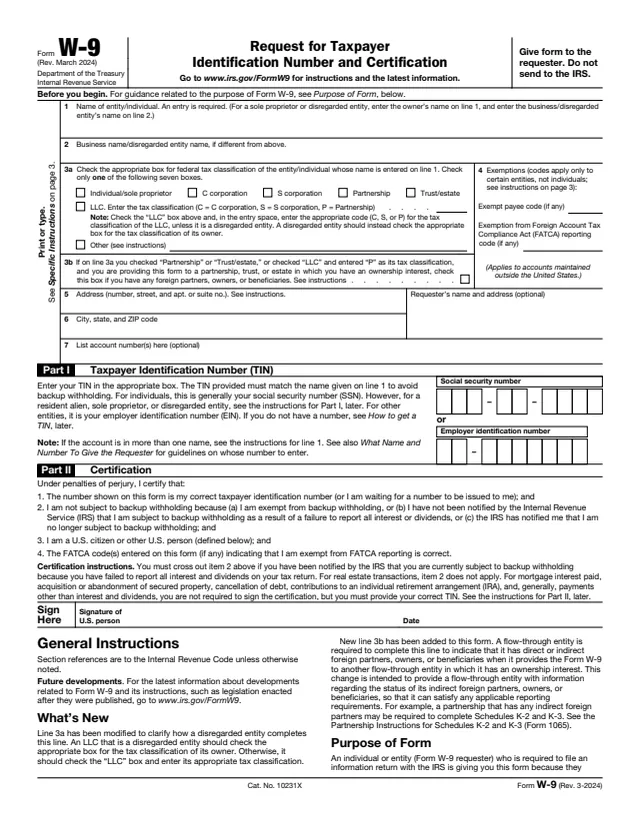
W-9
23 fields, 6 pages
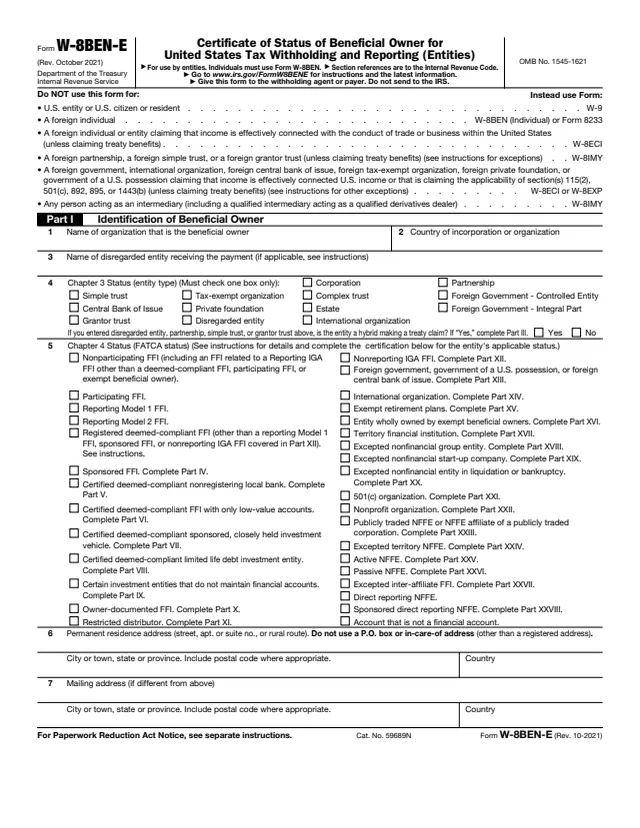
W-8BEN-E
179 fields, 8 pages
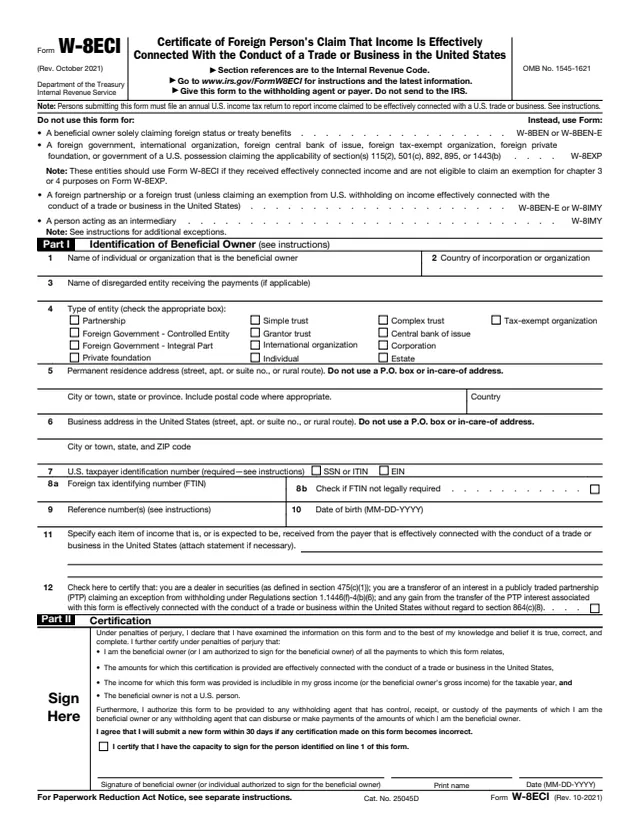
W-8
36 fields, 1 page
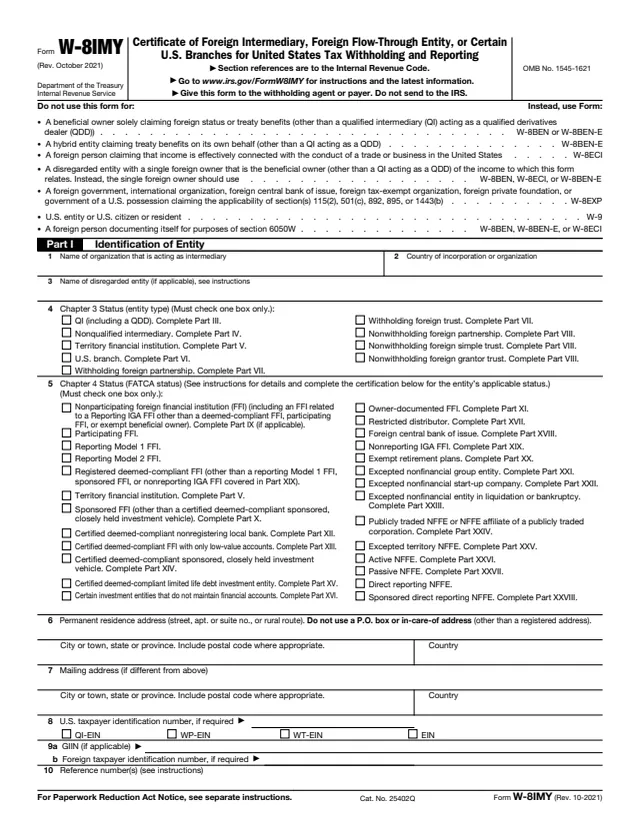
W-8
148 fields, 8 pages
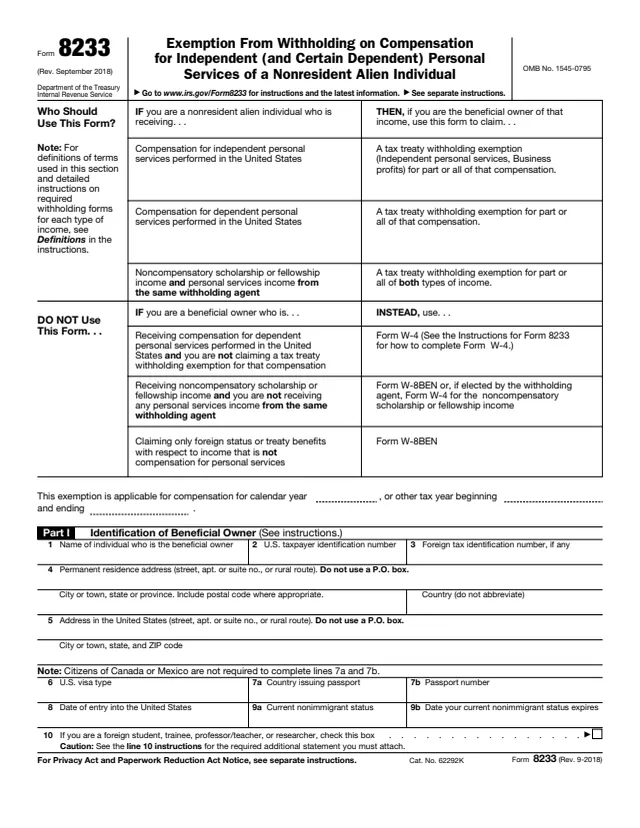
8233
51 fields, 2 pages
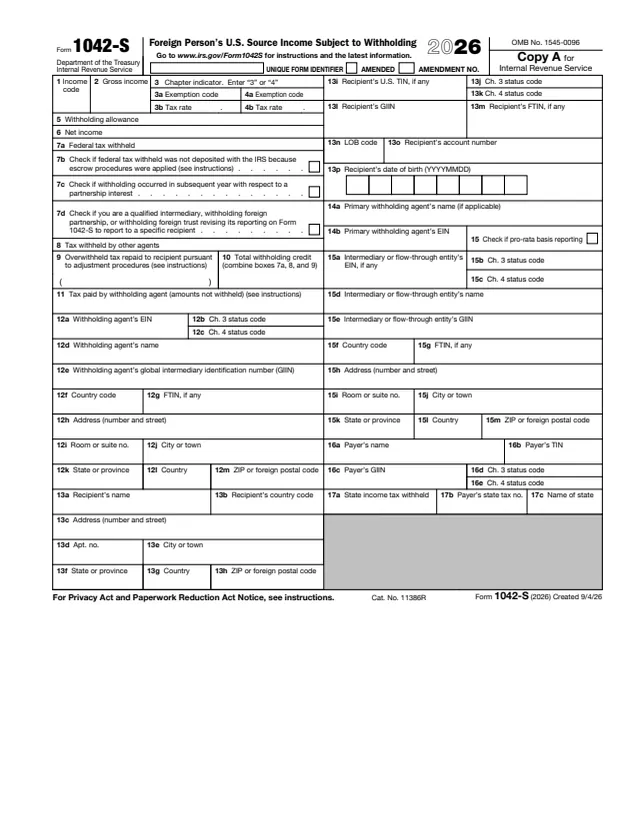
1042-S
300 fields, 7 pages
The instructions say foreign individuals who are the beneficial owner of an amount subject to U.S. withholding give it to the withholding agent or payer when requested.
No tool matches that search.
No. You give it to the payer or withholding agent that requested it.
Generally from the signing date through the last day of the third succeeding calendar year, unless your circumstances change.
Not always. Line 5 asks for an SSN or ITIN, which is generally required for certain treaty claims. Line 6a asks for a foreign tax ID in some cases.
No. Foreign entities use Form W-8BEN-E.
Tell the withholding agent within 30 days of a change that makes the form incorrect, and submit a new form or a Form W-9 as needed.
Typing your name alone is not an electronic signature under the instructions. The agent may accept a qualifying electronic signature.