Line 1: Tier 1 tax
Taxable compensation paid during the quarter subject to Tier 1 tax, times 12.4% (0.124). The instructions say it applies only to the first $184,500 paid during 2026.
CT-2
Employee Representative's Quarterly Railroad Tax Return
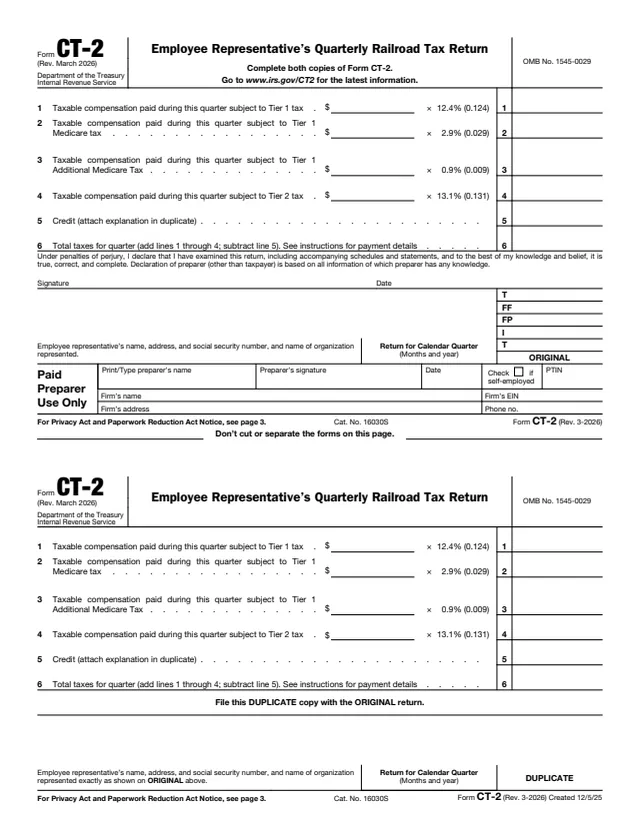
Form CT-2, Employee Representative's Quarterly Railroad Tax Return, is used to report railroad retirement taxes imposed on compensation received by employee representatives. The instructions say the Railroad Retirement Tax Act imposes these taxes on an employee representative based on compensation, and that they are made up of Tier 1 and Tier 2 taxes.
The return is filed each calendar quarter. It has six lines: Tier 1 tax, Tier 1 Medicare tax, Tier 1 Additional Medicare Tax, Tier 2 tax, a credit line and the total. The PDF holds an ORIGINAL and a DUPLICATE copy, and the form says to complete both. The instructions are printed on pages 2 and 3 of the same PDF. This is the March 2026 revision, with the 2026 rates and compensation bases.
You can fill out the PDF free in your browser on this page and download it without an account.
Taxable compensation paid during the quarter subject to Tier 1 tax, times 12.4% (0.124). The instructions say it applies only to the first $184,500 paid during 2026.
Line 2 is Tier 1 Medicare tax at 2.9% (0.029) on all compensation. Line 3 is Tier 1 Additional Medicare Tax at 0.9% (0.009) on compensation over $200,000.
Taxable compensation subject to Tier 2 tax, times 13.1% (0.131). The instructions say it applies only to the first $137,100 paid during 2026.
Line 5 is a credit, with an explanation attached in duplicate. Line 6 is the total taxes for the quarter: lines 1 through 4 minus line 5.
The declaration and signature, the representative's name, address, social security number and organization, and the calendar quarter covered.
The preparer's name, signature, PTIN, firm name, EIN, address and phone, then a DUPLICATE copy of lines 1 to 6 that is filed with the ORIGINAL.
Type or print your name, address, SSN and the name of the labor organization you serve. Enter the months and year of the quarter, for example "Jan., Feb., Mar. 2026."
Multiply the compensation subject to each tax by the rate printed on that line: 12.4%, 2.9%, 0.9% and 13.1%. The instructions give the 2026 limits for each line.
Enter a credit for tax, penalty or interest overpaid for an earlier quarter and attach two copies of a detailed statement. The instructions say not to include a credit for Additional Medicare Tax overpaid for an earlier year.
Add lines 1 through 4 and subtract line 5. The instructions ask for payment through EFTPS or IRS Direct Pay. A check or money order is payable to "United States Treasury" and shows your SSN, "Form CT-2" and the quarter, such as "1Q 2026."
You or your authorized agent sign the ORIGINAL copy. A paid preparer also signs by hand and enters a PTIN and the firm's name and EIN.
Fill in the DUPLICATE copy with the same amounts and the name block exactly as shown on the ORIGINAL. The form says not to cut or separate the forms on that page.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Send both the ORIGINAL and DUPLICATE to the Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999-0049. The instructions suggest making an extra copy for your records.
January to March: May 31, 2026. April to June: August 31, 2026. July to September: November 30, 2026. October to December: February 28, 2027. A due date on a weekend or legal holiday moves to the next business day.
The instructions say a return received after the due date is treated as on time if properly addressed, with enough postage, and postmarked by the U.S. Postal Service or sent by an IRS-designated private delivery service by the due date.
When taxable compensation payments stop completely, write "Final Return" at the top of Form CT-2 and on the duplicate copy.
The instructions say the law provides a penalty for late filing or late payment unless there is reasonable cause, and to send an explanation with a late return. Interest is charged on taxes paid late.
The instructions say records relating to employee representative taxes are kept for at least 4 years after the taxes are due or were paid, whichever is later.
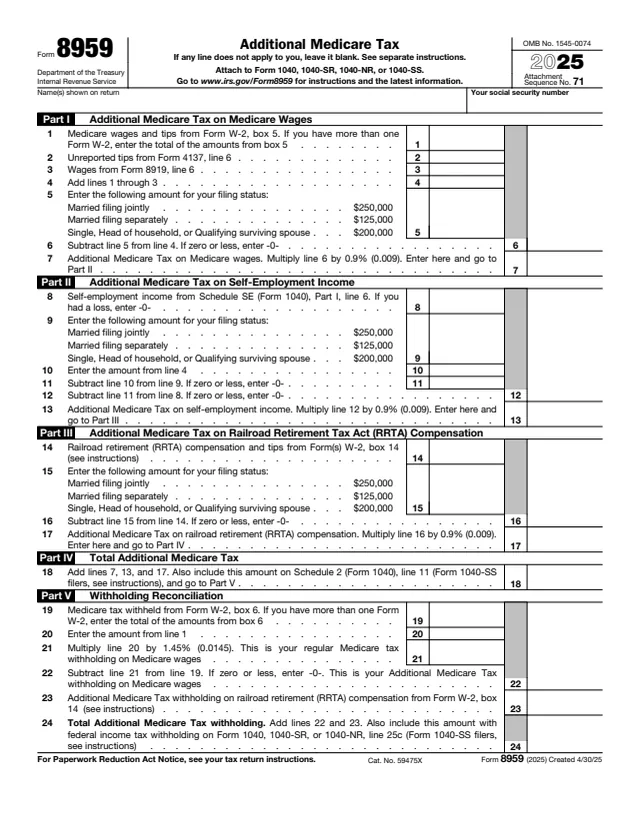
8959
26 fields, 1 page
1040-X
166 fields, 2 pages
W-12
85 fields, 3 pages
CT-1
80 fields, 3 pages
CT-1
330 fields, 6 pages

1040
199 fields, 2 pages
The instructions say the return is filed by an employee representative, starting with the first quarter in which taxable compensation is paid for services as an employee representative.
No tool matches that search.
Railroad retirement taxes imposed on compensation received by employee representatives: Tier 1, Tier 1 Medicare, Tier 1 Additional Medicare and Tier 2 taxes.
The instructions list Tier 1 at 12.4% on the first $184,500, Tier 1 Medicare at 2.9% with no base limit, Additional Medicare Tax at 0.9% on compensation over $200,000, and Tier 2 at 13.1% on the first $137,100.
For 2026 quarters the instructions list May 31, 2026, August 31, 2026, November 30, 2026 and February 28, 2027.
To the Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999-0049, with both the ORIGINAL and DUPLICATE copies.
The instructions say to continue filing for each quarter, even if no taxable compensation is paid, and to file a final return when payments stop completely.
The instructions ask for payment through EFTPS or IRS Direct Pay. They note that from October 17, 2025, Form CT-2 filers can't create new EFTPS accounts, and those not enrolled by then pay using IRS Direct Pay.
The instructions say an employee representative who pays any Additional Medicare Tax during the year completes and files Form 8959 with the federal income tax return.