Header
EIN, RRB number, name as shown on the latest Form CT-1, address, the calendar year of the return being corrected and the date errors were discovered.
CT-1
Adjusted Employer's Annual Railroad Retirement Tax Return or Claim for Refund
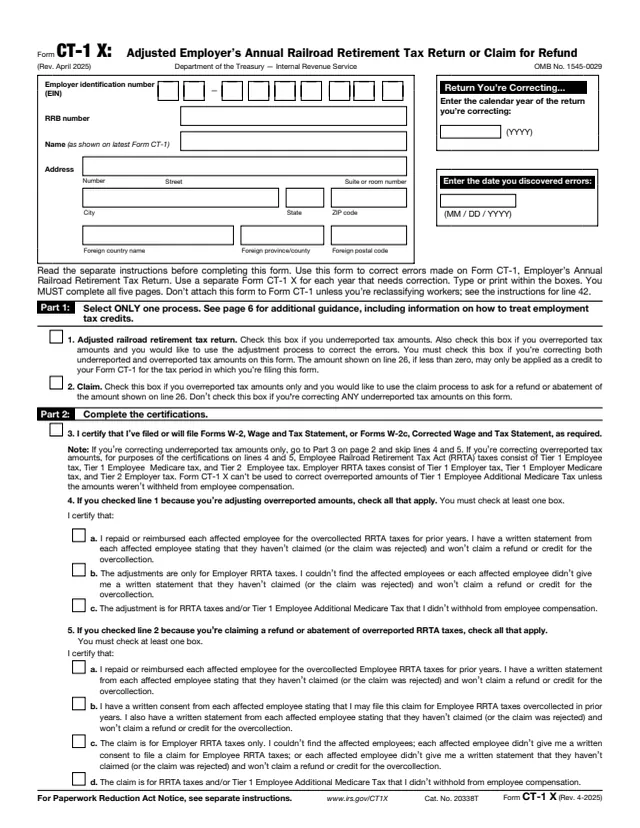
Form CT-1 X is the Adjusted Employer's Annual Railroad Retirement Tax Return or Claim for Refund. The IRS About page says to use it to correct errors on a Form CT-1 previously filed. Form CT-1 is the Employer's Annual Railroad Retirement Tax Return.
The instructions say it corrects Tier 1 Employee tax, Tier 1 Employee Medicare tax, Tier 1 Employee Additional Medicare Tax and Tier 2 Employee tax, the matching Tier 1 and Tier 2 Employer taxes, and amounts reported for the credit for qualified sick and family leave compensation and the COBRA premium assistance credit. Each line has columns for the corrected amount, the amount originally reported, the difference and the tax correction.
The employer picks one of two processes: an adjusted railroad retirement tax return or a claim for refund or abatement. The form says to use a separate Form CT-1 X for each year that needs correction and to complete all five pages. This page has the April 2025 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
EIN, RRB number, name as shown on the latest Form CT-1, address, the calendar year of the return being corrected and the date errors were discovered.
Line 1 for an adjusted railroad retirement tax return and line 2 for a claim for refund or abatement. The form says to check only one.
Line 3 certifies that Forms W-2 or W-2c have been or will be filed. Lines 4 and 5 hold certifications about repaying employees, employee consents or Employer RRTA taxes only, for overreported amounts.
Lines 6 to 40, each tied to a Form CT-1 line, covering Tier 1 and Tier 2 taxes on compensation and sick pay, tax adjustments and credits. Line 21 is a subtotal and line 26 the total.
Line 41 for corrections that include both underreported and overreported amounts, line 42 for reclassified workers, and line 43 for a detailed explanation of how the corrections were determined.
The declaration, the signer's printed name, title, date and best daytime phone, and the Paid Preparer Use Only section.
Enter the EIN, RRB number, name and address, the calendar year of the Form CT-1 being corrected and the date errors were discovered. The instructions say to repeat the name, EIN and year at the top of pages 2 to 5.
Check line 1 for the adjustment process or line 2 for the claim process. The form says line 1 is checked when correcting both underreported and overreported amounts, and line 2 only when correcting overreported amounts.
Check line 3. The form says to skip lines 4 and 5 when correcting underreported tax amounts only. For overreported amounts, check each box on line 4 or line 5 that applies.
For each line that changes, enter the corrected total in column 1, the amount originally reported or as previously corrected in column 2 and the difference in column 3. The instructions say to show a negative amount with a minus sign. Lines that don't apply stay blank.
Combine lines 21 through 25c of column 4. The form says a positive amount is the amount owed, paid by the time the return is filed. A negative amount is credited to Form CT-1 under line 1, or refunded or abated under line 2.
Check lines 41 and 42 if they apply, explain each correction on line 43, then sign on page 5. The instructions say any later discovery dates and related errors are also reported on line 43.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file by the due date of the return for the return period in which the error was discovered and pay the amount owed by the time of filing.
Under the adjustment process the instructions say to file more than 90 days before the period of limitations expires. A claim can be filed any time before it expires. In the last 90 days, only the claim process is available.
The instructions say overreported taxes can generally be corrected within 3 years of the date Form CT-1 was filed or 2 years from the date the tax was paid, whichever is later, and underreported taxes within 3 years of filing.
The instructions list Department of the Treasury, Internal Revenue Service Center, Cincinnati, OH 45999-0007. A private delivery service uses Ogden-Internal Revenue Submission Processing Center, 1973 Rulon White Blvd., Ogden, UT 84201.
The form says not to attach it to Form CT-1 unless reclassifying workers. Errors only in the tax liabilities in Part II of Form CT-1 or on Form 945-A are not corrected on Form CT-1 X, the instructions say.
The instructions say the amount on line 26 can be paid through EFTPS, the preferred method, or by check or money order payable to "United States Treasury."
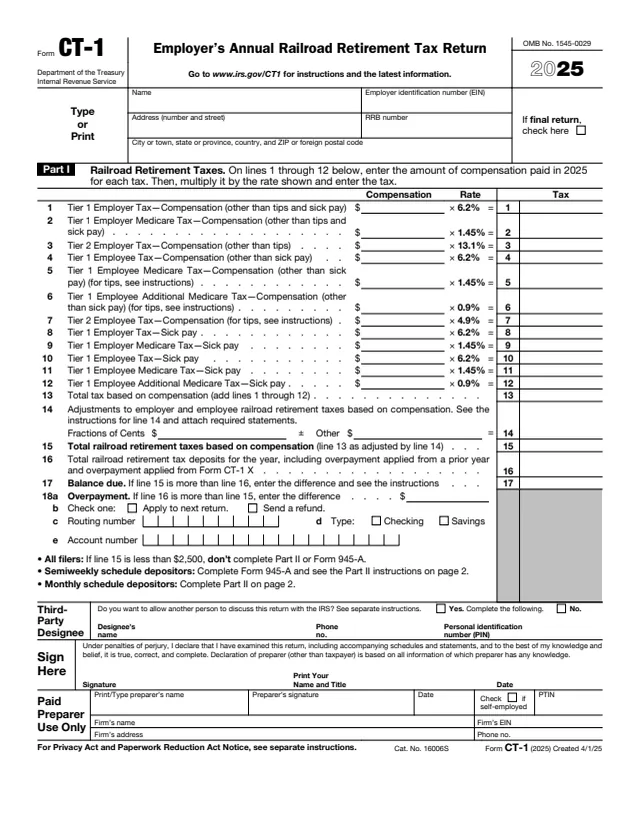
CT-1
80 fields, 3 pages
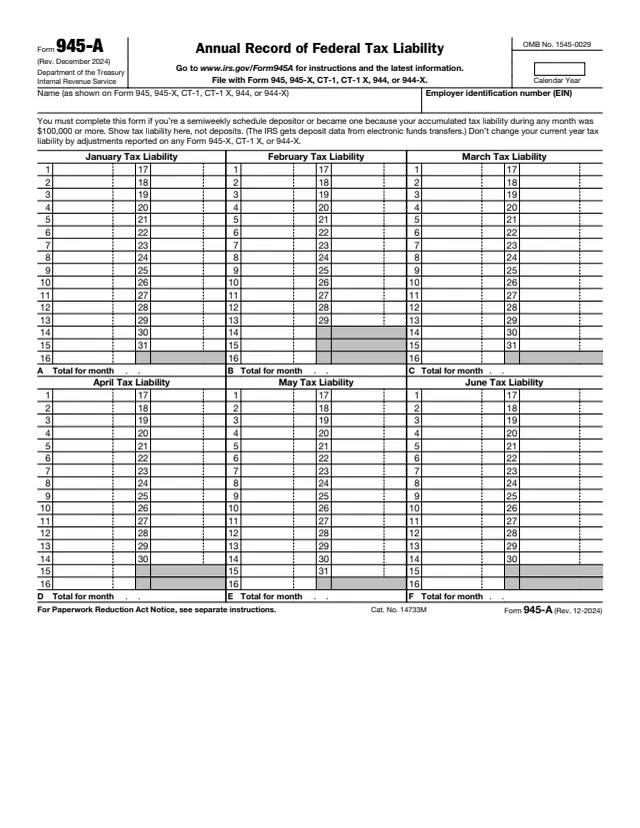
945-A
748 fields, 2 pages
W-2c
540 fields, 9 pages
843
85 fields, 2 pages
943-X
321 fields, 6 pages
941-X
352 fields, 6 pages
Form CT-1 X is filed by the employer that filed Form CT-1. It is not a form railroad employees file.
No tool matches that search.
The About page says to use it to correct errors on a Form CT-1, Employer's Annual Railroad Retirement Tax Return, that was previously filed.
No. The form says to use a separate Form CT-1 X for each year that needs correction.
Line 1 is the adjustment process, where a credit is applied to Form CT-1 for the period of filing. Line 2 is the claim process, used only for overreported amounts to ask for a refund or abatement.
The instructions say to use Form 843, Claim for Refund and Request for Abatement, for assessed interest or penalties, not Form CT-1 or Form CT-1 X.
The instructions say Form CT-1 is considered filed on the last day in February of the following year if it was filed before that date.
The instructions say a refund claim can't be filed to correct Tier 1 Employee Additional Medicare Tax actually withheld from employees.