Heading
The tax year, trust name and EIN, the other filer's name and SSN or EIN, address, boxes for a pending application or changed address, the FMV of assets at the beginning of the operator's tax year, and the Return filed by boxes.
990-BL
Information and Initial Excise Tax Return for Black Lung Benefit Trusts and Certain Related Persons
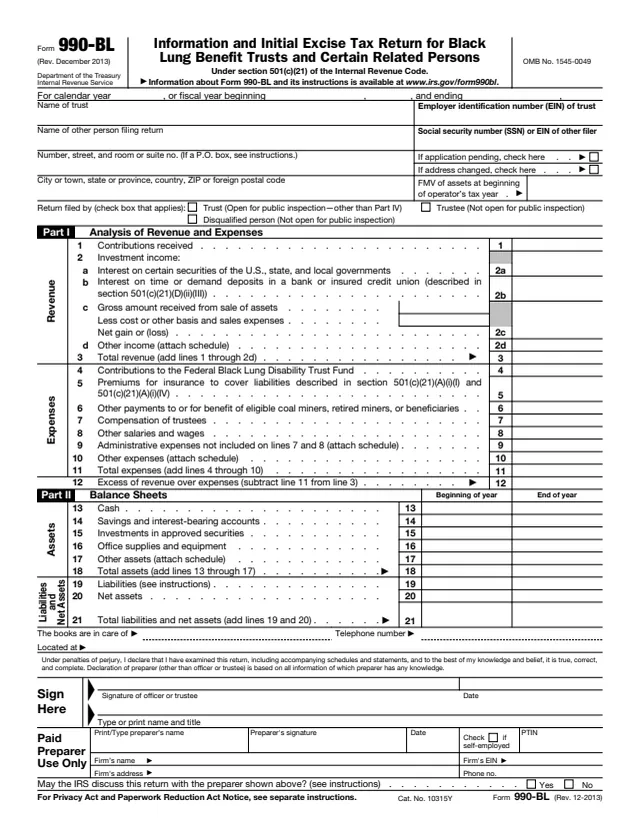
Form 990-BL is generally used by black lung benefit trusts to meet the reporting requirements of Internal Revenue Code section 6033. The form is titled Information and Initial Excise Tax Return for Black Lung Benefit Trusts and Certain Related Persons, under section 501(c)(21). If initial taxes under section 4951 (self-dealing) or section 4952 (taxable expenditures) are imposed on the trust or certain related parties, Schedule A (Form 990-BL), printed on page 3 of the same PDF, reports them.
The filer is the trust, a trustee or a disqualified person. The instructions say the trustee files Form 990-BL for a trust exempt from tax under section 501(a) and described in section 501(c)(21), unless the trust normally has gross receipts in each tax year of not more than $50,000. A trustee or disqualified person liable for tax completes the heading and signature area and attaches Schedule A.
This page hosts the December 2013 revision. The instructions, revised 01/2020, say they are for use with that revision. You can fill out the PDF free in your browser on this page and download it without an account.
The tax year, trust name and EIN, the other filer's name and SSN or EIN, address, boxes for a pending application or changed address, the FMV of assets at the beginning of the operator's tax year, and the Return filed by boxes.
Lines 1 to 12: contributions, investment income, contributions to the Federal Black Lung Disability Trust Fund, insurance premiums, payments to or for eligible miners and beneficiaries, trustee pay, salaries and other expenses.
Lines 13 to 21: cash, savings, investments in approved securities, office supplies and other assets, liabilities and net assets at the beginning and end of the year.
Lines 22 to 26: changes to the governing instrument, self-dealing with disqualified persons, taxable expenditures, corrective action, and officers, directors and trustees with their compensation.
Persons who contributed $5,000 or more, and whether contributions exceeded the contributor's maximum allowable deduction under section 192. The form says this part is not open for public inspection.
Initial taxes on self-dealing (section 4951) and taxable expenditures (section 4952), with columns at 10% and 2½% of the amounts involved, and a summary of total tax due. It is not open for public inspection.
Enter the trust's name, address and EIN. A trustee or disqualified person filing for tax also enters their own name and SSN or EIN. The instructions say the application pending, address change and FMV boxes are filled in only when the return is filed for a trust.
Line 1 is the total contributions received under section 192 from the coal mine operator who established the trust. Lines 4 to 10 cover payments to the Federal Black Lung Disability Trust Fund, insurance, benefits, pay and expenses, with schedules where the form asks for them.
Use the trust's regular accounting method. The instructions say line 19 includes only liabilities such as approved black lung claims due but not paid and accrued trustee fees, and line 21 equals total assets on line 18.
Attach a conformed copy of any change to the governing instrument not reported before. A No on line 23b leads to Schedule A, Part I, Section A, and a Yes on line 24 leads to Section B. Explain any uncorrected acts.
List every officer, director and trustee, even if unpaid, with average hours per week, compensation, benefit plan contributions and expense allowances. The instructions say phrases such as "as needed" are unacceptable for hours, and -0- goes in columns (c), (d) and (e) if nothing was paid.
For tax years ending on or after December 31, 2018, the instructions say filers enter "N/A" on Part IV, line 1 instead of contributor names and addresses. The authorized trustee signs, along with any paid preparer.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the return, with Schedule A if tax is due, is filed on or before the 15th day of the 5th month following the close of the filer's tax year, or the next business day if that falls on a weekend or legal holiday.
Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999. For a private delivery service address, the instructions point to IRS.gov/PDSstreetAddresses.
An extension of time to file is requested on Form 8868, Application for Automatic Extension of Time To File an Exempt Organization Return.
The 01/2020 instructions give $20 a day ($105 a day for a large organization), up to the smaller of $10,500 ($53,000 for a large organization) or 5% of gross receipts, and say these amounts are adjusted for inflation.
The instructions say the return is generally available for public inspection, except Part IV and Schedule A, and the trust makes it available for 3 years from the due date, including extensions, or the filing date if later.
When contributions exceed the section 192 deduction, the instructions say the contributor may be required to file Form 6069 and pay the tax imposed by section 4953(a).
6069
112 fields, 3 pages
8868
47 fields, 2 pages
4506-A
40 fields, 1 page
W-12
85 fields, 3 pages
941
116 fields, 3 pages
990
1,075 fields, 12 pages
The form has three "Return filed by" boxes: Trust, Trustee and Disqualified person. The instructions say to check only the box that applies.
No tool matches that search.
The instructions say the trustee files it for a section 501(c)(21) trust unless the trust normally has gross receipts in each tax year of not more than $50,000. Those trusts may file an annual electronic notice instead.
Only when initial tax is due under section 4951 or 4952. The instructions say Schedule A is attached to a completed Form 990-BL, cannot be filed separately, and is not filed if no tax is due.
The instructions say 10% of the amount involved for each act of self-dealing on the disqualified person, 2.5% on a trustee who knowingly participated, 10% of each taxable expenditure on the trust, and 2.5% on a trustee who knowingly agreed.
The return filed by a trust is generally open for public inspection. The instructions say Part IV and Schedule A are not, and the inspection rules do not apply to a return filed by a trustee or disqualified person.
No. The instructions say that for tax years ending on or after December 31, 2018, filers enter "N/A" on Part IV, line 1 for each contribution of $5,000 or more.
The Instructions for Form 990-BL, revised 01/2020, say they are for use with the December 2013 revision of Form 990-BL hosted on this page.