Lines A to D: foreign entities
For a form tied to a foreign entity's information return, such as Form 5471: the entity's name and numbers, and yes or no questions on CFC group membership and a safe harbor election.
8990
Limitation on Business Interest Expense Under Section 163(j)
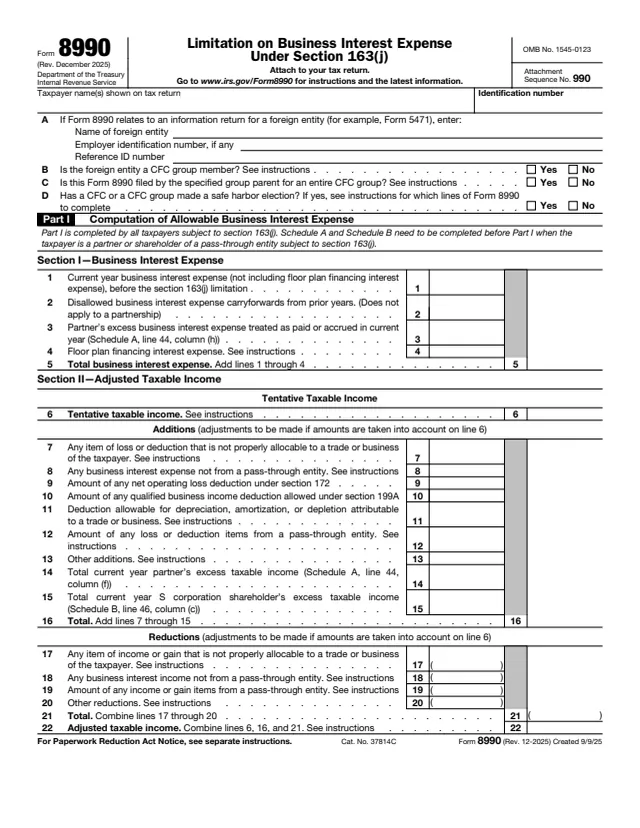
Form 8990 applies the section 163(j) limitation on business interest expense. The About page says to use it to calculate the amount of business interest expense you can deduct and the amount to carry forward to the next year.
The instructions say the deduction for the year is limited to the sum of business interest income, the applicable percentage of adjusted taxable income (ATI) and floor plan financing interest expense. The applicable percentage is 30%. Business interest expense that is not allowed is carried forward to the following year.
Individuals, corporations, partnerships and S corporations can all be filers, and the form is attached to the tax return. The December 2025 revision reinstates the add-back for depreciation, amortization or depletion on line 11. You can fill it out free in your browser on this page and download the result without an account.
For a form tied to a foreign entity's information return, such as Form 5471: the entity's name and numbers, and yes or no questions on CFC group membership and a safe harbor election.
Lines 1 to 5 total business interest expense, including carryforwards and floor plan financing interest. Lines 6 to 22 build adjusted taxable income from tentative taxable income with additions and reductions.
Lines 23 to 25 total business interest income. Lines 26 to 31 apply the percentage to ATI, show the allowed deduction on line 30 and the disallowed amount on line 31.
Lines 32 to 37, completed only by a partnership subject to section 163(j): excess business interest expense, excess taxable income and excess business interest income allocated to partners.
Lines 38 to 42, completed only by an S corporation subject to section 163(j): excess taxable income and excess business interest income allocated to shareholders.
Page 3 lists each partnership (Schedule A, lines 43 and 44) or S corporation (Schedule B, lines 45 and 46) by name and EIN with its excess items.
Complete them only when the form relates to an information return for a foreign entity, such as Form 5471. The instructions say to prepare the whole form in U.S. dollars.
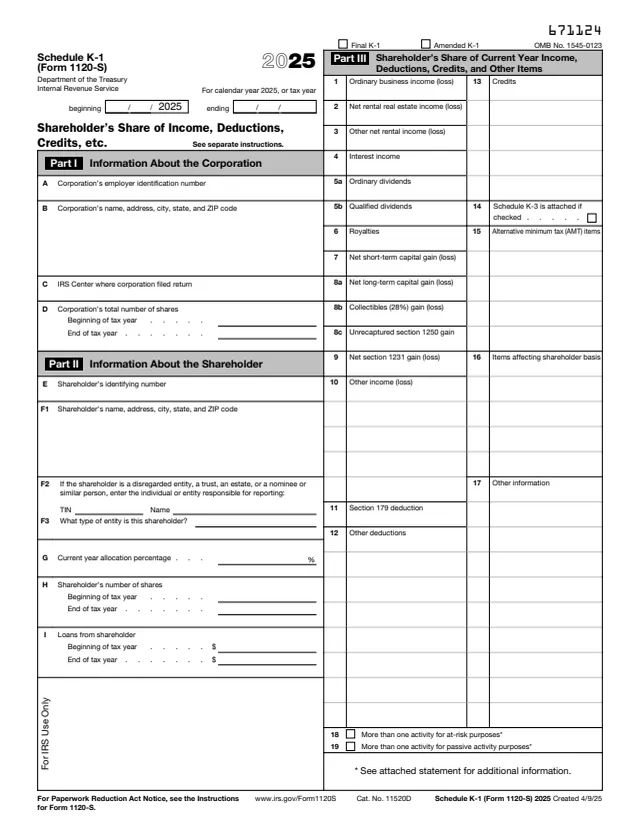
Partners enter the excess items reported to them on Schedule K-1 for each partnership on line 43. S corporation shareholders do the same for each S corporation on line 45.
Enter current year business interest expense without floor plan financing interest or interest from an excepted trade. Line 2 is the prior year's disallowed amount, which does not apply to a partnership.
Enter tentative taxable income on line 6, then the additions such as depreciation, amortization or depletion on line 11 and the reductions, to reach ATI on line 22.
Line 26 is ATI times 30%. The instructions say line 30 is the smaller of line 29 or line 5. Line 31, the disallowed amount, goes to next year's line 2, or to line 32 for a partnership.
A partnership completes Part II and an S corporation completes Part III. The instructions point to the Form 1065 and Form 1120-S instructions for reporting the items to owners.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. For an applicable CFC, the instructions say a Form 8990 is attached with each Form 5471.
The instructions say that for tax years beginning in 2025, a taxpayer meets the gross receipts test with average annual gross receipts of $31 million or less for the 3 prior tax years, if it is not a tax shelter.
A real property, farming or certain utility trade or business may elect out of the limitation with a statement attached to a timely filed original return. The instructions say the election is irrevocable.
The line 31 amount is used on next year's Form 8990, line 2, except for partnerships, whose excess business interest expense is allocated to partners.
The instructions say P.L. 119-21 restored the add-back for depreciation, amortization or depletion for tax years beginning after 2024 and expanded floor plan financing to certain trailers and campers.

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages

1065
111 fields, 1 page
1120-S
114 fields, 1 page

5471
437 fields, 6 pages

1120
481 fields, 6 pages
The instructions say a taxpayer with business interest expense, a disallowed business interest expense carryforward, or current or prior year excess business interest expense generally files Form 8990, unless an exclusion applies.
No tool matches that search.
The About page says it calculates the business interest expense you can deduct and the amount to carry forward to the next year, under section 163(j).
The instructions say it is 30% of adjusted taxable income. Line 26 multiplies the ATI on line 22 by that percentage.
The instructions say a small business taxpayer without excess business interest expense from a partnership, and a filer with interest expense only from excepted trades or businesses.
The instructions say a pass-through entity allocating excess taxable income or excess business interest income to its owners files Form 8990 regardless of whether it has interest expense.
It is shown on line 31 and carried forward to the following year's line 2. For a partnership, the amount goes to Part II, line 32 and is allocated to partners.
The instructions say line 11 was revised to reinstate the depreciation, amortization or depletion add-back for ATI, and floor plan financing now includes certain trailers and campers.