Identifier and report type
A three-digit identifier for paper filings and boxes for a corrected, amended or voided report, or no accounts to report.
8966
FATCA Report
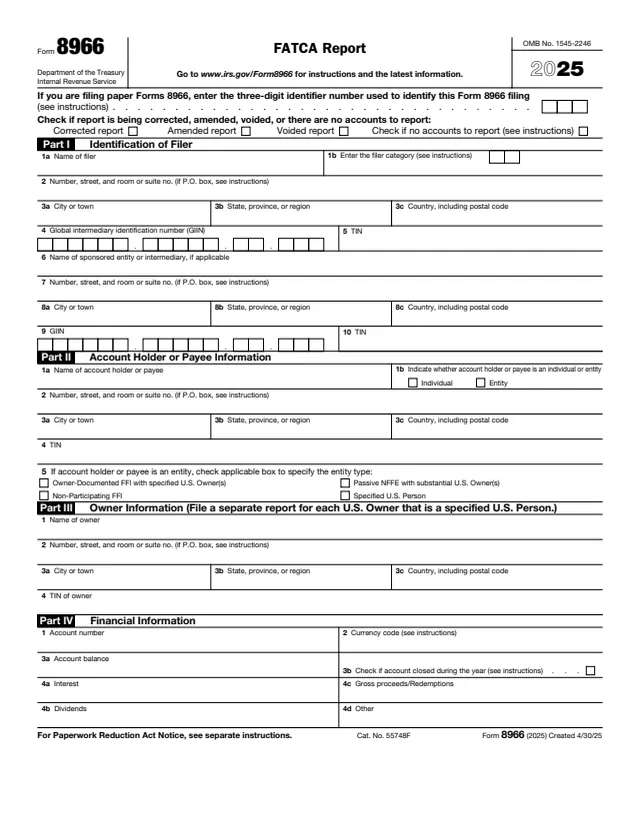
Form 8966 is the FATCA Report. The About page says it is filed to report information with respect to certain U.S. accounts, substantial U.S. owners of passive non-financial foreign entities (NFFEs), specified U.S. persons that own certain debt or equity interests in owner-documented foreign financial institutions (ODFFIs), and certain other accounts based on the filer's chapter 4 status. This page covers the 2025 form.
The filers are financial institutions and certain withholding agents, not the account holders. The instructions list participating foreign financial institutions (PFFIs), registered deemed-compliant FFIs, Reporting Model 2 FFIs, qualified intermediaries, withholding foreign partnerships and trusts, Direct Reporting NFFEs, Sponsoring Entities and trustees of Trustee-Documented Trusts. The report is filed with the IRS.
The instructions say an entity that is a financial institution files Form 8966 electronically. Paper forms, where allowed, go with Form 8966-C. You can fill out Form 8966 free in your browser on this page and download the result without an account.
A three-digit identifier for paper filings and boxes for a corrected, amended or voided report, or no accounts to report.
The filer's name, filer category, address, GIIN and TIN on lines 1a to 5, and a sponsored entity or intermediary on lines 6 to 10.
Name, individual or entity, address and TIN, plus boxes for the entity type such as a passive NFFE with substantial U.S. owners or a specified U.S. person.
Name, address and TIN of a U.S. owner. The form says to file a separate report for each U.S. owner that is a specified U.S. person.
Account number, currency code, account balance, a box for an account closed during the year, and interest, dividends, gross proceeds or redemptions and other amounts.
On page 2, one pooled reporting type is checked, with the number of accounts, aggregate payment amount, aggregate account balance and currency code.
Paper filers assign each form a unique three-digit number, such as 001. A corrected, amended or voided report reuses the original form's number. Check Corrected report when responding to an IRS notification and Amended report when not contacted by the IRS.
Enter the filer's name and the filer category code from the instructions, such as 01 for a PFFI or 10 for a withholding agent. Enter the mailing address and the GIIN. Line 5 takes a U.S. TIN only when no GIIN is entered, except for a QI, WP or WT.
The instructions say these lines are completed only by a Sponsoring Entity, a trustee of a Trustee-Documented Trust, or a filer paying certain Territory Financial Institutions or certified deemed-compliant FFIs acting as intermediaries.
Use the chart in the instructions to see whether each part applies. Enter the account holder or payee, then each U.S. owner on its own report.
Enter the account number, currency code and balance, and the payment amounts. The instructions allow amounts in U.S. dollars or the account's currency, and say that if amounts are rounded, all of them are rounded.
A PFFI reports accounts of recalcitrant account holders here on a pooled basis, filing a separate Form 8966 for each pooled type. The instructions say to complete lines 1, 2, 4 and 5 and not line 3.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 8966 is filed on or before March 31 of the year following the end of the calendar year being reported. A due date on a weekend or U.S. legal holiday moves to the next business day.
An automatic 90-day extension may be requested on Form 8809-I, no later than the due date. Under certain hardship conditions the IRS may grant an additional 90-day extension.
The instructions say an entity that is a financial institution files electronically, whatever the number of forms. A waiver is requested on Form 8508-I at least 45 days before the due date. Pub. 5124, Pub. 5190 and Pub. 5188 cover electronic filing.
Filers with a waiver, or not required to file electronically, send paper Forms 8966 with Form 8966-C to Internal Revenue Service, FATCA, Stop 6052 AUSC, 3651 South IH 35, Austin, Texas 78741.
The instructions say Form 8966 is not used to report tax withheld under chapter 4. A withholding agent may also file Form 1042 and Form 1042-S.
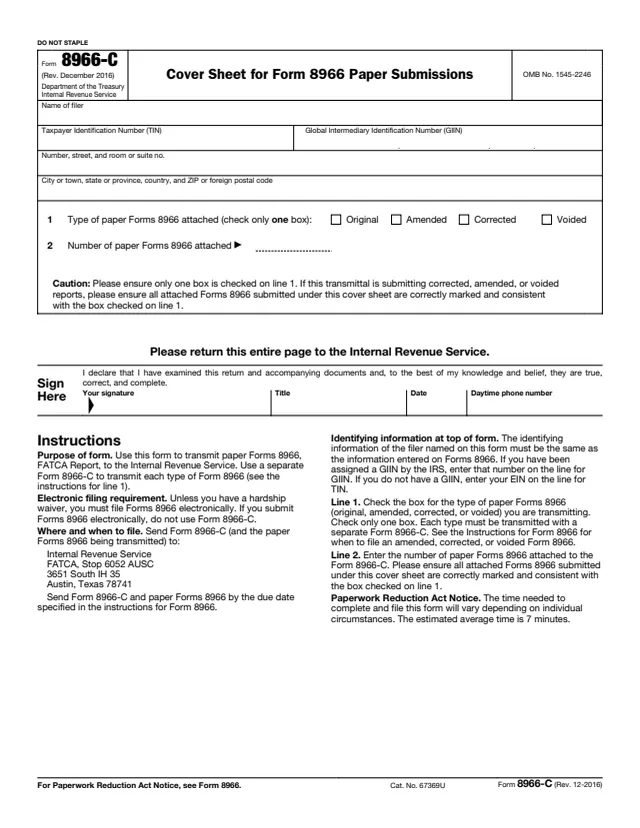
8966-C
15 fields, 1 page
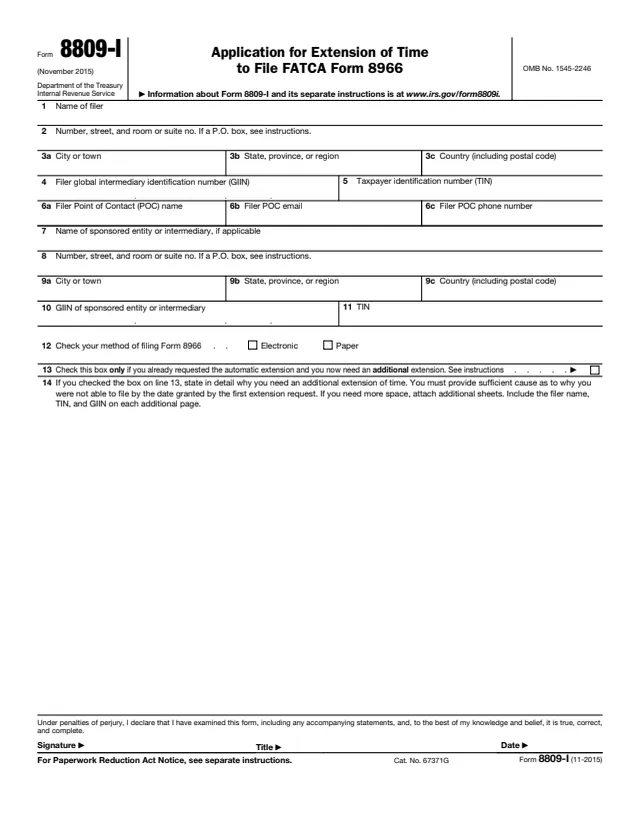
8809-I
28 fields, 1 page
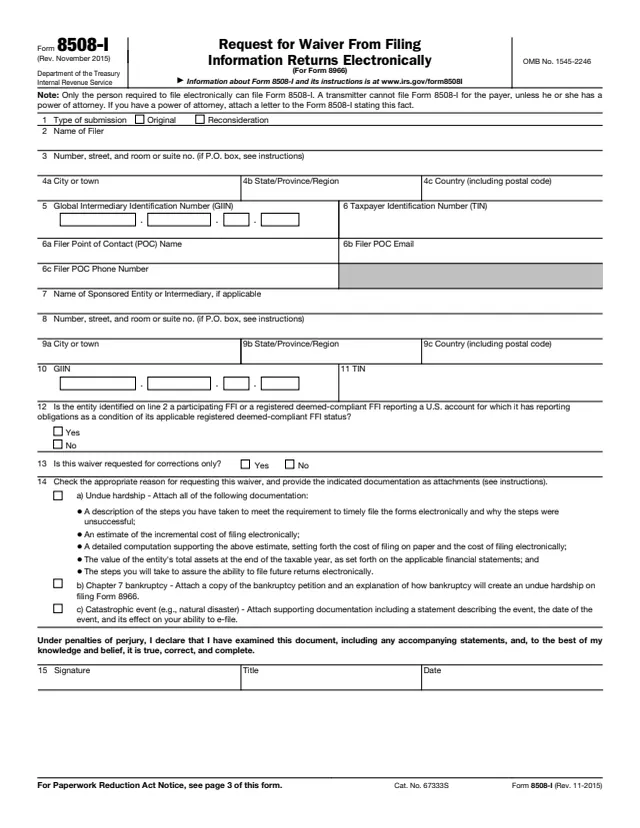
8508-I
33 fields, 4 pages
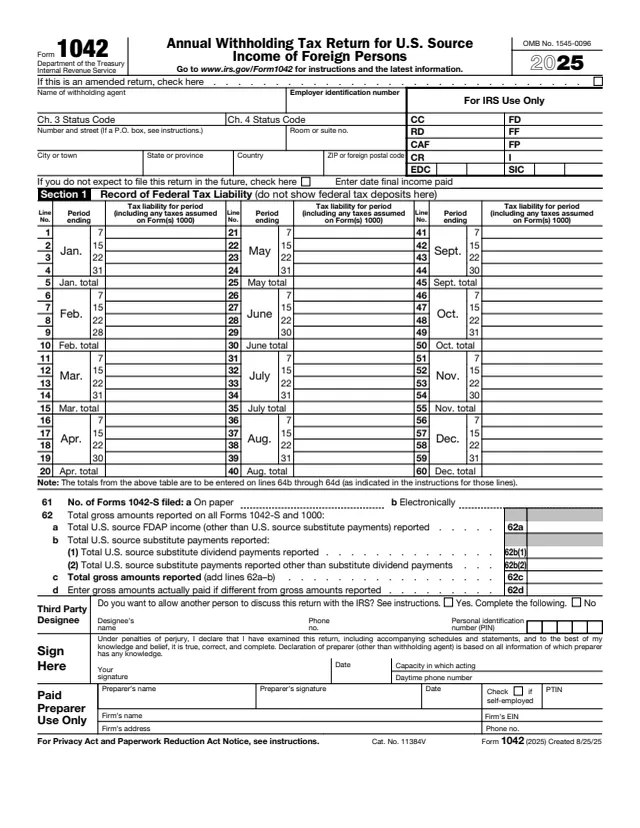
1042
134 fields, 2 pages
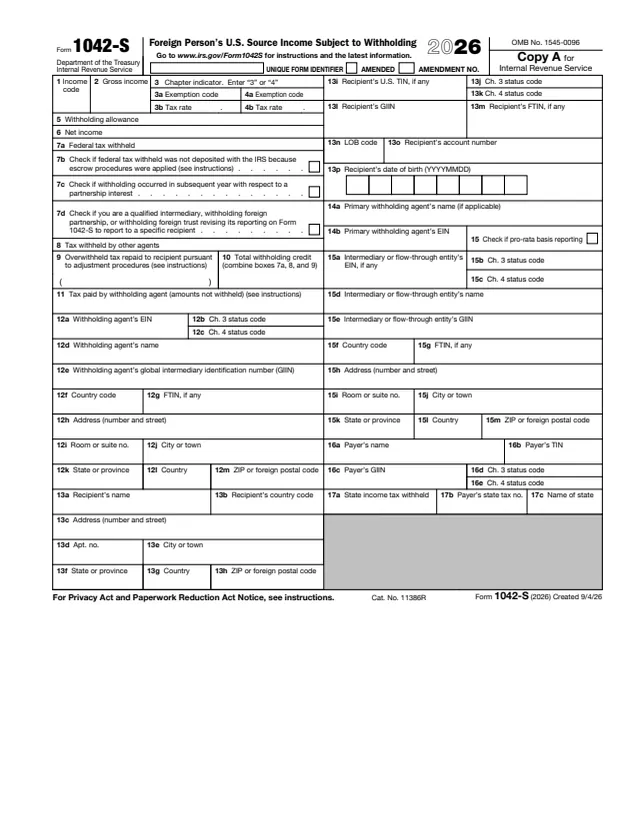
1042-S
300 fields, 7 pages
The instructions list the persons that file Form 8966. Each one reports on accounts or owners it holds information about, and the report goes to the IRS.
No tool matches that search.
The instructions list PFFIs, registered deemed-compliant FFIs, Reporting Model 2 FFIs, QIs, WPs and WTs, Direct Reporting NFFEs, Sponsoring Entities, trustees of Trustee-Documented Trusts and, in certain cases, withholding agents.
The instructions say on or before March 31 of the year following the end of the calendar year for which it is filed, or the next business day if that falls on a weekend or U.S. legal holiday.
Yes. The instructions say an automatic 90-day extension may be requested by filing Form 8809-I, and each branch requesting an extension files a separate Form 8809-I.
The instructions say a financial institution files electronically. Filers with a waiver from Form 8508-I, or not otherwise required to file electronically, may mail paper forms with Form 8966-C.
Check Corrected report when correcting in response to an IRS notification. When the IRS has not made contact, check Amended report and also file a copy of the original marked Voided report.
No. The instructions say tax withheld under chapter 4 is reported on Form 1042 and Form 1042-S, not on Form 8966.