Lines 1 through 3c: filer
The filer's name and mailing address, including city, state, province or region, and country with postal code.
8809-I
Application for Extension of Time to File FATCA Form 8966
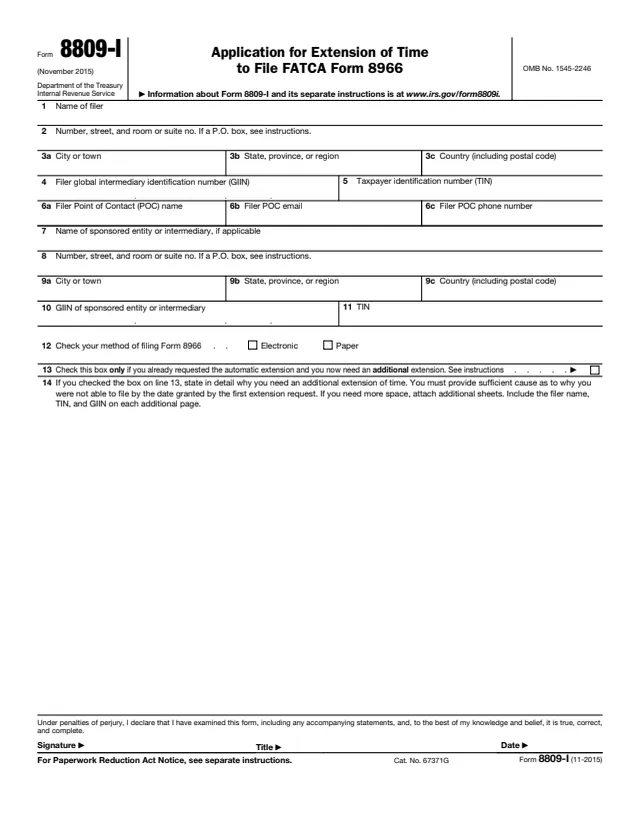
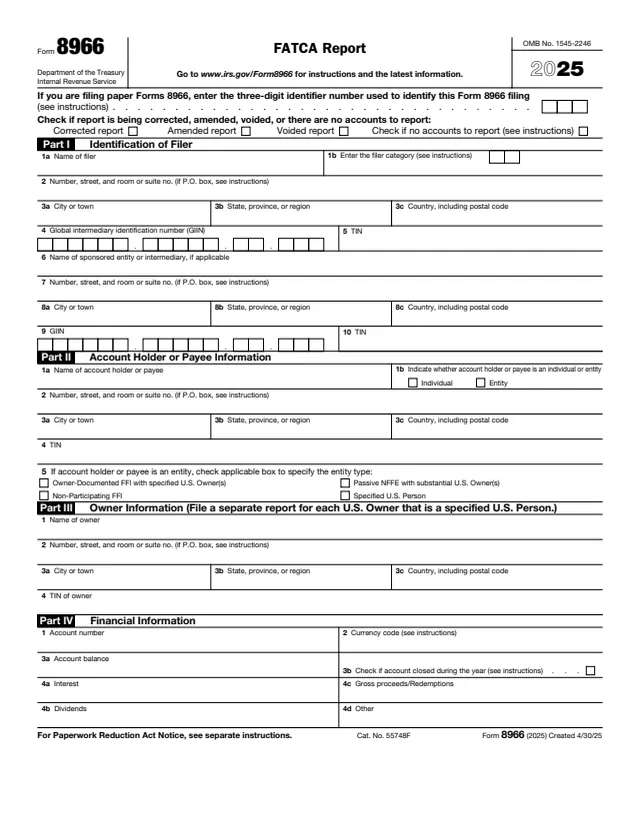
Form 8809-I is the application a filer uses to ask for more time to file Form 8966, the FATCA Report. The instructions say it is used to request an initial or additional extension of time to file Form 8966 for the current tax year.
The filers are FATCA reporting entities, such as financial institutions, Direct Reporting NFFEs, and Sponsoring Entities or trustees reporting for the entities they sponsor. The instructions say a separate request is submitted for each filer, and a separate Form 8809-I is filed for each method of filing Form 8966, electronic or paper.
The instructions describe an automatic extension of 90 days from the original due date, and an additional 90-day extension under a hardship exception that is not automatically granted. You can fill out the form free in your browser on this page and download it without an account.
The filer's name and mailing address, including city, state, province or region, and country with postal code.
The filer's global intermediary identification number (GIIN) on line 4 and its U.S. taxpayer identification number (TIN) on line 5.
The name, email and phone number of a person the IRS can contact if it needs more information.
Name, address, GIIN and TIN of the sponsored entity or intermediary, if applicable.
Two boxes for how Form 8966 will be filed: electronic or paper.
A box for a filer that already requested the automatic extension and now needs more time, and space to explain why, followed by the signature line.
Enter the filer's name and the address where correspondence should be sent. The instructions say to enter a P.O. box only if the post office does not deliver mail to the street address.
Enter the GIIN if the filer has one. A Sponsoring Entity or trustee filing for another entity enters the GIIN from its registration as a Sponsoring Entity or trustee. Enter a TIN if one was issued; the instructions say a TIN is not required to file.
Enter the name, phone number and email of someone familiar with the form whom the IRS can contact.
Complete these only for a Sponsoring Entity or a trustee of a Trustee-Documented Trust. For more than one sponsored entity or trust, the instructions say to list the others in an attachment.
Check electronic or paper. The instructions say to file a separate Form 8809-I for each method.
Check line 13 only after receiving the automatic 90-day extension, and explain on line 14 why more time is needed. The instructions say no signature is required for the automatic extension; an additional extension is signed by the filer or a person authorized to sign for it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to mail a paper Form 8809-I to Internal Revenue Service, FATCA, Stop 6052 AUSC, 3651 South IH 35, Austin, TX 78741.
As soon as the filer knows an extension is needed, but not before January 1 of the filing year, and by the due date of Form 8966. The instructions give that due date as March 31 of the year following the year the report covers, unless a Model 2 IGA sets a different date.
The instructions say the automatic extension is 90 days from the original due date.
The IRS may grant an additional 90-day extension. The instructions say it is filed by the first extended due date, is not automatic, and is generally granted only when extenuating circumstances prevented filing. The IRS notifies the filer whether it is approved or denied.
The instructions say not to send a copy of Form 8809-I or any letters with Form 8966.
The instructions say filers may be subject to a late filing penalty if Form 8966 is filed late without an approved extension.
The instructions say filers who need more time to file Form 8966 with the IRS file Form 8809-I before the due date of Form 8966. It is completed by the reporting entity, not by an individual account holder.
No tool matches that search.
The instructions say it is used to request an initial or additional extension of time to file Form 8966, the FATCA Report, for the current tax year.
The automatic extension is 90 days from the original due date. The IRS may grant an additional 90 days under the hardship exception, which is not automatic.
The instructions say no signature is required for the automatic 90-day extension. A request for an additional extension is signed by the filer or a person authorized to sign on its behalf.
The instructions give Internal Revenue Service, FATCA, Stop 6052 AUSC, 3651 South IH 35, Austin, TX 78741 for a paper form.
No. The instructions say to file a separate Form 8809-I for each method of filing Form 8966.
The instructions say the filer is not required to obtain a TIN to file Form 8809-I if a TIN has not been issued.