Lines A to C: screening questions
SHOP Marketplace premiums and the Marketplace Identifier, the EIN used for employment taxes if different, and whether an earlier return for a tax year beginning after 2013 and before 2024 claimed the credit.
8941
Credit for Small Employer Health Insurance Premiums
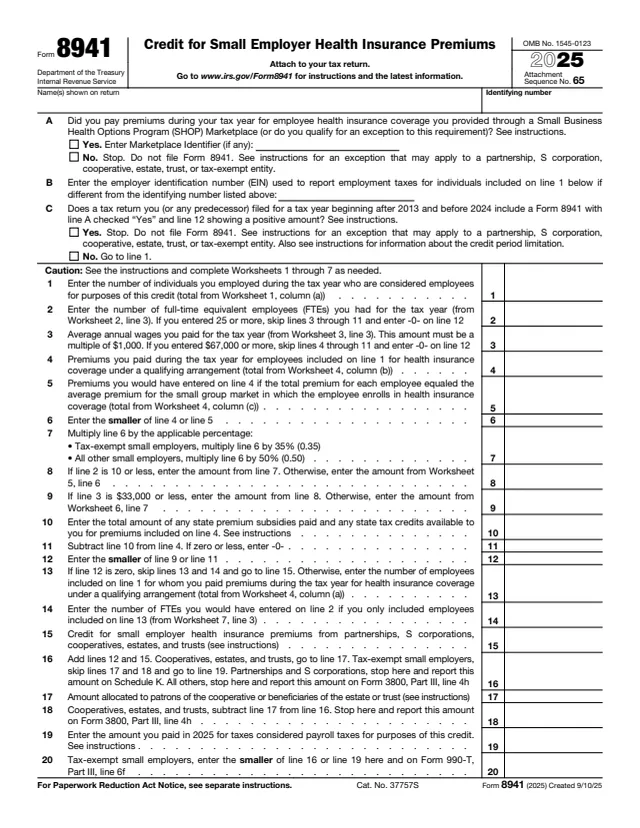
Form 8941, Credit for Small Employer Health Insurance Premiums, is the 2025 IRS form that eligible small employers use to figure the credit for small employer health insurance premiums. The instructions say that for tax years beginning after 2013 the credit is only available for a 2-consecutive-tax-year credit period, and that the maximum credit is generally a percentage of premiums the employer paid for certain coverage provided to certain employees enrolled in a qualified health plan offered through a Small Business Health Options Program (SHOP) Marketplace.
The form is attached to the employer's tax return. Lines A to C are screening questions, lines 1 to 14 figure the credit using Worksheets 1 through 7 in the instructions, and lines 15 to 20 cover credits passed through from other entities and the path for tax-exempt employers to Form 990-T.
You can fill out Form 8941 free in your browser on this page and download it without an account.
SHOP Marketplace premiums and the Marketplace Identifier, the EIN used for employment taxes if different, and whether an earlier return for a tax year beginning after 2013 and before 2024 claimed the credit.
The number of employees, FTEs and average annual wages from Worksheets 1 to 3. With 25 or more FTEs, or wages of $67,000 or more, the form skips to line 12 and enters -0-.
Premiums paid, premiums at the small group market average, the smaller of the two times 35% or 50%, then the FTE and wage limits from Worksheets 5 and 6.
State premium subsidies and state tax credits, the credit on line 12, and the number of enrolled employees and their FTEs.
Credits from partnerships, S corporations, cooperatives, estates and trusts, amounts allocated to patrons or beneficiaries, and payroll taxes for tax-exempt employers.
Line A asks about premiums paid for coverage through a SHOP Marketplace or an exception. The form says to stop and not file if line A is No or line C is Yes, apart from exceptions in the instructions for certain entities.
The form's caution points to Worksheets 1 through 7 in the instructions. Worksheets 1 to 3 feed lines 1 to 3, Worksheet 4 feeds lines 4, 5 and 13, and Worksheets 5 to 7 feed lines 8, 9 and 14.
Enter the number of employees, FTEs and average annual wages. The form says the line 3 amount must be a multiple of $1,000.
Enter premiums, apply 35% (tax-exempt small employers) or 50% (all others) on line 7, then the limits on lines 8 to 11. Line 12 is the smaller of line 9 or line 11.
Enter credits from Schedules K-1 or Form 1099-PATR on line 15. Line 16 says where the total goes: Schedule K for partnerships and S corporations, Form 3800, Part III, line 4h for most others.
Tax-exempt small employers enter certain payroll taxes paid in 2025 on line 19, and the smaller of line 16 or line 19 on line 20 and on Form 990-T, Part III, line 6f.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." Its attachment sequence number is 65.
The About page says that for tax years beginning after 2013, the credit is only available for a 2 consecutive tax year credit period.
The instructions say no more than one Form 8941 can be filed with a tax return, unless the exception in their Example 2 for spouses who each run a separate business applies.
The instructions say the credit for tax-exempt eligible small employers is limited to certain payroll taxes and is claimed as a refundable credit on Form 990-T.
The instructions say the deduction for the cost of employee health insurance coverage is reduced by the amount of any credit allowed for that coverage.

3800
1,921 fields, 9 pages
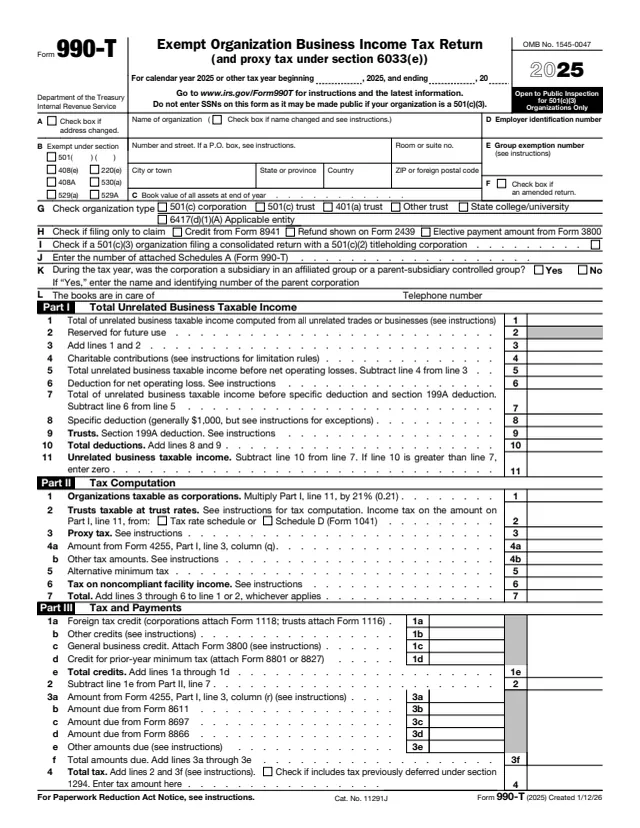
990-T
128 fields, 2 pages
990
1,075 fields, 12 pages

1065
111 fields, 1 page
1041
74 fields, 2 pages
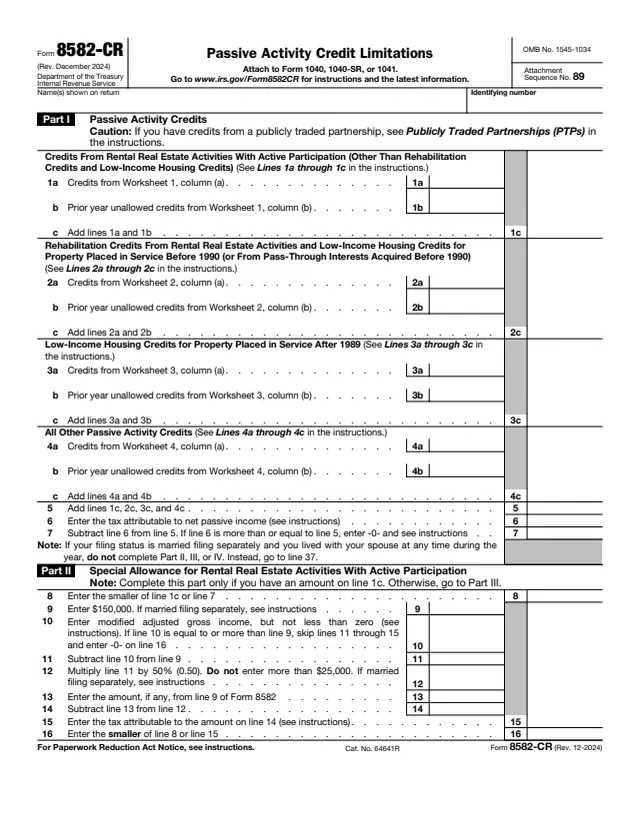
8582-CR
52 fields, 2 pages
Form 8941 figures a credit on health insurance premiums an employer paid for its employees. The instructions describe who completes it.
No tool matches that search.
The IRS About page says eligible small employers use it to figure the credit for small employer health insurance premiums.
The About page says that for tax years beginning after 2013 the credit is only available for a 2 consecutive tax year credit period.
The form says 35% for tax-exempt small employers and 50% for all other small employers.
The form says to skip lines 3 through 11 and enter -0- on line 12. The instructions add that an employer with exactly 25 FTEs is not, in fact, eligible because of how the phaseout works.
Not when the only source of the credit is a partnership, S corporation, cooperative, estate or trust. The instructions say to report it on Form 3800, Part III, line 4h instead.
Line 20 goes on Form 990-T, Part III, line 6f, the form says.