Header
The corporation's name and employer identification number, the 2025 tax year and the note to attach the form to the tax return.
8810
Corporate Passive Activity Loss and Credit Limitations
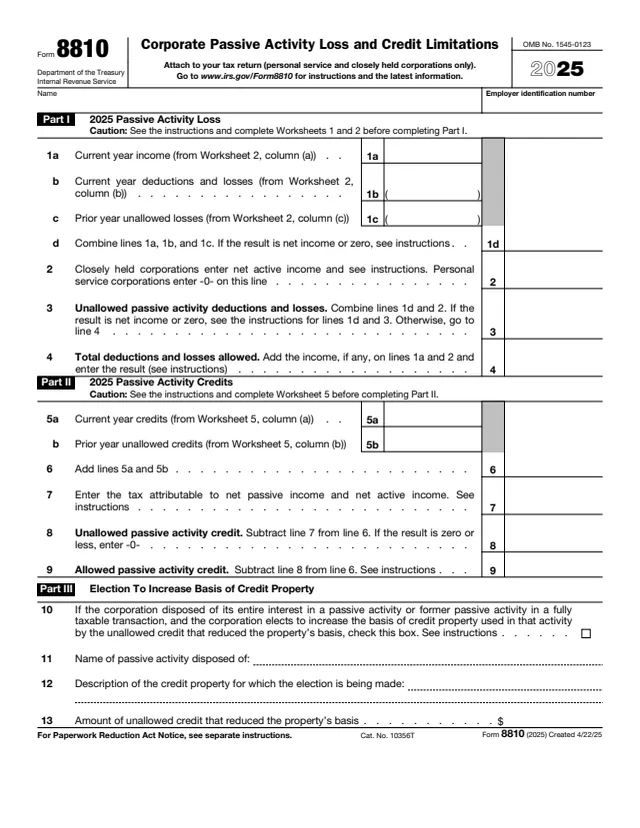
Form 8810, Corporate Passive Activity Loss and Credit Limitations, is a 2025 tax year form for corporations, not individuals. The instructions say personal service corporations and closely held corporations use it to figure the amount of any passive activity loss (PAL) or credit for the current tax year and the amount of losses and credits from passive activities allowed on the corporation's tax return. It is also used to make the election to increase the basis of credit property when the corporation disposes of its interest in an activity for which it has an unused credit.
The instructions say passive activities generally include trade or business activities in which the corporation did not materially participate for the tax year, and rental activities regardless of its participation. The form has three parts and relies on worksheets printed in the instructions. Individuals subject to the passive activity rules use Form 8582 instead.
The form says to attach it to the tax return. You can fill it out free in your browser on this page and download the result without an account.
The corporation's name and employer identification number, the 2025 tax year and the note to attach the form to the tax return.
Current year income, current year deductions and losses, and prior year unallowed losses, each taken from Worksheet 2, then combined on line 1d.
Net active income for closely held corporations (personal service corporations enter -0-), unallowed passive activity deductions and losses, and total deductions and losses allowed.
Current year and prior year unallowed credits from Worksheet 5, the tax attributable to net passive income and net active income, and the unallowed and allowed passive activity credit.
A box to elect to increase the basis of credit property, the name of the passive activity disposed of, a description of the property and the amount of unallowed credit that reduced its basis.
Worksheets 1 to 6 in the instructions figure income, losses, allocations and credits by activity. The form itself refers to Worksheets 1, 2 and 5.
The form says to see the instructions and complete Worksheets 1 and 2 before Part I. Worksheet 1 totals income, gains, deductions and losses for each passive activity.
Enter the totals of Worksheet 2, columns (a), (b) and (c), on lines 1a, 1b and 1c, then combine them on line 1d.
Closely held corporations enter net active income. Personal service corporations enter -0-. The instructions list the items left out when figuring net active income.
Combine lines 1d and 2 on line 3. The instructions say that if line 1d or 3 shows net income or zero, all the deductions and losses are allowed. Activities with an overall loss go through Worksheets 3 and 4.
Complete Form 3800 and Worksheet 5 first, then enter credits on lines 5a and 5b. Line 7 is the tax attributable to net passive and net active income, figured with the computation in the instructions. Line 9 is the allowed credit.
Check line 10 only if the corporation elects to increase the basis of credit property after a fully taxable disposition of its entire interest, then complete lines 11 to 13.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return (personal service and closely held corporations only)."
Allowed deductions are entered on the appropriate lines of Form 1120. Allowed passive activity general business credits go on line 3, 24 or 33 of Form 3800.
Column (c) of Worksheet 2 takes prior year unallowed losses from Worksheet 4 in the 2024 instructions. Worksheet 5, column (b), takes prior year unallowed credits from Worksheet 6 in the 2024 instructions.
The instructions say not to enter credits from publicly traded partnerships (PTPs) on Form 8810 or the worksheets. Special rules apply to PTP losses as well.
The instructions say the Part III election is irrevocable once made, and that no basis adjustment can be elected on a partial disposition or a disposition that is not fully taxable.
The form points to www.irs.gov/Form8810 for instructions and the latest information. The About page lists no recent developments.
8582
205 fields, 3 pages
6198
34 fields, 1 page

3800
1,921 fields, 9 pages

1120
481 fields, 6 pages
4797
182 fields, 2 pages
8949
202 fields, 2 pages
The instructions say personal service corporations and closely held corporations that have losses or credits (including prior year unallowed losses and credits) from passive activities file Form 8810.
No tool matches that search.
The instructions say personal service corporations and closely held corporations that have losses or credits, including prior year unallowed losses and credits, from passive activities.
No. The instructions say individuals subject to the passive activity rules use Form 8582, Passive Activity Loss Limitations.
No. The form says to attach it to the tax return of the personal service or closely held corporation.
The instructions say passive activities generally include trade or business activities in which the corporation did not materially participate for the tax year, and rental activities regardless of its participation.
Yes. The form says to complete Worksheets 1 and 2 before Part I and Worksheet 5 before Part II. The worksheets are in the instructions.
The instructions say once the election to increase the basis of credit property is made, it is irrevocable.