Header
Name as shown on Form 720, employer identification number, address and an optional telephone number.
720-X
Amended Quarterly Federal Excise Tax Return
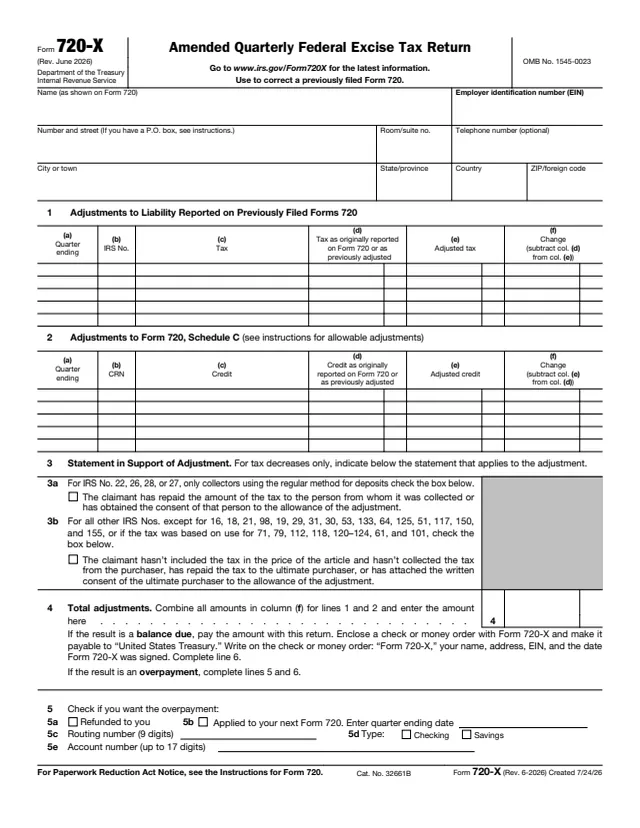
Form 720-X, Amended Quarterly Federal Excise Tax Return, is used to make adjustments to liability reported on Forms 720 filed for previous quarters. The form itself says "Use to correct a previously filed Form 720."
It is not used to change claims made on Schedule C (Form 720), except for the section 4051(d) tire credit and section 6426 credits. The instructions also say a remittance transfer provider (RTP) may use it to correct transcription or calculation errors on a previously filed Form 720, but not to claim amounts for a cancelled or expired remittance transfer.
The result of the adjustments is either a balance due, paid with the return, or an overpayment that is refunded or applied to the next Form 720. This page covers the Rev. June 2026 form. You can fill out the PDF free in your browser on this page and download it without an account.
Name as shown on Form 720, employer identification number, address and an optional telephone number.
Columns for quarter ending, IRS No., tax, tax as originally reported or previously adjusted, adjusted tax, and the change.
Columns for quarter ending, credit reference number (CRN), credit, credit as originally reported, adjusted credit, and the change.
Two checkbox statements used for tax decreases only: 3a for certain communications and air transportation taxes, and 3b for other IRS Nos. except those the form lists.
Line 4 totals the changes. A balance due is paid with the return. An overpayment is refunded or applied to the next Form 720, with direct deposit lines 5c to 5e.
Space to explain the adjustments, followed by the signature, title and the paid preparer section on page 2.
Report each adjustment separately. Enter the quarter ending date of the Form 720 being amended in MMDDYYYY format. The instructions give 03312026 for the first quarter of 2026.
Enter the tax as originally reported or as later adjusted, then the adjusted tax. If (e) is greater, the change is an increase. If (d) is greater, it is a decrease, shown in parentheses.
Use it for tire credit adjustments with CRN 366. The instructions say section 6426 credits for biodiesel, renewable diesel, alternative fuel and mixtures expired after 2024, and the SAF credit after September 30, 2025.
For a tax decrease, check the statement that applies: 3a for regular method collectors of IRS Nos. 22, 26, 28 or 27, or 3b for other IRS Nos. not excluded on the form.
Combine column (f) amounts on line 4. For a balance due, enclose a check or money order payable to "United States Treasury" with "Form 720-X", name, address, EIN and date signed written on it. For an overpayment, check 5a to refund or 5b to apply it.
Give a detailed description and computation of each adjustment, on line 6 or attached sheets with name and EIN. The instructions say Form 720-X is signed even when filed with Form 720 to apply an overpayment.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Filed separately, the instructions list Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0009. Otherwise it is attached to the next Form 720.
The instructions say adjustments that decrease tax liability for a prior quarter are generally made within 3 years from the time the return was filed or 2 years from the time the tax was paid, whichever is later.
If box 5b is checked, the overpayment is also included on lines 6 and 7 of the next Form 720. The instructions say it is first applied to any other federal tax, interest or penalty owed.
Lines 5c to 5e were added for direct deposit of overpayments, but the instructions say the functionality is not yet available. See IRS.gov/Form720X for updates.
The instructions say an overpayment from line 4 is included in gross income if a deduction on the income tax return included those taxes and reduced the income tax liability.
Designated private delivery services can be used for the timely mailing rule, but the instructions say they cannot deliver to P.O. boxes.
720
715 fields, 8 pages
8849
27 fields, 4 pages
8849 Sch. 6
26 fields, 1 page
W-12
85 fields, 3 pages
720-TO
266 fields, 3 pages
720-CS
288 fields, 3 pages
Form 720-X is filed by the business that filed the original Form 720. The instructions say it is signed by a person authorized by the entity.
No tool matches that search.
To make adjustments to liability reported on Forms 720 filed for previous quarters. The instructions say adjustments are not entered on Form 720 itself.
Only for the section 4051(d) tire credit and section 6426 credits. Other changes to claims made on Schedule C (Form 720) are not made on Form 720-X.
When filed separately, to Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0009. It can also be attached to the next Form 720.
The instructions say generally within 3 years from the time the return was filed or 2 years from the time the tax was paid, whichever is later.
No. The instructions say the sender may file a claim for refund on Form 8849, Schedule 6. An RTP may use Form 720-X only to correct transcription or calculation errors.
The form has direct deposit lines 5c to 5e, but the instructions say the functionality is not yet available and point to IRS.gov/Form720X for updates.