Header and notes
The decedent's name and Social Security number, a note that generally no exclusion is allowed for estates of decedents dying after December 31, 1984, and a note on portability-only returns.
706 Sch. I
Annuities
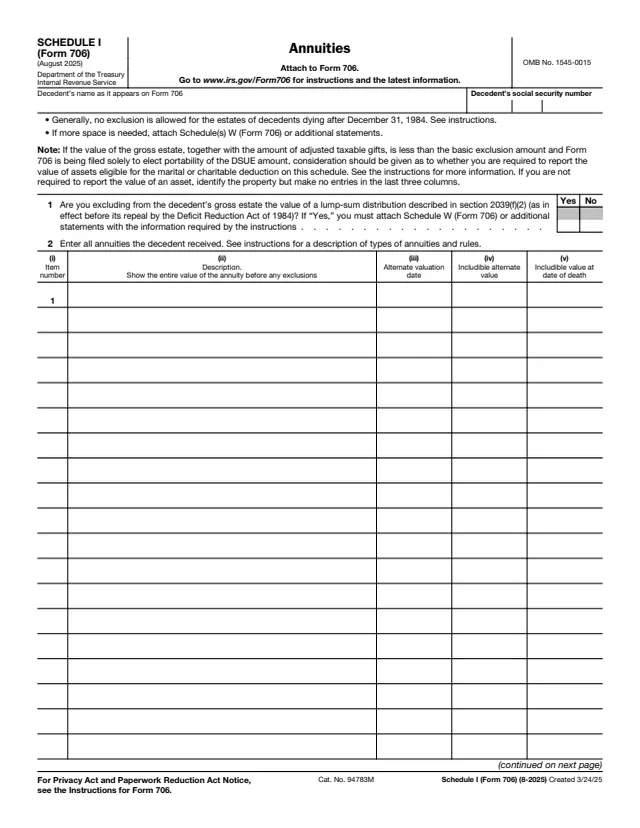
Schedule I (Form 706), Annuities, is a schedule of Form 706, the United States Estate (and Generation-Skipping Transfer) Tax Return. The IRS says that if the decedent, immediately before death, received any type of annuity, this schedule is used to report the annuities. The form says "Attach to Form 706."
The instructions say the rules apply to all types of annuities, including pension plans, individual retirement arrangements (IRAs), purchased commercial annuities and private annuities. The schedule is completed and filed with the return if the answer to Form 706, Part IV, line 16 is "Yes." Its total goes on Form 706, Part V, item 9.
You can fill out Schedule I free in your browser on this page and download it without an account.
The decedent's name and Social Security number, a note that generally no exclusion is allowed for estates of decedents dying after December 31, 1984, and a note on portability-only returns.
A Yes or No question on excluding a lump-sum distribution described in section 2039(f)(2), as in effect before its repeal. A Yes needs Schedule W or added statements.
Columns for the item number, a description showing the entire value before exclusions, the alternate valuation date, the includible alternate value and the includible value at date of death.
The line 2 table continues on page 2 with the same five columns.
The total of column (iv) or (v), the total from attached Schedule(s) W or statements, and the combined total entered on Form 706, Part V, item 9.
Answer Yes or No. The instructions say the lump-sum rules are repealed and apply only in limited pre-1985 cases. A Yes needs the names, addresses and identifying numbers of the recipients attached.
The instructions say to give the name and address of the grantor of the annuity and to say if it is under an approved plan. For a term of years, include the term and the date it began.
Under an approved plan, state the ratio of the decedent's contribution to the total purchase price. If the annuity is wholly or partly excluded, enter the amount excluded in column (ii) and explain how it was figured.
Enter the value at the date of death in column (v). The instructions say not to enter alternate values unless alternate valuation was elected on Form 706, Part III, line 1.
Add column (iv) or (v), add the total from any attached Schedule(s) W, and enter the result on Form 706, Part V, item 9.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach Schedule I to Form 706. The line 5 total is entered on Form 706, Part V, item 9.
The instructions give Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999. The About page points to Filing estate and gift tax returns for the latest filing address.
The instructions say Form 706 is filed within 9 months after the date of the decedent's death. Form 4768 is used to apply for an automatic 6-month extension of time to file.
The form says that if more space is needed, attach Schedule(s) W (Form 706) or additional statements.
The form says that when Form 706 is filed solely to elect portability, some assets eligible for the marital or charitable deduction may be identified with no entries in the last three columns.

706
316 fields, 5 pages
706 Sch. W
303 fields, 2 pages
706 Sch. M
157 fields, 2 pages
706 Sch. R-1
121 fields, 3 pages
706 Sch. G
268 fields, 2 pages
4768
35 fields, 1 page
The executor of a decedent's estate completes Schedule I as part of Form 706. It is not a form an individual files for their own taxes.
No tool matches that search.
The instructions say an annuity consists of one or more payments extending over any period of time. The payments may be equal or unequal, conditional or unconditional, periodic or sporadic.
The instructions say Social Security benefits are not includible in the gross estate even if the surviving spouse receives benefits.
The instructions say to include only the part of the annuity's value that the decedent's contribution bears to the total purchase price. Their example: 75% of a $20,000 survivor's annuity is $15,000.
The form says generally no exclusion is allowed for the estates of decedents dying after December 31, 1984. The instructions say the repealed exclusion rules apply only in limited cases tied to 1984 and earlier.
The form says to add lines 3 and 4 and enter the amounts on Form 706, Part V, item 9.