Part I: General Information
Name of the skip person distributee, SSN of an individual or TIN of a trust distributee, name and title of the person filing if different, and a U.S. or foreign address.
706-GS
Generation-Skipping Transfer Tax Return For Distributions
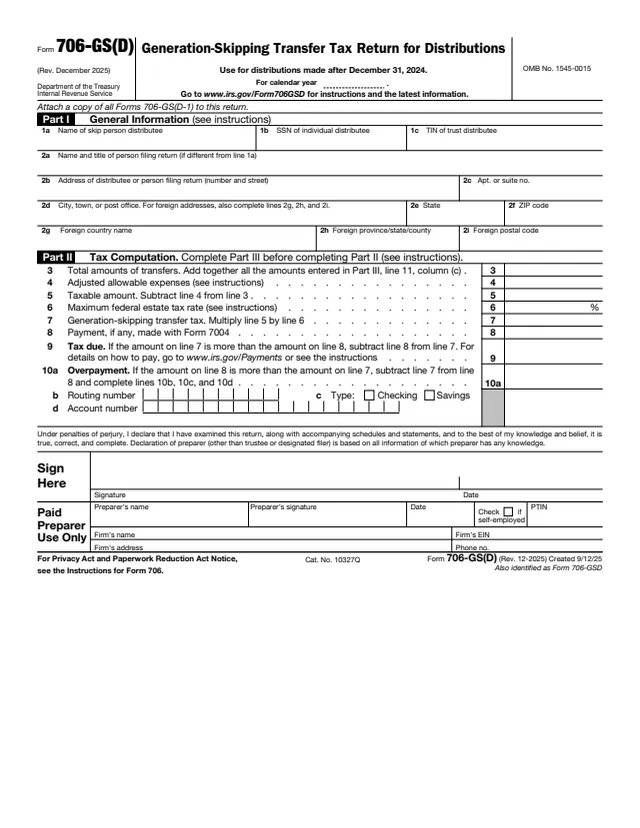
Form 706-GS(D) is used by a skip person distributee to calculate and report the tax due on distributions from a trust that are subject to the generation-skipping transfer (GST) tax. The form says to use it for distributions made after December 31, 2024, and the instructions say the GST tax on distributions is figured and reported on a calendar year basis.
The filer is the person who received the distribution, called the skip person distributee, which can be an individual or a trust. The trustee reports each taxable distribution to the distributee on Form 706-GS(D-1), and the form says to attach a copy of all Forms 706-GS(D-1) to this return. For a trust, a minor or a distributee under a disability, the instructions name a trustee, parent or guardian on line 2a.
This page hosts the December 2025 revision. You can fill out the PDF free in your browser on this page and download it without an account.
Name of the skip person distributee, SSN of an individual or TIN of a trust distributee, name and title of the person filing if different, and a U.S. or foreign address.
Total transfers from Part III, adjusted allowable expenses, the taxable amount, the maximum federal estate tax rate and the generation-skipping transfer tax.
Any payment made with Form 7004, the tax due, and an overpayment line with routing number, checking or savings, and account number for direct deposit.
A declaration under penalties of perjury, the filer's signature and date, and the Paid Preparer Use Only area with PTIN, firm name, firm EIN and phone number.
Line 11 lists each distribution by trust TIN, item number and amount of transfer, taken from Form 706-GS(D-1). The form says the page can be duplicated if more entries are needed.
The form says to complete Part III before Part II. List each taxable distribution with an inclusion ratio greater than zero, using the trust TIN, item number and tentative transfer from Form 706-GS(D-1).
The tentative transfer is the inclusion ratio times the fair market value of the distribution on the date of distribution. If the trustee left the values blank or the distributee disagrees, the instructions say to attach a statement with the amounts and how they were figured.
Enter the distributee's name and either the SSN for an individual or the TIN for a trust, never both. Use line 2a for a trustee, parent or guardian, and lines 2b to 2i for the address for IRS correspondence.
Add the Part III amounts on line 3. Line 4 holds adjusted allowable expenses, such as preparing this return, multiplied by the inclusion ratio. Subtract line 4 from line 3 for the taxable amount on line 5.
Enter the maximum tax rate in effect when the distribution occurred, from the table in the instructions. The table shows 40% for transfers after December 31, 2012. Multiply line 5 by line 6 for the GST tax.
Enter any payment made with Form 7004, then the tax due or the overpayment with direct deposit details. Sign and date, and attach a copy of every Form 706-GS(D-1).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the return is generally filed on or after January 1 but not later than April 15 of the year following the calendar year when the distributions were made.
Form 7004 requests an automatic 6-month extension of time to file. The instructions say it is filed on or before the regular due date of Form 706-GS(D).
Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999. With a private delivery service, Internal Revenue Submission Processing Center, 333 W. Pershing, Kansas City, MO 64108.
The instructions list EFTPS, same-day wire, a check payable to "United States Treasury" with the SSN or TIN and "Form 706-GS(D)" written on it, and cash at participating retail stores.
To change a filed return, file another Form 706-GS(D) marked "Supplemental Information" with a statement of the changes and a copy of the original, at Internal Revenue Service Center, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915.
The instructions describe section 6651 penalties for late filing and late payment unless there is reasonable cause, a 20% section 6662 penalty for certain underpayments, and interest on tax not paid by the due date.
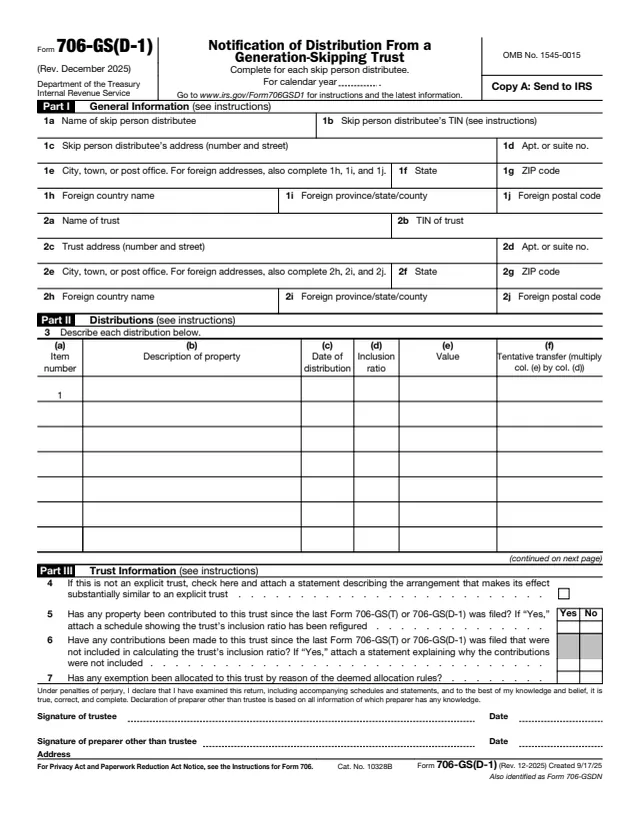
706-GS
386 fields, 5 pages
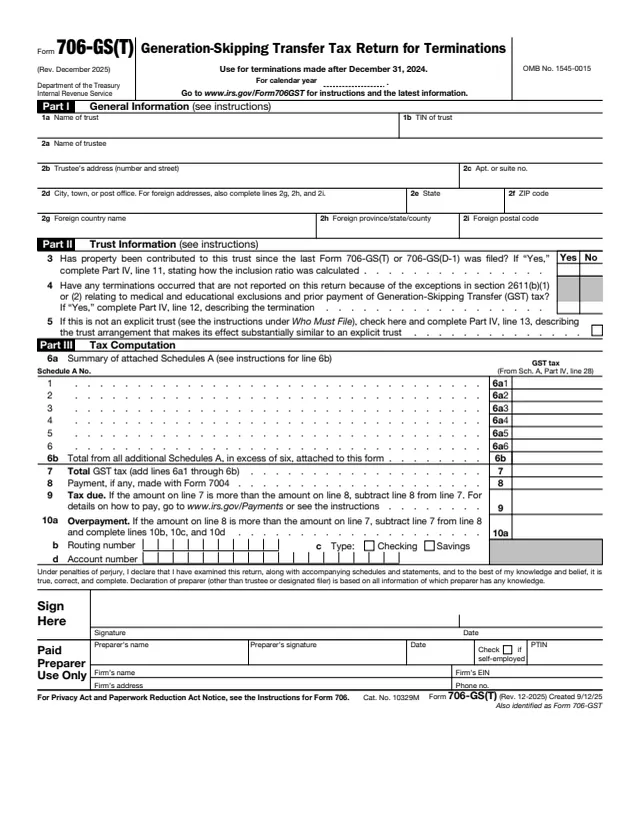
706-GS
287 fields, 6 pages

706
316 fields, 5 pages

7004
26 fields, 1 page
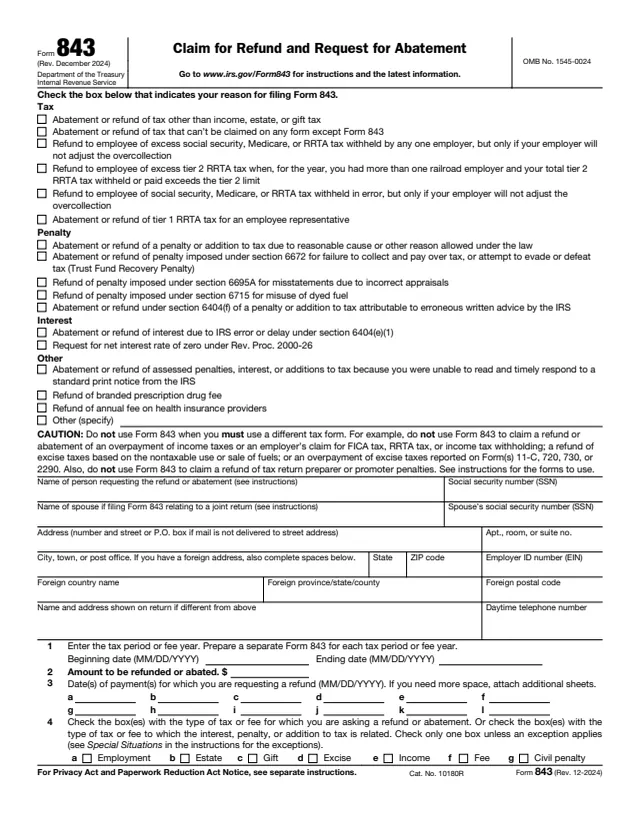
843
85 fields, 2 pages
The instructions say "any skip person who receives a taxable distribution from a trust must file Form 706-GS(D)." Either the distributee or an authorized representative signs it.
No tool matches that search.
The trustee. The instructions say trustees report taxable distributions to skip person distributees on Form 706-GS(D-1), and the distributee attaches a copy of each one to Form 706-GS(D).
The instructions say a distributee whose Form 706-GS(D-1) shows an inclusion ratio of zero for all distributions does not need to file Form 706-GS(D).
The maximum federal estate tax rate in effect when the distribution occurred. The table in the instructions shows 40% for transfers after December 31, 2012.
Line 4 allows adjusted allowable expenses, such as preparing this return, multiplied by the inclusion ratio. The instructions say an expense incurred after filing is claimed on Form 843, Claim for Refund and Request for Abatement.
No. The instructions say the GST tax on distributions is figured and reported on a calendar year basis, regardless of the income tax accounting period.
Yes. The instructions say direct deposit fields were added on lines 10b, 10c and 10d, and that a refund under $1 is sent only on written request.