Header
Name and identifying number of the person filing Form 5471, and the foreign corporation's name, EIN if any and reference ID number.
5471 Sch. G-1
Cost Sharing Arrangement
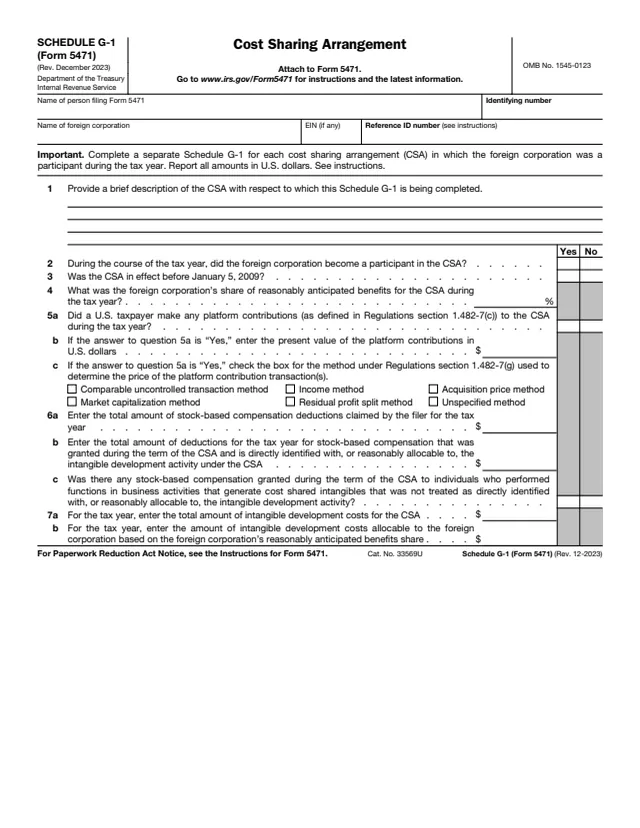
Schedule G-1 (Form 5471), Cost Sharing Arrangement, is a separate schedule filed with Form 5471. The form says to complete a separate Schedule G-1 for each cost sharing arrangement (CSA) in which the foreign corporation was a participant during the tax year, and to report all amounts in U.S. dollars.
The schedule asks for a short description of the CSA, whether the foreign corporation joined it during the year, whether the CSA was in effect before January 5, 2009, the corporation's share of reasonably anticipated benefits, platform contributions made by a U.S. taxpayer, stock-based compensation and intangible development costs.
The About Form 5471 page says certain U.S. citizens and residents who are officers, directors or shareholders in certain foreign corporations file Form 5471 and its schedules. This page covers the December 2023 revision. You can fill out the PDF free in your browser on this page and download it without an account.
Name and identifying number of the person filing Form 5471, and the foreign corporation's name, EIN if any and reference ID number.
A brief description of the CSA, yes or no questions on joining it during the year and on whether it was in effect before January 5, 2009, and the corporation's share of reasonably anticipated benefits as a percentage.
Whether a U.S. taxpayer made platform contributions to the CSA during the year, their present value in U.S. dollars, and boxes for the pricing method under Regulations section 1.482-7(g).
Total stock-based compensation deductions claimed by the filer, deductions tied to the intangible development activity under the CSA, and a yes or no question on compensation not treated as tied to it.
Total intangible development costs for the CSA for the tax year, and the amount allocable to the foreign corporation based on its reasonably anticipated benefits share.
Enter the filer's name and identifying number, then the foreign corporation's name and EIN if any. The instructions say to use the reference ID number shown on Form 5471, page 1, item 1b(2), if applicable.
Describe the CSA the schedule covers, then answer whether the foreign corporation became a participant during the year and whether the CSA was in effect before January 5, 2009.
Enter the foreign corporation's share of reasonably anticipated benefits (RAB). The instructions say that if more than one RAB share was applied during the year, enter the share applied to intangible development costs incurred at the end of the year.
If 5a is Yes, complete 5b and 5c. The instructions say 5b is the corporation's RAB share of the total present value of all platform contributions made by the U.S. taxpayer that year, and to attach a brief statement if a present value estimate is not possible.
Enter the stock-based compensation amounts and answer 6c. The instructions say a taxpayer who made the election in Regulations section 1.482-7(d)(3)(iii)(B) or Notice 2005-99 attaches a statement and includes the total taken into account as a cost on line 6b.
Enter the total intangible development costs for the CSA on 7a, and on 7b the amount allocated to the foreign corporation based on its RAB share.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 5471. The instructions say Form 5471 is attached to the filer's income tax return, or partnership or exempt organization return, and both are filed by the due date, including extensions, for that return.
The form says to report all amounts in U.S. dollars.
The instructions say that when a schedule is required but all amounts are zero, the schedule should still be filed with one or more zero amounts.
The Form 5471 instructions list a $10,000 penalty for each annual accounting period of each foreign corporation for failure to furnish the information required by section 6038(a) within the time prescribed.
The form says to go to www.irs.gov/Form5471 for instructions. Schedule G-1 has its own section in the Instructions for Form 5471.

5471
437 fields, 6 pages
5471 Sch. M
178 fields, 2 pages
5471 Sch. H
41 fields, 1 page
5471 Sch. H-1
55 fields, 1 page
5471 Sch. I-1
35 fields, 1 page
8886
98 fields, 2 pages
The person filing Form 5471 completes it and attaches it to that form. The instructions say the name of the person filing Form 5471 is generally the name of the U.S. person described in the applicable category of filers.
No tool matches that search.
The person filing Form 5471 attaches it. The About Form 5471 page says certain U.S. citizens and residents who are officers, directors or shareholders in certain foreign corporations file Form 5471 and its schedules.
No. The form says to complete a separate Schedule G-1 for each CSA in which the foreign corporation was a participant during the tax year.
The form says to report all amounts in U.S. dollars.
The form refers to the definition in Regulations section 1.482-7(c). Line 5c lists the pricing methods under Regulations section 1.482-7(g), including the income method and the residual profit split method.
The instructions say to use the reference ID number shown on Form 5471, page 1, item 1b(2), if applicable.
They are a section of the Instructions for Form 5471. The form points to www.irs.gov/Form5471.