Header
The depositor's name, date of birth and address, the account number, a box to check if this is an amendment, and the custodian's name and address. A line records the amount the depositor assigned to the account.
5305-R
Roth Individual Retirement Trust Account
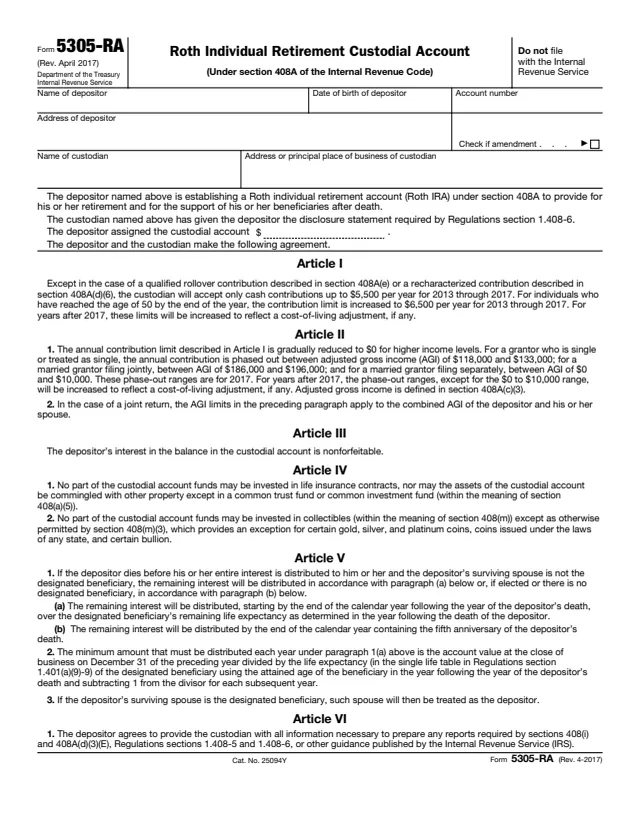
Form 5305-RA is a model custodial account agreement that, in the words of its instructions, meets the requirements of section 408A of the Internal Revenue Code. The instructions say a Roth individual retirement account (Roth IRA) is established after the form is fully executed by both the individual, called the depositor, and the custodian. The account has to be created in the United States for the exclusive benefit of the depositor and his or her beneficiaries.
Only Articles I through VIII have been reviewed by the IRS. Article IX is open space for additional provisions the depositor and the custodian agree to. The instructions note that, unlike contributions to traditional individual retirement arrangements, contributions to a Roth IRA are not deductible from the depositor's gross income.
The form is not filed with the IRS. It says "Do not file Form 5305-RA with the IRS. Instead, keep it with your records." This is the April 2017 revision, so its contribution limits are for 2013 through 2017 and its income phase-out ranges are for 2017. You can fill it out free in your browser on this page and download the result without an account.
The depositor's name, date of birth and address, the account number, a box to check if this is an amendment, and the custodian's name and address. A line records the amount the depositor assigned to the account.
Apart from a qualified rollover contribution under section 408A(e) or a recharacterized contribution, the custodian accepts only cash contributions up to the yearly limit the form prints.
The annual contribution limit is gradually reduced to $0 for higher adjusted gross income (AGI). For a joint return, the limits apply to the combined AGI of the depositor and spouse.
Article III says the depositor's interest is nonforfeitable. Article IV bars investing in life insurance contracts and in collectibles, except certain gold, silver and platinum coins, coins issued under state law and certain bullion.
Rules for paying the remaining interest over the designated beneficiary's life expectancy or by the end of the year containing the fifth anniversary of the depositor's death, and for a surviving spouse.
Reports, controlling provisions and amendments, then Article IX for additional provisions and signature lines for the depositor, the custodian and, only if a signature has to be witnessed, a witness.
Enter the depositor's name, date of birth and address, and the account number at the top of page 1.
Enter the custodian's name and address or principal place of business. Check the box marked "Check if amendment" only when this form amends an existing agreement.
Enter the dollar amount on the line that reads "The depositor assigned the custodial account $" in the opening paragraph.
The instructions say elections made under Article V should be reviewed periodically to make sure they correspond to the depositor's intent.
Add any agreed provisions, such as definitions, investment powers, voting rights, the custodian's fees or state law requirements, and attach pages if needed. If none, draw a line through the space.
The depositor and the custodian sign and date page 2. The form says to use the witness line only if a signature is required to be witnessed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Nowhere. The form says "Do not file Form 5305-RA with the IRS. Instead, keep it with your records."
Article I lists $5,500 per year for 2013 through 2017, or $6,500 for individuals who reached age 50 by the end of the year. The form says later years are adjusted for cost of living, if any.
Article II prints AGI ranges of $118,000 to $133,000 for a filer who is single or treated as single, $186,000 to $196,000 for married filing jointly, and $0 to $10,000 for married filing separately.
The instructions say the depositor may be subject to a 6% tax on excess contributions, for example when the depositor's AGI exceeds the Article II limits for the tax year.
The instructions say distributions after 5 years made when the depositor is 59½ or older, or on account of death, disability, or a first-time home purchase (limited to $10,000), are not includible in gross income.
Provisions added in Article IX have to comply with state law and the Internal Revenue Code, and the form says they may not imply that the IRS reviewed or pre-approved them.
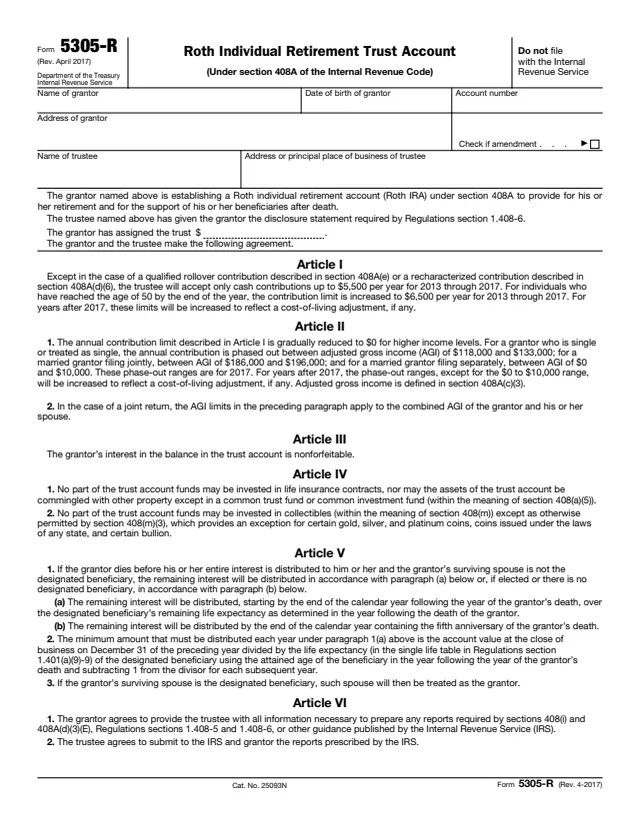
5305-R
9 fields, 2 pages
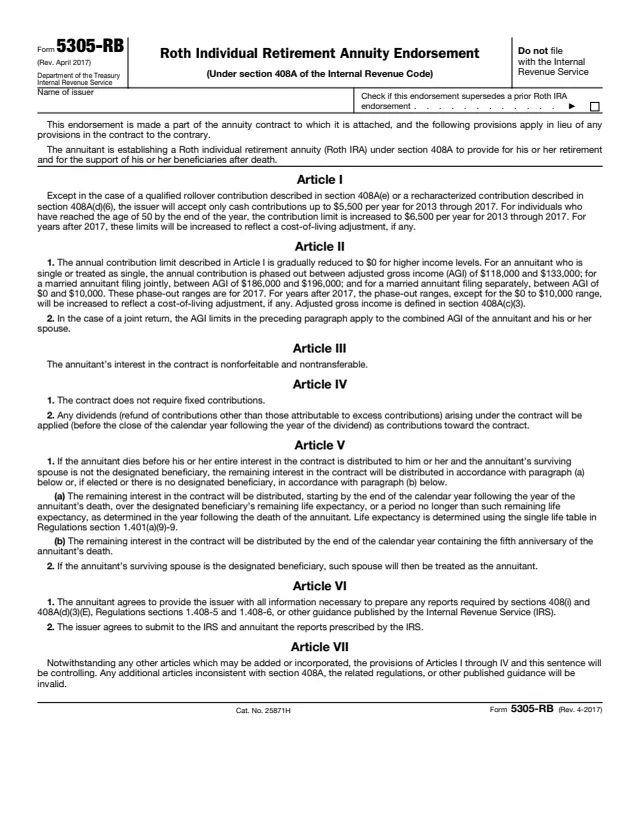
5305-RB
3 fields, 2 pages
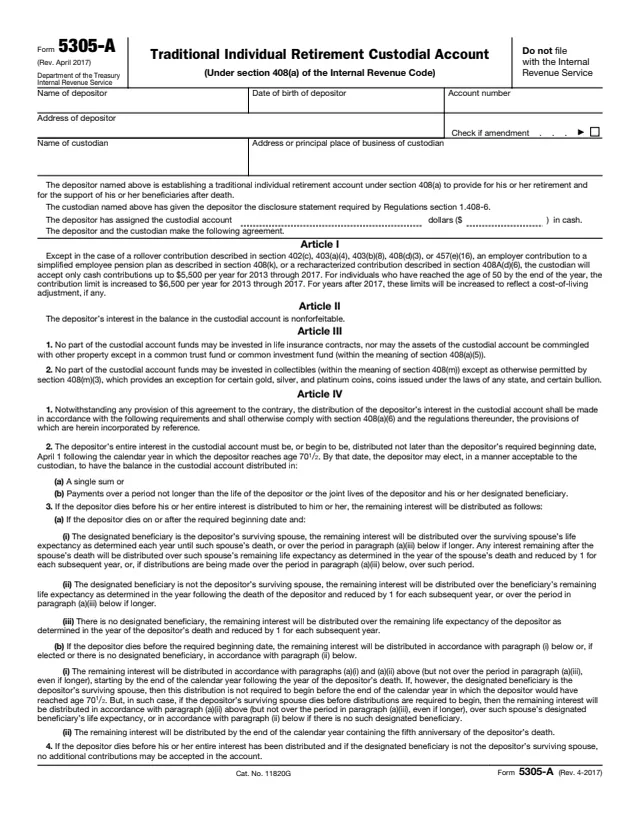
5305-A
10 fields, 2 pages
5305
10 fields, 2 pages
5305-S
9 fields, 2 pages
The form is an agreement between the person opening the Roth IRA and the custodian that holds it. Nobody sends it to the IRS.
No tool matches that search.
No. The form says "Do not file Form 5305-RA with the IRS. Instead, keep it with your records."
The depositor, who establishes the custodial account, and the custodian. The instructions say the Roth IRA is established once both have fully executed the form.
The instructions say only Articles I through VIII have been reviewed by the IRS. Article IX holds any additional provisions.
The April 2017 revision lists $5,500 per year for 2013 through 2017, or $6,500 for individuals who reached age 50 by the end of the year, with cost-of-living adjustments, if any, for later years.
The instructions say that, unlike contributions to traditional individual retirement arrangements, contributions to a Roth IRA are not deductible from the depositor's gross income.
Article V says a surviving spouse who is the designated beneficiary is treated as the depositor. Otherwise the interest is paid over the beneficiary's life expectancy or by the end of the year containing the fifth anniversary of the death.