Part I: General Information
Lines 1 to 9 cover your foreign address, occupation, employer and employer type, earlier Form 2555 filings and revocations, citizenship, a second foreign household, and your tax homes.
2555
Foreign Earned Income
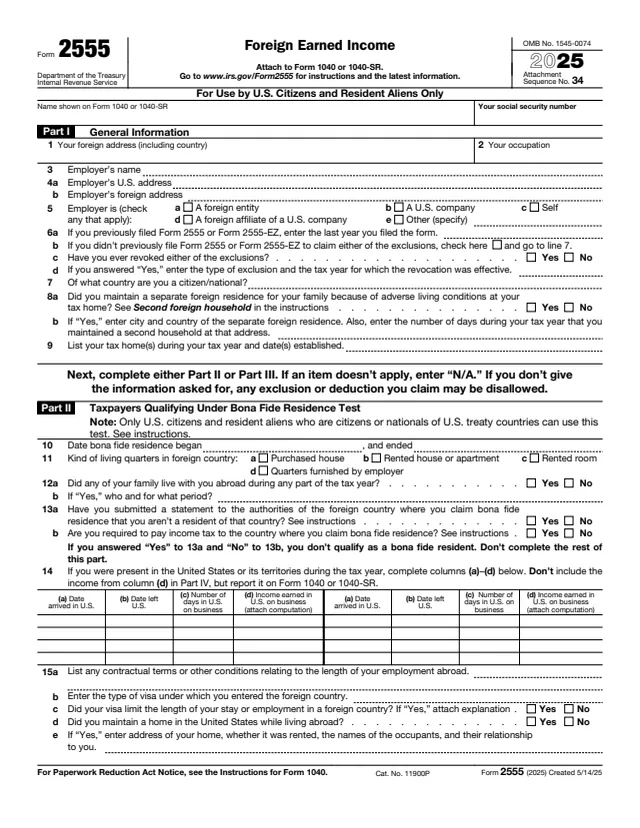
Form 2555 is used to figure the foreign earned income exclusion and the housing exclusion or deduction, the IRS About Form 2555 page says. It also says you cannot exclude or deduct more than your foreign earned income for the year. The form is printed "For Use by U.S. Citizens and Resident Aliens Only" and says "Attach to Form 1040 or 1040-SR."
The instructions describe a tax home test and two time tests: the bona fide residence test and the physical presence test. The form has nine parts. Part I asks for general information, Part II or Part III covers one of the two tests, Part IV totals foreign earned income, and Parts V to IX figure the housing exclusion, the foreign earned income exclusion and the housing deduction. For 2025, line 37 shows a maximum exclusion of $130,000.
You can fill out Form 2555 free in your browser on this page and download it without an account.
Lines 1 to 9 cover your foreign address, occupation, employer and employer type, earlier Form 2555 filings and revocations, citizenship, a second foreign household, and your tax homes.
Part II, lines 10 to 15, is the bona fide residence test. Part III, lines 16 to 18, is the physical presence test with a 12-month period and a travel table. The instructions say to complete one, not both.
Lines 19 to 26 total wages, business income, noncash income such as a home, meals or a car, allowances and other foreign earned income, less excludable meals and lodging.
Part V asks if you are claiming the housing exclusion or deduction. Part VI, lines 28 to 36, figures it from qualified housing expenses, the location limit and employer-provided amounts.
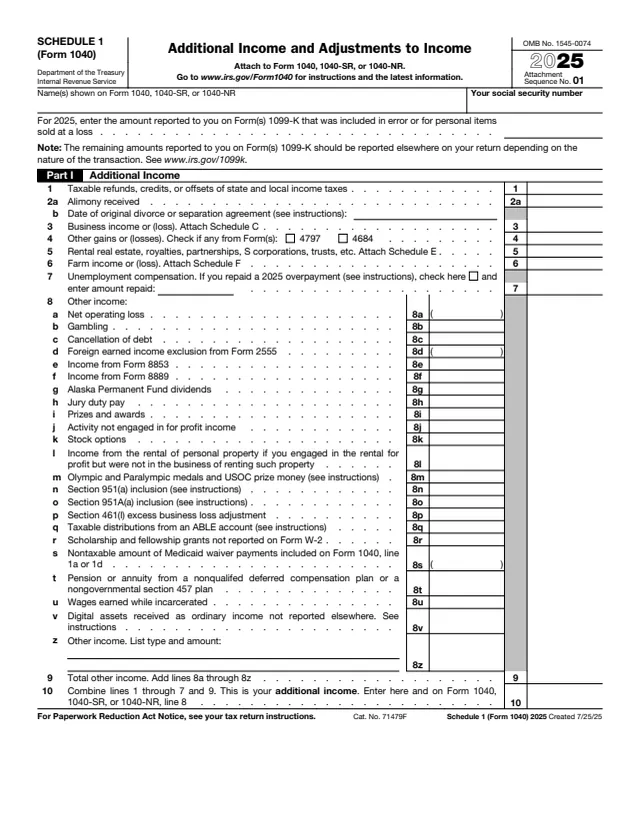
Part VII, lines 37 to 42, figures the foreign earned income exclusion. Part VIII, lines 43 to 45, combines both exclusions, subtracts allocable deductions and goes to Schedule 1 (Form 1040), line 8d.
Lines 46 to 50 figure the housing deduction, including any carryover from 2024, and go to Schedule 1 (Form 1040), line 24j.
Enter your entire foreign address with country, then your tax homes and the dates they were established on line 9. The form says to enter "N/A" for an item that does not apply.
For Part II, line 10 takes the dates residence began and ended, or "Continues." For Part III, line 16 takes a 12-month period with both dates, and line 18 lists travel with arrival and departure dates.
Enter income earned and received for services performed in a foreign country, in U.S. dollars at the exchange rate when received. The instructions say pensions, interest, dividends and U.S. Government pay are not foreign earned income.
Line 28 holds reasonable housing expenses such as rent and utilities. The instructions say most locations have a $39,000 limit on line 29b for a full year, and line 32 multiplies $56.99 by the days on line 31.
Enter $130,000 on line 37, the qualifying days on line 38 and the fraction of the year on line 39. Line 42 is the smaller of line 40 or line 41.
Line 44 holds deductions allocable to the excluded income, with a computation attached. Line 45 goes on Schedule 1 (Form 1040), line 8d, and the form points to the Foreign Earned Income Tax Worksheet in the Form 1040 instructions.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 2555 to Form 1040 or 1040-SR and mail the return to one of the special addresses for those filing Form 2555, not the state of residence address.
The instructions say a 2025 calendar year Form 1040 or 1040-SR is generally due April 15, 2026, with an automatic 2-month extension to June 15, 2026, when you live and have your tax home outside the United States and Puerto Rico.
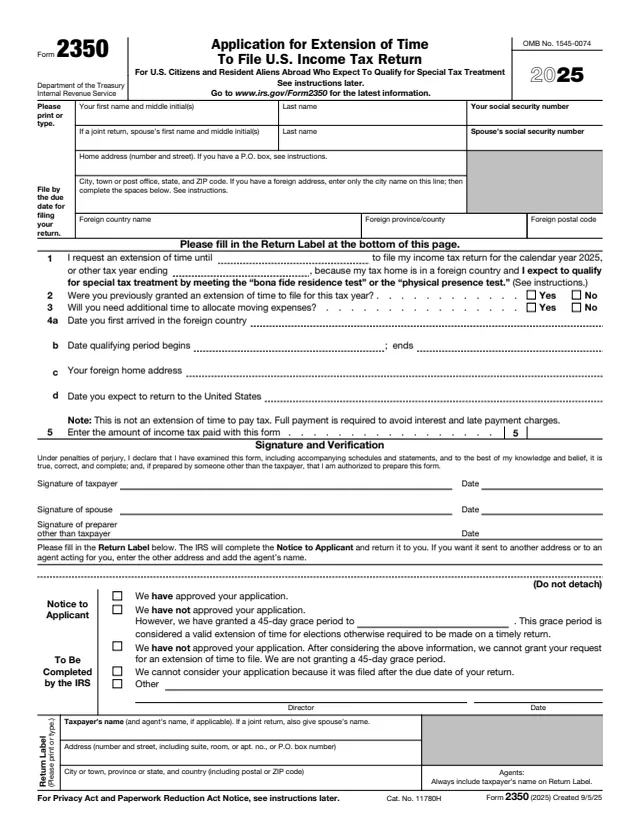
If a test is not yet met by the due date, the instructions mention Form 2350, filed with the Department of the Treasury, Internal Revenue Service Center, Austin, TX 73301-0045, before the due date.
The instructions say a choice to claim the exclusions stays in effect until revoked by a statement attached to the return, and after a revocation they can't be claimed for the next 5 tax years without IRS approval.
The instructions say the additional child tax credit and the earned income credit can't be taken when either exclusion or the housing deduction is claimed, and there is no foreign tax credit on excluded income.
When adverse conditions forced someone to leave a listed country, the instructions say to attach a statement and enter "Claiming Waiver" in the top margin on page 1.

1040
199 fields, 2 pages
1040
73 fields, 2 pages
2350
26 fields, 4 pages
673
28 fields, 2 pages
1116
118 fields, 2 pages
1040-X
166 fields, 2 pages
An individual completes Form 2555 and attaches it to their own Form 1040 or 1040-SR. The instructions describe the tests that decide who qualifies.
No tool matches that search.
The About page says it is used to figure the foreign earned income exclusion and the housing exclusion or deduction.
Line 37 of the 2025 form says to enter $130,000. Line 40 then multiplies it by the share of the tax year in the qualifying period from line 39.
The instructions say it requires being physically present in a foreign country or countries for at least 330 full days during any period of 12 months in a row.
No. The instructions say to complete either Part II or Part III, but not both.
The instructions say that if both spouses qualify and claim the exclusion, each figures it separately and completes Part VII of a separate Form 2555.
Yes. The instructions say to mail the Form 1040 or 1040-SR with Form 2555 attached to the special addresses for those filing Form 2555.