Employee information
First name and initial, last name and Social Security number.
673
Statement for Claiming Exemption From Withtholding on Foreign Earned Income Eligible for the Exclusion(s) Provided by Section 911
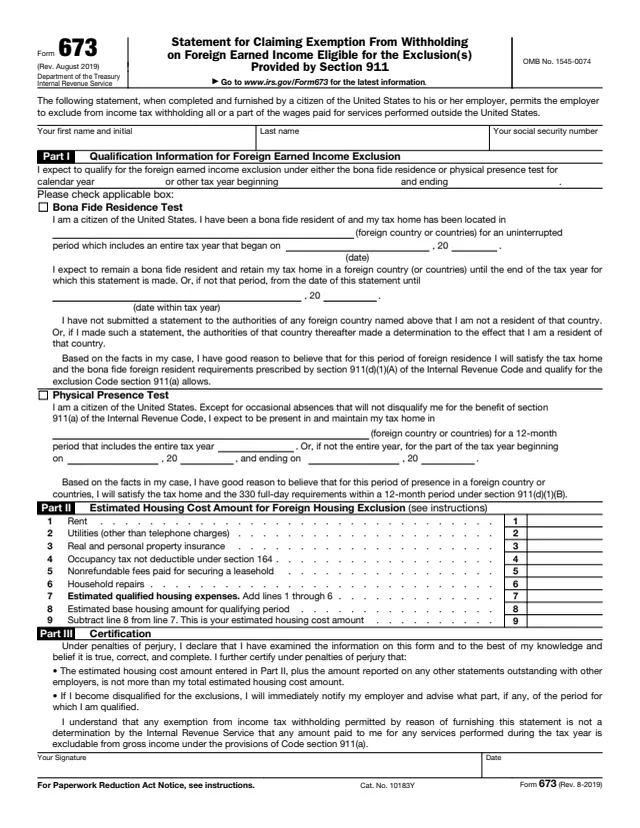
Form 673 is a statement a U.S. citizen gives to a U.S. employer to claim an exemption from U.S. income tax withholding on wages earned abroad, to the extent of the foreign earned income exclusion and the foreign housing exclusion under section 911. The form says that, when completed and furnished by a citizen of the United States to his or her employer, it "permits the employer to exclude from income tax withholding all or a part of the wages paid for services performed outside the United States."
The employee states which test they expect to meet, the bona fide residence test or the physical presence test, estimates the housing cost amount and signs a certification. The instructions on page 2 say to give the form to the U.S. employer. The exclusion itself is claimed on Form 2555, which the instructions say is attached to Form 1040 or Form 1040-SR.
You can fill out Form 673 free in your browser on this page and download it without an account.
First name and initial, last name and Social Security number.
The calendar year, or another tax year with its beginning and ending dates, for which the employee expects to qualify for the foreign earned income exclusion.
The foreign country, the start of the uninterrupted residence period, the expected end date, and a statement about residence declarations made to foreign authorities.
The foreign country, the tax year or the part of it with start and end dates, and the statement about the 330 full-day requirement.
Lines 1 to 6 list rent, utilities other than telephone charges, property insurance, occupancy tax, nonrefundable leasehold fees and household repairs. Line 7 adds them, line 8 is the estimated base housing amount and line 9 is the difference.
A declaration under penalties of perjury, with statements about other employers and about notifying the employer after a disqualification, then the signature and date.
Enter the first name and initial, last name and Social Security number at the top of the form.
In Part I, enter the calendar year, or the beginning and ending dates of another tax year, for which the statement is made.
Check the Bona Fide Residence Test box or the Physical Presence Test box, then fill in the foreign country names and the dates that test asks for.
Enter estimated amounts on Part II, lines 1 to 6, add them on line 7, enter the estimated base housing amount on line 8 and subtract it on line 9. The instructions say eligible housing expenses are limited depending on the location of the foreign tax home and point to Pub. 54 and the Instructions for Form 2555.
Sign and date the certification. It says the employee will immediately notify the employer if disqualified for the exclusions and advise what part, if any, of the period they are qualified for.
Hand the completed form to the U.S. employer. The instructions say the employer will then withhold the correct amount of federal income tax from pay.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to give Form 673 to the U.S. employer to claim the exemption from U.S. income tax withholding on wages earned abroad.
The certification says the exemption from withholding is not a determination by the IRS that any amount paid is excludable from gross income under section 911(a).
The instructions say to complete Form 2555 to claim the foreign earned income exclusion or the foreign housing exclusion or deduction, and to attach it to Form 1040 or Form 1040-SR.
The instructions say Form 2555-EZ is not available after tax year 2018, and that from tax year 2019 Form 2555 is used to claim the foreign earned income exclusion.
The What's New section says new tax home rules apply for tax years beginning after December 31, 2017, for certain individuals serving in a combat zone in support of the U.S. Armed Forces.
An employee who is a U.S. citizen completes it and gives it to the U.S. employer, which uses it for payroll withholding.
No tool matches that search.
A U.S. citizen employee gives it to the U.S. employer. The About Form 673 page says it is filed with the U.S. employer to claim an exemption from U.S. income tax withholding on wages earned abroad.
No. The instructions say the exclusion is claimed on Form 2555, attached to Form 1040 or Form 1040-SR. Form 673 only concerns the employer's withholding.
The bona fide residence test under section 911(d)(1)(A) and the physical presence test under section 911(d)(1)(B), which the form describes as the tax home and 330 full-day requirements within a 12-month period.
The information for employers says that if for any reason the employer believes the employee will not qualify for the exclusions, it should disregard Form 673.
Rent, utilities other than telephone charges, real and personal property insurance, occupancy tax not deductible under section 164, nonrefundable fees for securing a leasehold, and household repairs.
The certification says the employee will immediately notify the employer and advise what part, if any, of the period they are qualified for.