Identification blocks
The RIC's or REIT's name, address and identification number, the shareholder's identifying number, name and address, the tax year, and VOID and CORRECTED boxes.
2439
Notice to Shareholder of Undistributed Long-Term Capital Gains
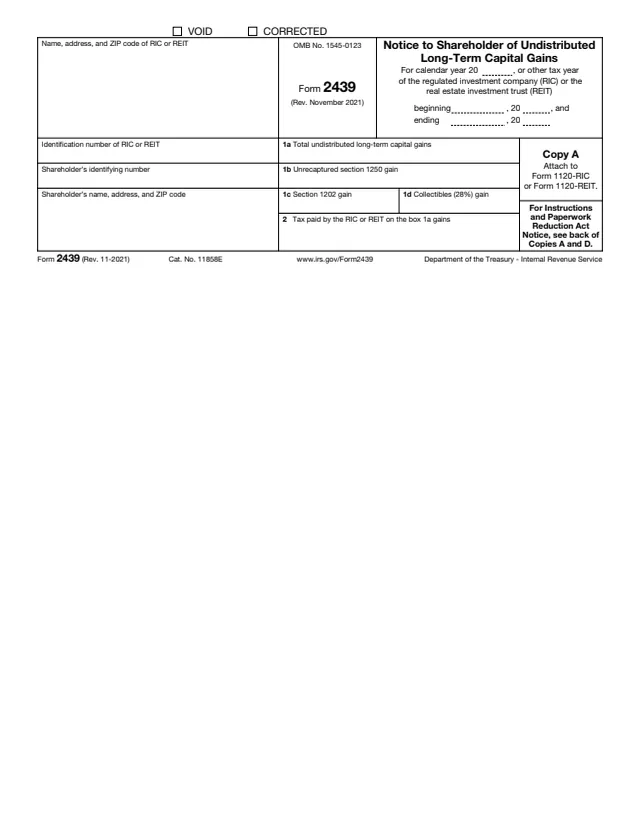
Form 2439, Notice to Shareholder of Undistributed Long-Term Capital Gains, is issued by a regulated investment company (RIC) or a real estate investment trust (REIT). The IRS describes it as the form used to provide shareholders of a RIC or REIT the amount of undistributed long-term capital gains.
The RIC or REIT completes Copies A, B, C and D for each shareholder for whom it paid tax on undistributed capital gains under section 852(b)(3)(D) or 857(b)(3)(C). Copy A goes to the IRS with Form 1120-RIC or Form 1120-REIT, Copies B and C go to the shareholder, and Copy D stays with the RIC or REIT. The shareholder reports the gain and can apply for a refund or credit of the tax shown in box 2.
The instructions for the RIC or REIT and for the shareholder are printed on the back of the copies. You can fill out the PDF free in your browser on this page and download it without an account.
The RIC's or REIT's name, address and identification number, the shareholder's identifying number, name and address, the tax year, and VOID and CORRECTED boxes.
Total undistributed long-term capital gains allocated to the shareholder.
Portions of box 1a that are unrecaptured section 1250 gain, section 1202 gain, and collectibles (28%) gain.
Tax paid by the RIC or REIT on the box 1a gains.
Copy A attaches to Form 1120-RIC or 1120-REIT. Copy B attaches to the shareholder's income tax return. Copy C is for the shareholder's records. Copy D is for the RIC's or REIT's records.
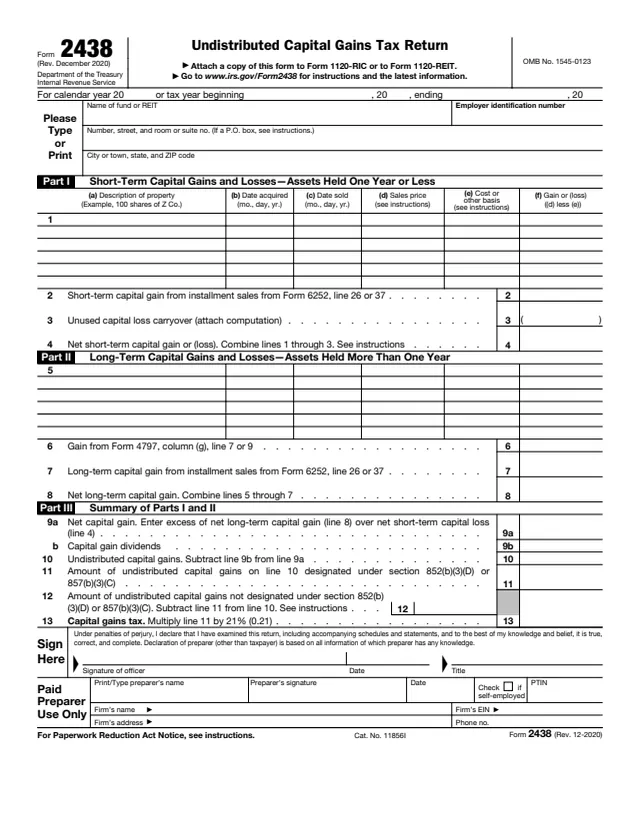
Enter the name, address (including ZIP code) and employer identification number (EIN) of the RIC or REIT as shown on Form 2438, Undistributed Capital Gains Tax Return.
Enter the shareholder's SSN, name and address, or the EIN if the shareholder is not an individual. For an IRA, enter the IRA trust's number, not the SSN of the person for whom the IRA is maintained.
The shareholder's number may be truncated on the copy sent to the shareholder by replacing the first 5 digits with asterisks or Xs. Truncation is not allowed on the copy filed with the IRS or for the RIC's or REIT's own number.
Enter the amount of undistributed capital gains from line 11 of Form 2438 (Rev. December 2020), or the applicable line of the current revision, allocable to the shareholder.
Enter the shareholder's allocable portions in boxes 1b, 1c and 1d, and the tax paid on the box 1a amount in box 2. For box 1c, attach the statement the instructions describe. Do not include section 1202 gain in box 1d.
Attach Copy A to Form 1120-RIC or 1120-REIT, furnish Copies B and C to the shareholder, and keep Copy D.
These steps follow the Instructions for the RIC and the REIT printed on the back of Copies A and D.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Copy A of all Forms 2439 to Form 1120-RIC or Form 1120-REIT when it is filed at the appropriate IRS service center.
The instructions say to furnish Copies B and C to the shareholder by the 60th day after the end of the RIC's or the REIT's tax year.
A nominee has 90 days after the close of the RIC's or REIT's tax year. A nominee acting as custodian of a unit investment trust described in section 851(f)(1) has 70 days, and a nominee resident in a foreign country has 150 days.
The shareholder instructions say individuals report it on line 11, column (h), of Schedule D (Form 1040), estates and trusts on Schedule D (Form 1041), and corporate shareholders in Part II of Form 8949.
The shareholder can apply for a refund or credit of the box 2 tax. For individuals, the form points to line 13a of Schedule 3 (Form 1040) of the 2021 form or the applicable line on the current year form.
A nominee writes "Nominee" on the Copy B it received, attaches it to the Copy A it completed, and files them with the IRS service center where it files its income tax return.
2438
101 fields, 3 pages
1120-RIC
325 fields, 4 pages
1120-REIT
346 fields, 5 pages
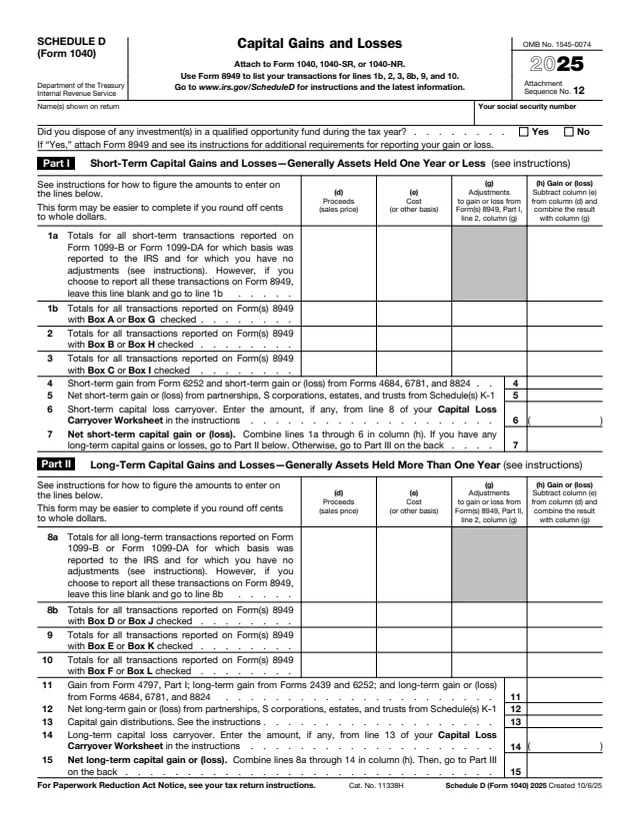
1040
55 fields, 2 pages
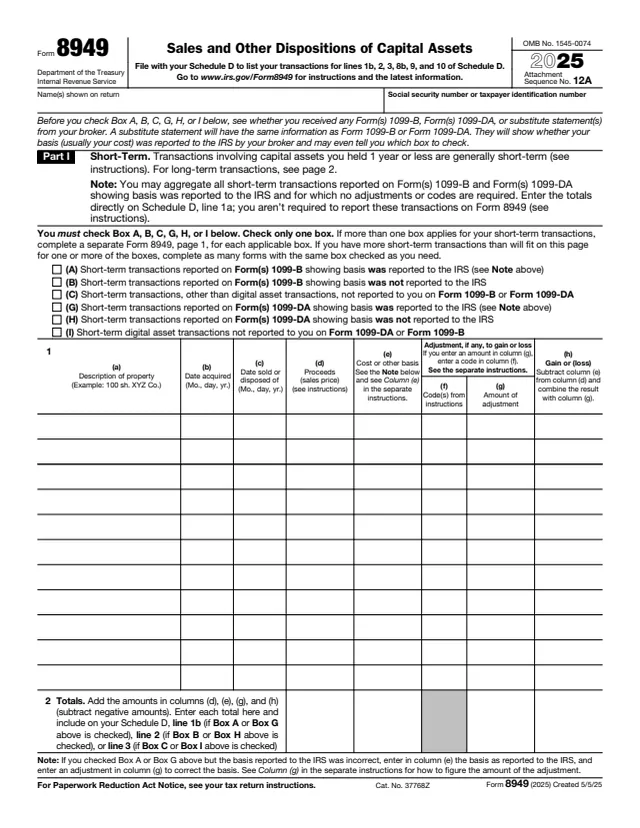
8949
202 fields, 2 pages
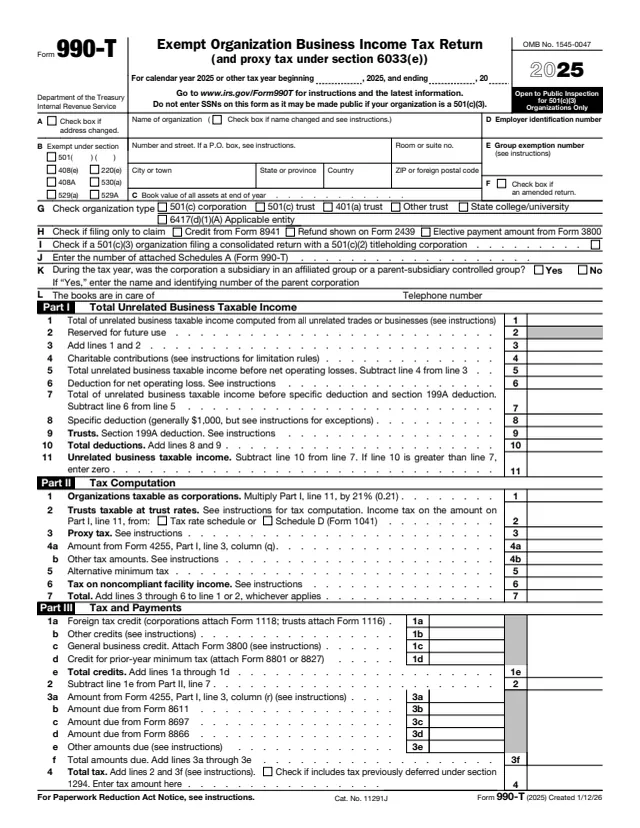
990-T
128 fields, 2 pages
The form is prepared by the fund or trust, not by the shareholder. The shareholder receives it and uses Copy B with an income tax return.
No tool matches that search.
The regulated investment company or real estate investment trust that paid tax on undistributed capital gains. It completes the form for each shareholder.
Copy B says to attach it to the shareholder's income tax return for the tax year that includes the last day of the RIC's or REIT's tax year. Copy C is for the shareholder's records.
The shareholder instructions say to report the total as a long-term capital gain on the appropriate Schedule D. For example, individuals use line 11, column (h), of Schedule D (Form 1040).
It is the tax paid by the RIC or REIT on the box 1a gains. The instructions say the shareholder can apply for a refund or credit of this tax.
The form says it may show only the last four digits for protection, but the RIC or REIT has reported the complete identifying number to the IRS.
The RIC or REIT enters the IRA trust's identification number and sends Copies B and C to the IRA trustee or custodian, not to the IRA owner.