Introduction and the 14581 series
Explains the seven tools: Forms 14581-A, B, D and G for federal, state and local government entities, and Forms 14581-C, E and F for state and local government entities only.
14581-C
Medicare Coverage Compliance Self-Assessment For State and Local Government Employers
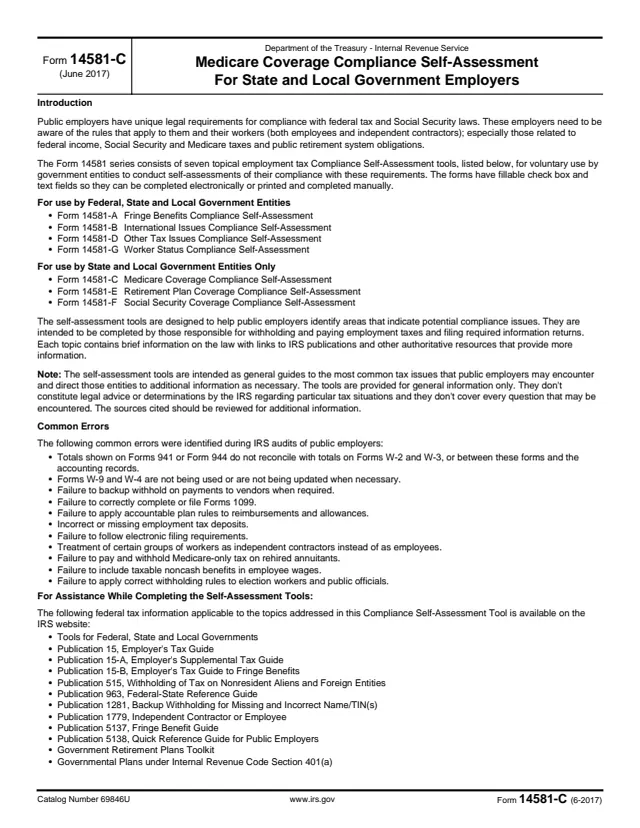
Form 14581-C, Medicare Coverage Compliance Self-Assessment For State and Local Government Employers, is a checklist for government employers. The form says the Form 14581 series consists of seven topical employment tax Compliance Self-Assessment tools for voluntary use by government entities, and lists Form 14581-C among the tools for use by State and Local Government Entities Only.
This form covers Medicare coverage of employees. It asks whether any employees are exempt from Medicare under the continuing employment exception, whether Medicare is withheld from all other employees, and whether Social Security and Medicare tax are withheld and paid on rehired annuitants. Each question has Yes, No and Follow Up boxes, a note on the rules and a Comments field.
The form says the tools are provided for general information only and don't constitute legal advice or determinations by the IRS. You can fill out the PDF free in your browser on this page and download it without an account.
Explains the seven tools: Forms 14581-A, B, D and G for federal, state and local government entities, and Forms 14581-C, E and F for state and local government entities only.
Errors the form says were identified during IRS audits of public employers, including failure to pay and withhold Medicare-only tax on rehired annuitants.
Whether any employees are exempt from Medicare under this exception. The note lists the conditions for employees hired before April 1, 1986, under IRC Section 3121(u).
A list of services the IRC also exempts from mandatory Social Security and Medicare taxes, such as temporary emergency workers and some students and election workers.
Whether there are any employees from whom Medicare is not withheld, other than those who meet the exceptions identified above.
Whether the entity employs rehired annuitants, and whether Social Security tax and Medicare tax are withheld and paid on them.
The form says the tools are intended for those responsible for withholding and paying employment taxes and filing required information returns.
The form says it has fillable check box and text fields so it can be completed electronically or printed and completed manually.
The notes summarize the continuing employment exception, exempt services and rehired annuitant rules, under the heading Medicare Coverage, Publication 963.
Mark one of the three boxes for questions 1, 2 and 3, and for 3a and 3b when the entity has rehired annuitants.
Use the Comments field under each question to record details, and list open items in Notes/Follow-up at the end.
The form says to contact the State Social Security Administrator with any questions about the exemptions listed under question 1.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form prints no filing address, deadline or signature line. It describes itself as a self-assessment tool for voluntary use by government entities.
The form says the tools are provided for general information only. They don't constitute legal advice or determinations by the IRS regarding particular tax situations, and they don't cover every question.
The form says that when an employee retires, employment has ended for the continuing employment exception, so a rehired former employee will be subject to Medicare tax even if previously exempt.
Fringe benefits, international issues, other tax issues and worker status have their own forms, as do retirement plan and Social Security coverage for state and local government entities.
Page 1 lists Publications 15, 15-A, 15-B, 515, 963, 1281, 1779, 5137 and 5138, the Government Retirement Plans Toolkit and Tools for Federal, State and Local Governments.
14581-A
45 fields, 4 pages
14581-A
49 fields, 3 pages
14581-D
100 fields, 3 pages
14581-E
25 fields, 3 pages
14581-F
19 fields, 4 pages
14581-G
31 fields, 3 pages
The form says the self-assessment tools are intended to be completed by those responsible for withholding and paying employment taxes and filing required information returns at a public employer.
No tool matches that search.
The form prints no filing address or deadline. It describes the Form 14581 series as tools for voluntary use by government entities to assess their own compliance.
The form lists it for use by State and Local Government Entities Only. Forms 14581-A, B, D and G are listed for federal, state and local government entities.
The form describes it as applying to an employee hired or rehired before April 1, 1986, who is a member of a public retirement system and meets all of the listed conditions, including continuous employment since March 31, 1986.
The form says a retired employee who is rehired will be subject to Medicare tax, even if the employee was previously exempt because of the continuing employment exception.
No. The form says the tools don't constitute legal advice or determinations by the IRS regarding particular tax situations.