Section I: Identification of Failure
A table of calendar years, the number of participants affected and the total amount of missed required minimum distributions, not including earnings.
14568-H
Model VCP Compliance Statement-Schedule 8: Failure to Pay Required Minimum Distributions Timely
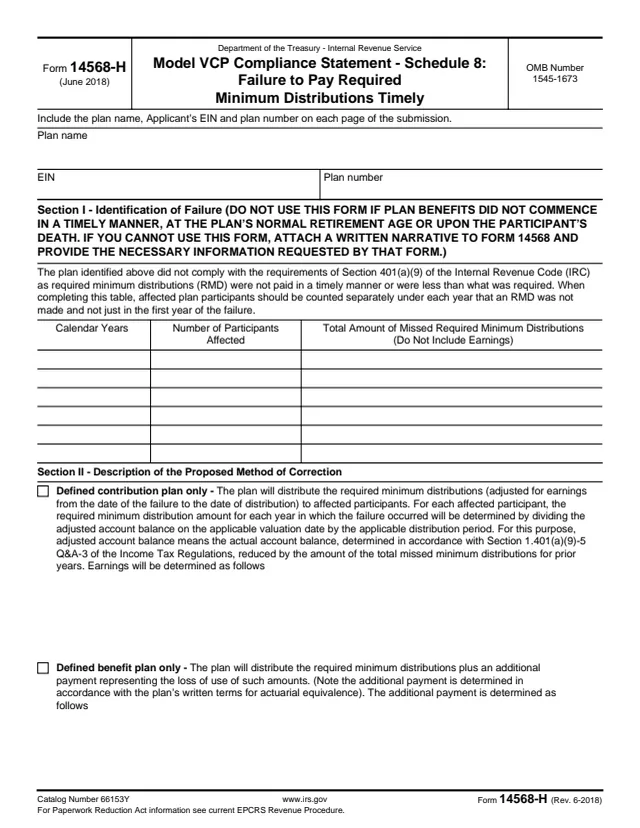
Form 14568-H is Schedule 8 of the Model VCP Compliance Statement. It describes a retirement plan failure under Section 401(a)(9) of the Internal Revenue Code: the form says required minimum distributions (RMD) were not paid in a timely manner or were less than what was required.
The form is written for the plan's Applicant and plan sponsor, not for plan participants. It identifies the failure by year, sets out the proposed correction for a defined contribution or defined benefit plan, asks whether relief from the Section 4974 excise tax is requested, explains how the failure arose and lists the enclosures.
The form says not to use it if plan benefits did not start in a timely manner at the plan's normal retirement age or upon the participant's death; then a written narrative goes with Form 14568 instead. You can fill out the PDF free in your browser on this page and download it without an account.
A table of calendar years, the number of participants affected and the total amount of missed required minimum distributions, not including earnings.
Space to describe how earnings are figured for a defined contribution plan, or how the additional payment is figured for a defined benefit plan, plus a Yes or No question on IRC Section 436(d) lump sum restrictions.
A Yes or No request for relief from excise taxes under IRC Section 4974, a statement about owner-employees or 10 percent owners, and space for the explanation.
An explanation of how and why the failures arose and the measures that have been or will be put in place so they do not recur.
A list of what the plan sponsor encloses, such as calculations for each affected employee or a representative sample.
Enter the plan name, the Applicant's EIN and the plan number. The form says to include them on each page of the submission.
List each calendar year with a missed distribution. The form says affected participants are counted separately under each year an RMD was not made, not only in the first year of the failure.
Complete the paragraph for the plan type. For a defined contribution plan, describe how earnings are determined. For a defined benefit plan, describe the additional payment and answer the Section 436(d) question.
If No is checked on the Section 436(d) question, the form asks for a copy of the plan's most current actuarial certification of its Adjusted Funded Target Attainment Percentage (AFTAP).
Check Yes or No for the Section 4974 relief request and give the explanation if Yes. Then describe how and why the failures arose and the measures taken.
Gather the sample calculations. The form says they show each aspect of the correction method, the interest rate for defined benefit plans, and how earnings were determined for defined contribution plans.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form names the Procedural Requirements Checklist for Form 8950 and says the plan sponsor encloses the listed items with the submission. The form prints no mailing address of its own.
If the defined benefit plan is subject to a Section 436(d) restriction, the form says the plan sponsor contributes, at the time of correction, an amount equal to the corrective distribution.
The form has no separate instructions. For the Paperwork Reduction Act notice it points to the current EPCRS Revenue Procedure.
14568
45 fields, 3 pages
8950
87 fields, 6 pages
14568-E
130 fields, 5 pages
14568-G
20 fields, 1 page
14568-I
156 fields, 5 pages
14568-F
13 fields, 1 page
The form speaks for the Applicant and the plan sponsor of the retirement plan. It asks for the plan name, the Applicant's EIN and the plan number on each page.
No tool matches that search.
The plan's Applicant and plan sponsor. The form describes a plan-level failure and the plan's correction, so it is not a form for individual participants.
The form says not to use it if plan benefits did not start on time at normal retirement age or upon the participant's death. A written narrative attached to Form 14568 is used instead.
No. The column heading says Do Not Include Earnings. Earnings are addressed in the correction method in Section II.
Whether the Applicant requests relief from excise taxes under IRC Section 4974, with space to explain the request.
The items on the Procedural Requirements Checklist for Form 8950, plus the calculations and any AFTAP certification listed in Section V.