Plan identification
Plan name, EIN and plan number, which the form says to include on each page of the compliance statement.
14568-G
Model VCP Compliance Statement- Schedule 7 Failure to Distribute Elective Deferrals in Excess of the 402(g) Limit
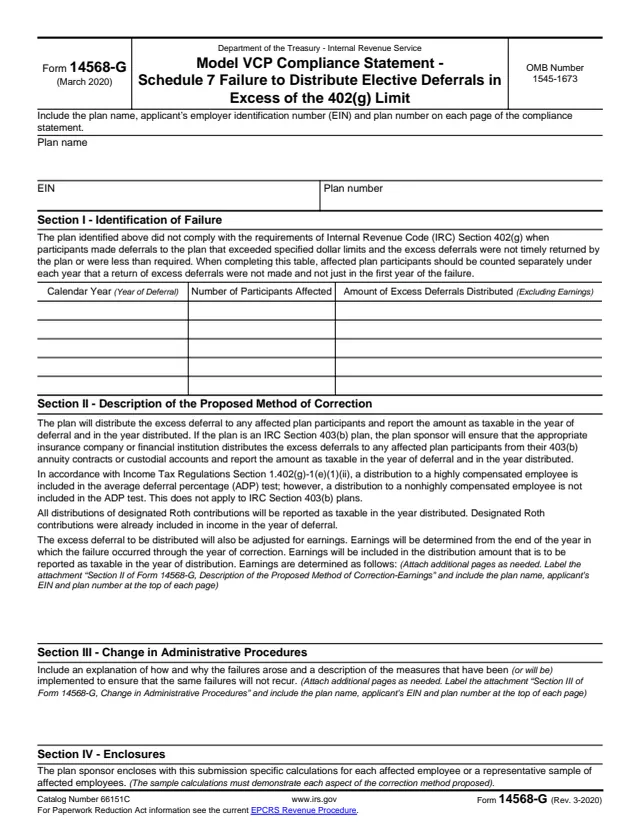
Form 14568-G is the Model VCP Compliance Statement, Schedule 7: Failure to Distribute Elective Deferrals in Excess of the 402(g) Limit. It is for a plan that did not comply with Internal Revenue Code (IRC) Section 402(g) when participants made deferrals that exceeded specified dollar limits and the excess deferrals were not timely returned by the plan or were less than required.
The statement is completed for the plan by the applicant and plan sponsor, not by participants. Section I counts the affected participants and excess deferrals by year, Section II describes the correction, Section III explains how the failure arose and how it will be prevented, and Section IV covers the calculations enclosed with the submission.
The form says to include the plan name, the applicant's employer identification number (EIN) and plan number on each page. This page hosts the March 2020 revision. You can fill out the PDF free in your browser on this page and download it without an account.
Plan name, EIN and plan number, which the form says to include on each page of the compliance statement.
A table with the calendar year (year of deferral), number of participants affected, and amount of excess deferrals distributed, excluding earnings.
The plan distributes the excess deferral and reports it as taxable in the year of deferral and in the year distributed, with rules for the ADP test and designated Roth contributions.
Space to describe how earnings are determined, from the end of the year in which the failure occurred through the year of correction.
An explanation of how and why the failures arose and the measures that have been (or will be) implemented so they do not recur.
Specific calculations for each affected employee or a representative sample of affected employees.
Enter the plan name, EIN and plan number, and repeat them on each page and attachment.
Enter each calendar year, the participants affected and the excess deferrals distributed. The form says to count affected participants separately under each year a return of excess deferrals was not made, not just in the first year of the failure.
Section II prints the correction method. The form says a distribution to a highly compensated employee is included in the ADP test and one to a nonhighly compensated employee is not, and that this does not apply to 403(b) plans.
State how earnings are determined. Label any extra page "Section II of Form 14568-G, Description of the Proposed Method of Correction-Earnings" with the plan name, applicant's EIN and plan number at the top.
Explain how and why the failures arose and the measures taken. Label any extra page "Section III of Form 14568-G, Change in Administrative Procedures".
Enclose the calculations. The form says sample calculations must demonstrate each aspect of the correction method proposed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says the plan sponsor encloses the calculations with this submission. The PDF does not print a mailing address or a filing deadline.
Section II says the excess deferral is reported as taxable in the year of deferral and in the year distributed, and earnings are reported as taxable in the year of distribution.
The form says all distributions of designated Roth contributions will be reported as taxable in the year distributed, because they were already included in income in the year of deferral.
The form says to see the current EPCRS Revenue Procedure for Paperwork Reduction Act information.
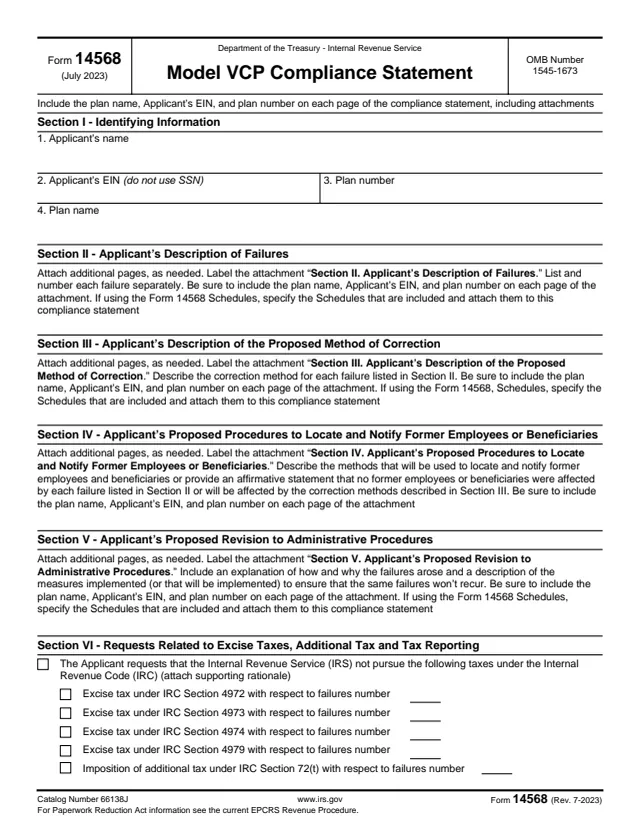
14568
45 fields, 3 pages
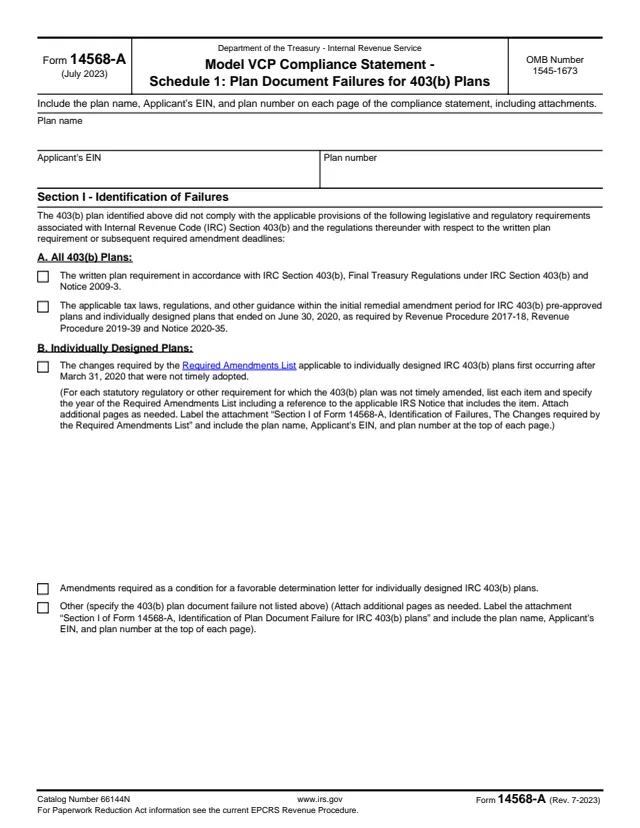
14568-A
18 fields, 2 pages
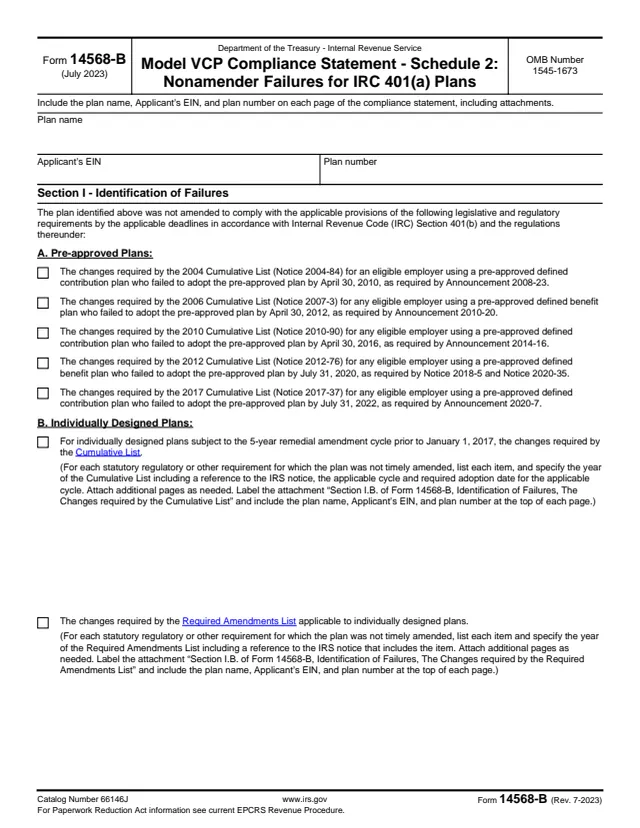
14568-B
21 fields, 2 pages
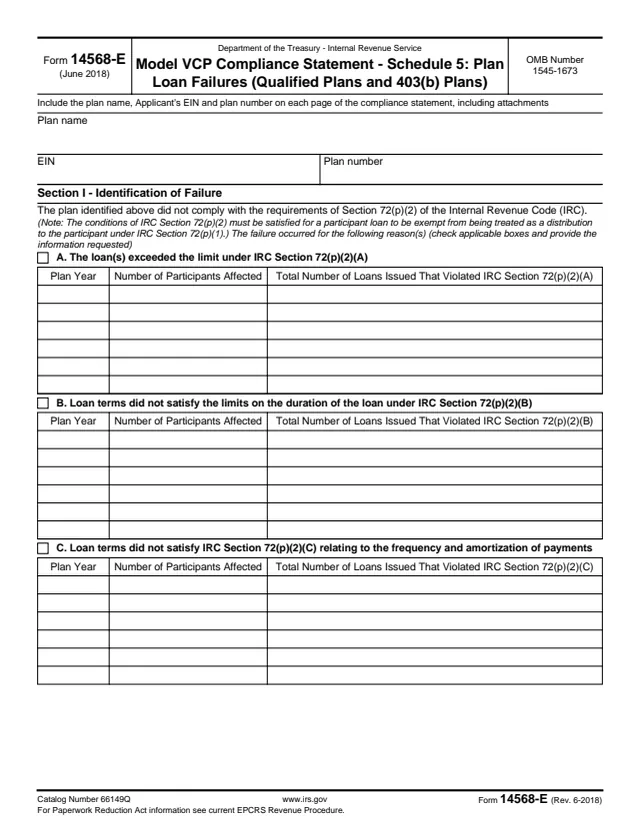
14568-E
130 fields, 5 pages
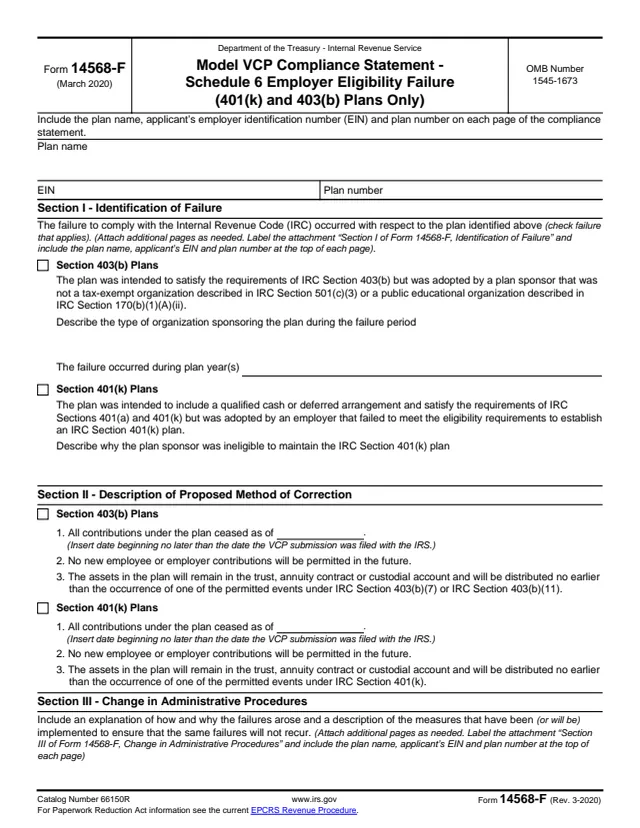
14568-F
13 fields, 1 page
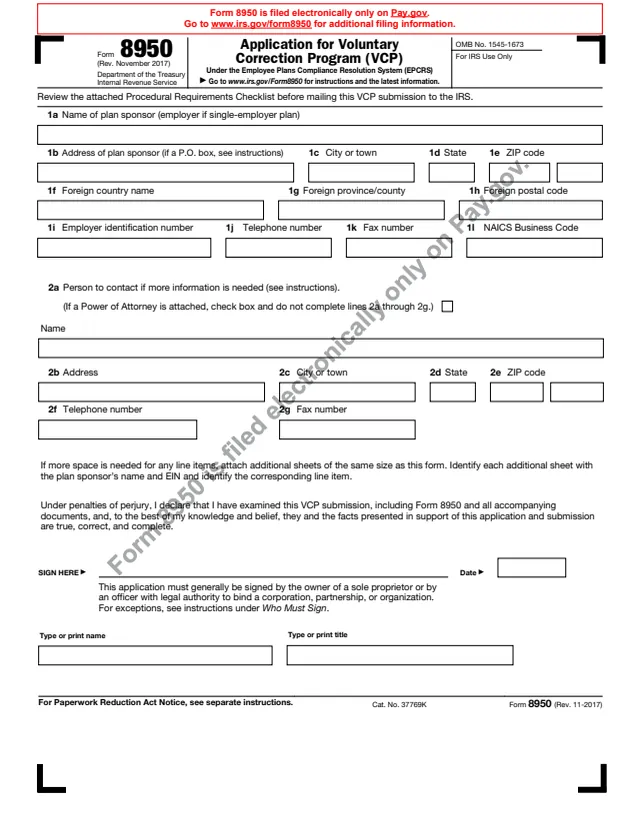
8950
87 fields, 6 pages
The form names the applicant's EIN and says the plan sponsor encloses the calculations with the submission. It goes to the IRS as part of the plan's VCP submission.
No tool matches that search.
The applicant and plan sponsor complete it for the plan. The form says the plan sponsor encloses calculations for each affected employee or a representative sample with the submission.
A plan whose participants made deferrals that exceeded the IRC Section 402(g) dollar limits, where the excess deferrals were not timely returned by the plan or were less than required.
The form says affected participants are counted separately under each year that a return of excess deferrals was not made, not just in the first year of the failure.
The excess deferral is adjusted for earnings from the end of the year in which the failure occurred through the year of correction, and the earnings are reported as taxable in the year of distribution.
The plan sponsor ensures that the insurance company or financial institution makes the distributions from the 403(b) contracts or accounts, and the form says the ADP test rule does not apply to 403(b) plans.
Specific calculations for each affected employee or a representative sample. The form says sample calculations must demonstrate each aspect of the proposed correction method.