Section I: Identification of Failure
Four check boxes, A to D, each with a table for the plan year, the number of participants affected and the number of loans involved.
14568-E
Model VCP Compliance Statement- Schedule 5: Plan Loan Failures(Qualified Plans and 403(b) Plans)
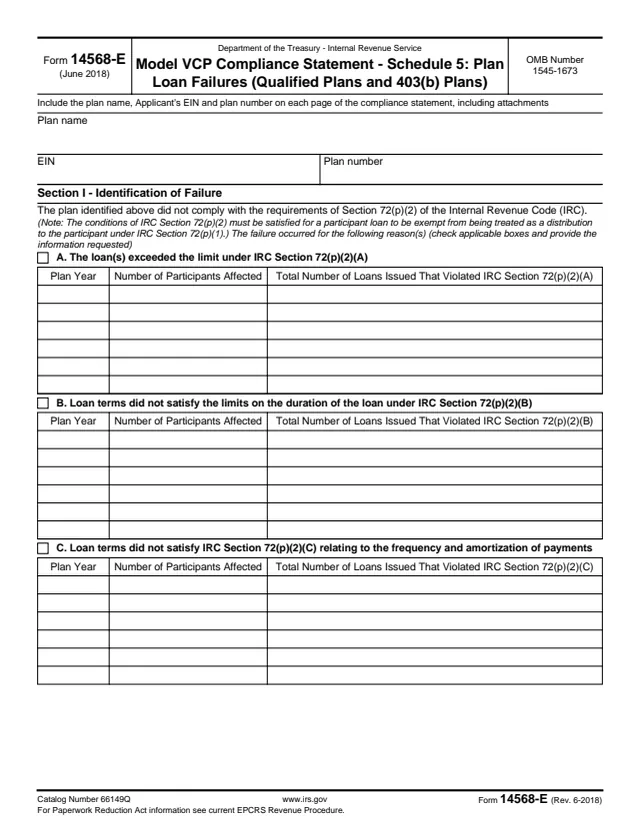
Form 14568-E is Schedule 5 of the Model VCP Compliance Statement, for plan loan failures in qualified plans and 403(b) plans. The form says it applies when the plan "did not comply with the requirements of Section 72(p)(2) of the Internal Revenue Code (IRC)", which sets the conditions a participant loan has to meet to avoid being treated as a distribution.
The plan sponsor, called the Applicant on the form, completes it. It identifies the loan failures, checks eligibility to use the schedule, explains how the failures happened, proposes a correction method, describes changes to administrative procedures, states the relief requested and lists the enclosures. Section VII refers to the Procedural Requirements Checklist for Form 8950. The form says to include the plan name, the Applicant's EIN and the plan number on each page.
The PDF has no separate instructions. You can fill out Form 14568-E free in your browser on this page and download it without an account.
Four check boxes, A to D, each with a table for the plan year, the number of participants affected and the number of loans involved.
Three yes or no questions, A to C, on key employees and owner-employees, the purpose of the request, and whether correction ends before the maximum repayment period expires.
A narrative space to explain how and why the plan loan failures occurred.
Parts A to C set out correction methods for excess loans, noncompliant loan terms and defaulted loans. Part D proposes reporting the loans as deemed distributions on Form 1099-R in the year of correction.
Section V describes measures to keep the failures from recurring. Section VI has three yes or no requests for relief on deemed distribution reporting.
Lists what the plan sponsor encloses: loan agreements, original and any modified amortization schedules, and calculations for each affected employee or a representative sample.
Enter the plan name, the Applicant's EIN and the plan number. The form says to include them on each page of the compliance statement, including attachments.
Check each box that applies and give the plan year, the number of participants affected and the total number of loans that violated the rule or are in default.
Answer A, then B or C as the form directs. If B is answered No, the form says to stop and make any request in a detailed written attachment to Form 14568 instead.
Explain how and why the plan loan failures occurred.
Check the correction method that applies. For defaulted loans, choose how interest on missed repayments is figured and whether the plan sponsor or the affected participants pay it. Check Part D only to propose deemed distribution reporting in the year of correction.
Describe the new administrative procedures, answer the three relief requests, and gather the enclosures listed in Section VII.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Section VII refers to the items listed on the Procedural Requirements Checklist for Form 8950, plus the enclosures the form names. The form itself prints no mailing address or due date.
If an affected participant is a key employee or owner-employee and the request is not limited to year-of-correction reporting, the form says not to use Form 14568-E and to file a detailed written attachment to Form 14568.
The form says the period is generally five years from the original date of the loan, except for home loans described in IRC Section 72(p)(2)(B)(ii).
The form notes that the IRS may determine that the plan sponsor should pay all or part of the additional unpaid interest, and will then ask for a revised submission.
Under Section IV D, the loans are reported on Form 1099-R for the year of correction, and the plan sponsor pays any income tax withholding that was required in connection with the failure.
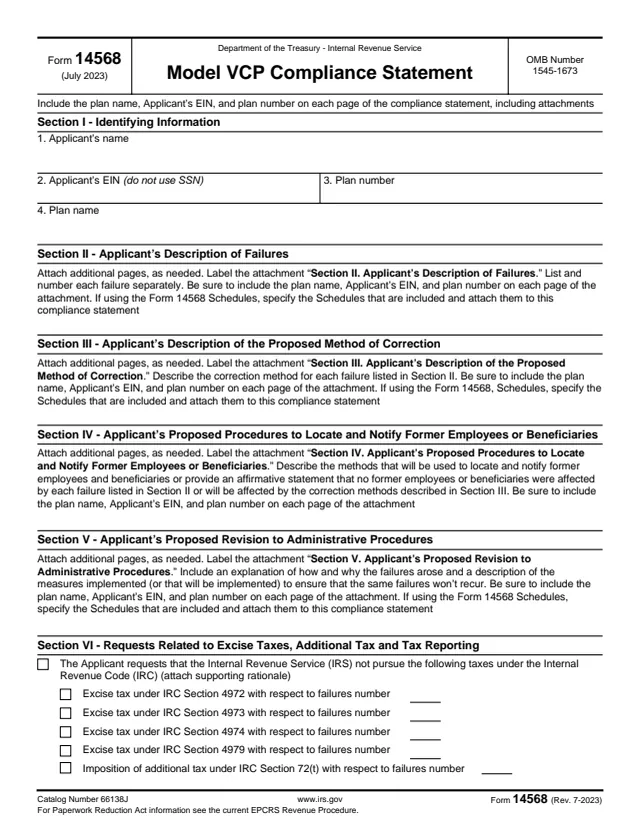
14568
45 fields, 3 pages
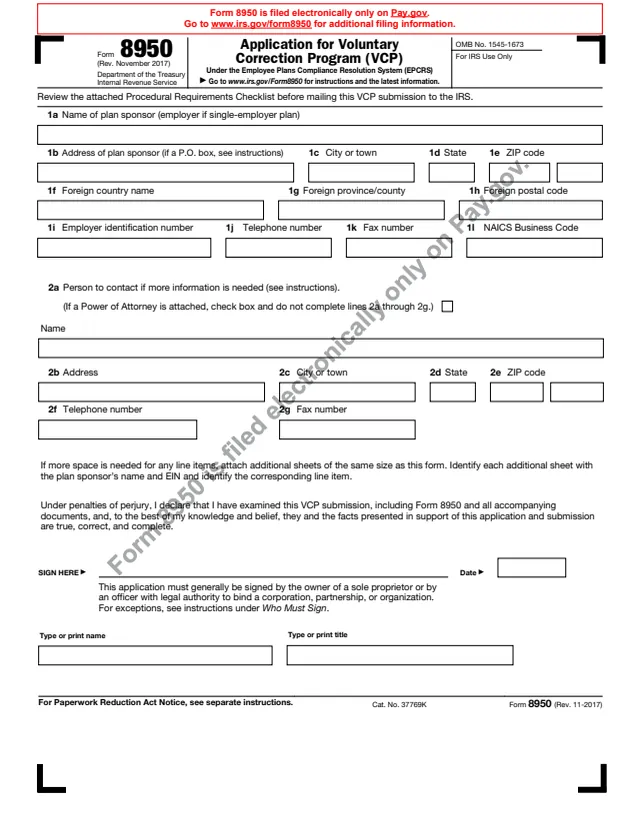
8950
87 fields, 6 pages
1099-R
257 fields, 9 pages
14568-A
18 fields, 2 pages
14568-B
21 fields, 2 pages
14568-H
36 fields, 2 pages
The plan sponsor of the plan completes it as part of its correction request. Plan participants do not file it, although the form describes corrective repayments that affected participants make to the plan.
No tool matches that search.
The plan sponsor, called the Applicant on the form. It covers participant loan failures in qualified plans and 403(b) plans.
No separate instructions are linked to it. The PDF itself explains each choice, and its Paperwork Reduction Act note points to the current EPCRS Revenue Procedure.
The form says to stop if an affected participant is a key employee or owner-employee and the request is not limited to reporting the loan as a deemed distribution in the year of correction. Relief is then requested in a written attachment to Form 14568.
The form says it is generally five years from the original date of the loan, except for home loans, and that the original date is when the participant received the loan proceeds.
The form has boxes for the plan sponsor or the affected participants, and notes that the IRS may decide the plan sponsor should pay all or part of it.
Section VII lists a copy of each original loan agreement, the original and any modified amortization schedules, and calculations for each affected employee or a representative sample.