Pages 1 to 3: instructions
What a CWA is, its legal background, the IRS policy under Revenue Procedure 89-47, who can apply, when and where to apply, the documents to attach and what happens after the IRS receives the application.
13930
Application for Central Withholding Agreement
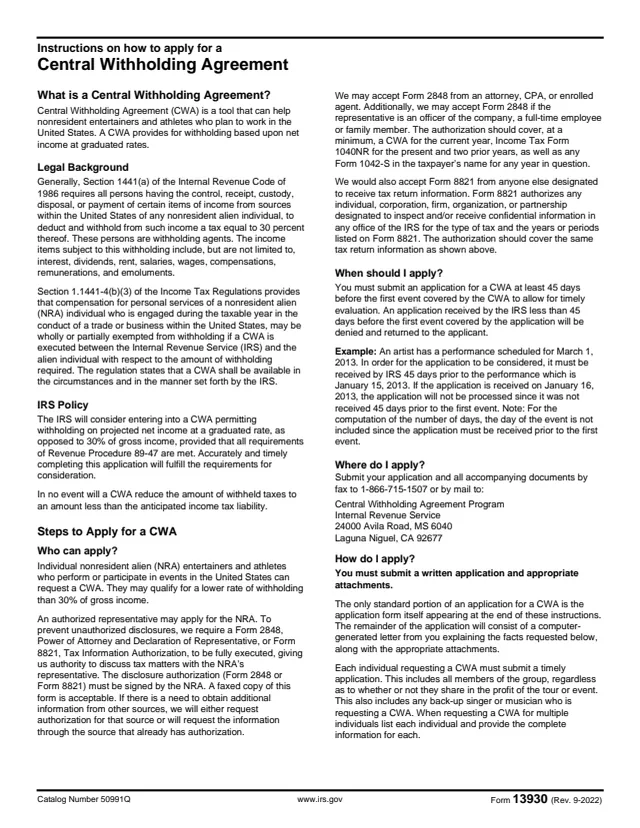
Form 13930 is the IRS Application for Central Withholding Agreement. The instructions say a Central Withholding Agreement (CWA) is a tool that can help nonresident entertainers and athletes who plan to work in the United States, and that it provides for withholding based upon net income at graduated rates, as opposed to 30% of gross income.
The application is sent to the IRS Central Withholding Agreement Program by the nonresident alien (NRA) entertainer or athlete or by an authorized representative. A CWA is an agreement between the NRA, a designated withholding agent and the IRS, and the instructions say it is effective only when all three have signed it. The instructions also say that in no event will a CWA reduce the amount of withheld taxes to an amount less than the anticipated income tax liability.
Pages 1 to 3 of the PDF hold the instructions. The application form follows, with a continuation page for contact persons and a continuation sheet for entertainment groups with several nonresident aliens. You can fill out Form 13930 free in your browser on this page and download it without an account.
What a CWA is, its legal background, the IRS policy under Revenue Procedure 89-47, who can apply, when and where to apply, the documents to attach and what happens after the IRS receives the application.
Legal name, address, U.S. taxpayer ID, date of birth, countries of residence and citizenship, athlete or entertainer, group name, percentage share of net income, stage name, marital status and business details, plus the EIN where 1042 deposits are made.
Firm, contact person, address, U.S. taxpayer ID (EIN/SSN), voice and fax numbers, whether the agent is enrolled in EFTPS, and whether it acts as promoter, agent, venue or other. A declaration under penalties of perjury, signature and date follow.
Name, firm, address and voice and fax numbers for the valid Form 2848 or Form 8821 holder the IRS contacts for more information. A continuation page holds more contact persons.
For entertainment groups with multiple nonresident aliens: the athlete or entertainer fields repeated for each member, with boxes marked IRS Use Only.
The instructions say the application is due at least 45 days before the first event covered by the CWA. An application the IRS receives less than 45 days before the first event will be denied and returned. The day of the event is not counted.
If a representative applies, the NRA signs Form 2848 or Form 8821. The instructions say it should cover, at a minimum, a CWA for the current year, Form 1040NR for the present and two prior years, and any Form 1042-S in the taxpayer's name for any year in question.
Fill in the athlete or entertainer, the withholding agent and any contact person. Use the continuation sheet for more than one entertainer. The form says it is signed by each NRA on the application unless signed by a POA with authority under Form 2848.
The rest of the application is a computer-generated letter with the facts the instructions list and the perjury statement they quote. The initial application includes the NRA names, SSN or ITIN if known, tour dates or event, POA as appropriate and a preliminary budget.
Entertainers attach income contracts, merchandising and sponsorship documents, an itinerary, a budget spreadsheet of gross income and U.S. expenses, and prior CWAs. Athletes attach bout and other agreements, event details, an expense spreadsheet and the travel party list.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to send the application and all documents by fax to 1-866-715-1507 or by mail to Central Withholding Agreement Program, Internal Revenue Service, 24000 Avila Road, MS 6040, Laguna Niguel, CA 92677.
At least 45 days before the first event covered by the CWA. The instructions give an example: for a performance on March 1, 2013, the application had to be received by January 15, 2013.
The instructions say the applicant is contacted within 3 business days of assignment to a Tax Specialist. If the request is granted, the specialist notifies the applicant in writing and provides the agreement for signature.
The withholding agent withholds and pays the tax through EFTPS on the dates and in the amounts in the CWA, gives a final accounting, and files Form 1042 and Form 1042-S for each tax year in which income is paid.
The instructions say an NRA who worked in the US in a prior tax year will not be granted a CWA unless in paying and filing compliance, and that the NRA agrees to file Form 1040NR for the year of the CWA.
The instructions say tours crossing calendar years may require additional information and will require a separate CWA for each year.

2848
92 fields, 2 pages
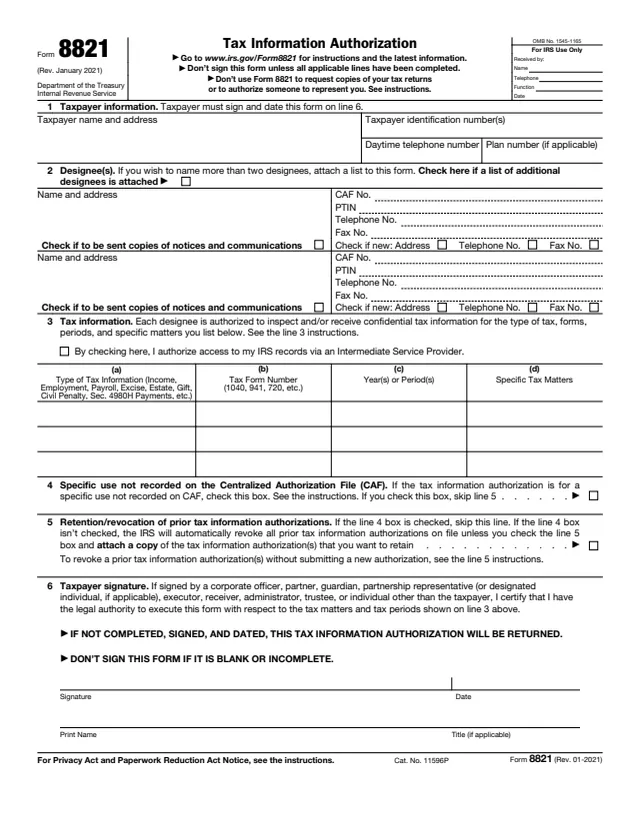
8821
45 fields, 1 page
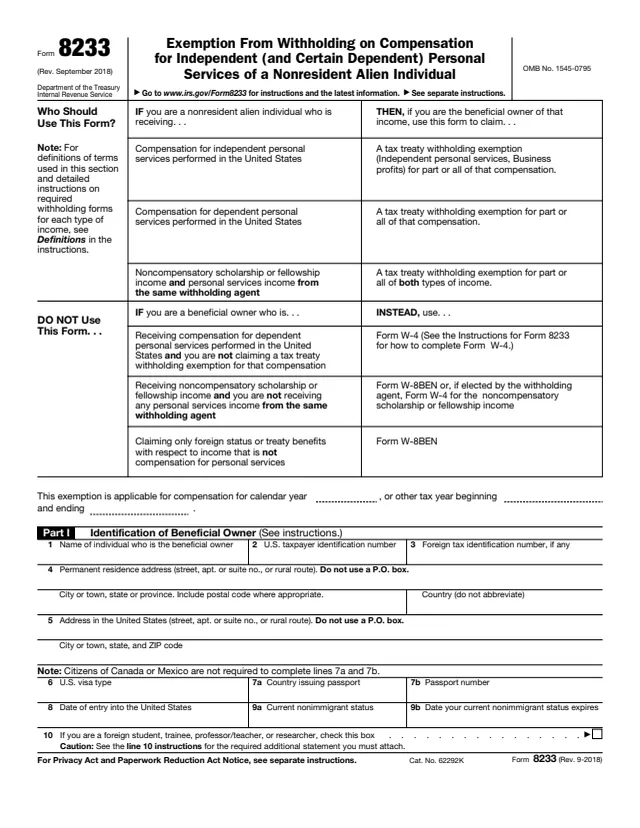
8233
51 fields, 2 pages
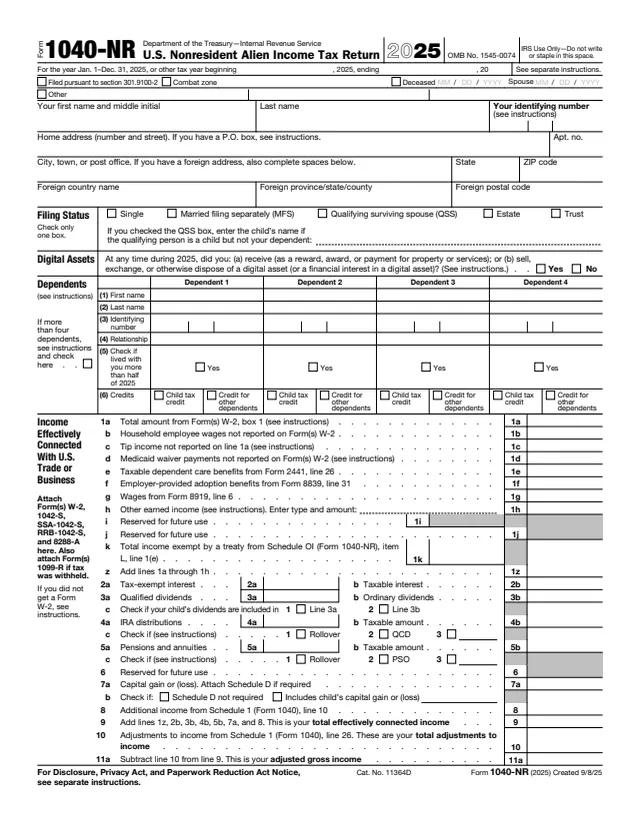
1040-NR
171 fields, 2 pages
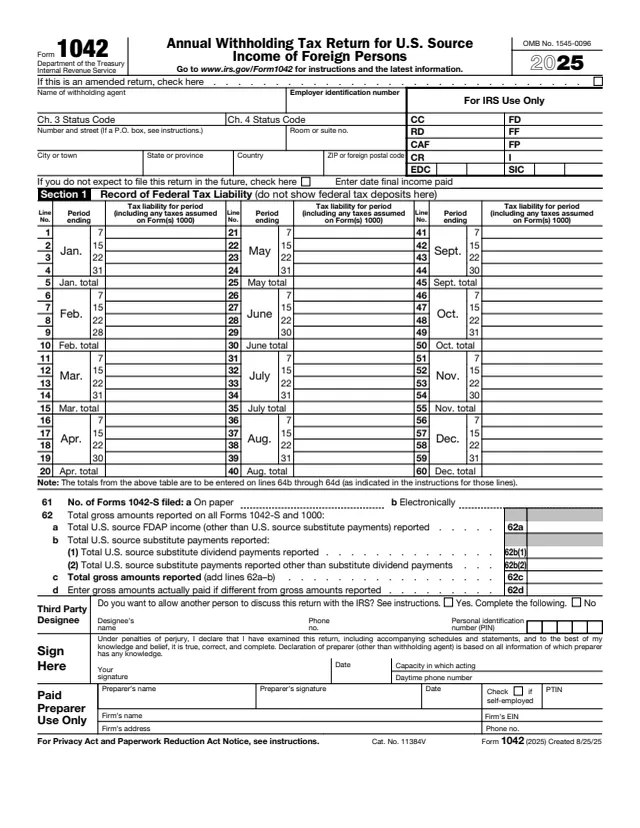
1042
134 fields, 2 pages
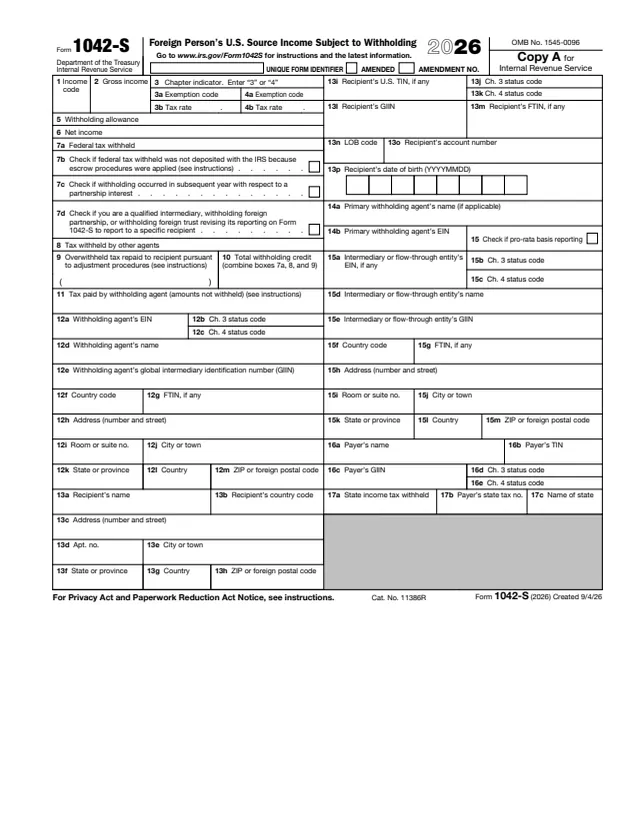
1042-S
300 fields, 7 pages
The instructions say individual nonresident alien entertainers and athletes, or their authorized representatives, apply. The completed application goes to the IRS.
No tool matches that search.
The instructions describe it as a tool for nonresident entertainers and athletes who plan to work in the United States. It provides for withholding on projected net income at graduated rates instead of 30% of gross income.
The instructions say that in no event will a CWA reduce the amount of withheld taxes to an amount less than the anticipated income tax liability.
At least 45 days before the first event covered. The instructions say an application received less than 45 days before the first event will be denied and returned.
Yes. An authorized representative may apply, with a Form 2848 or Form 8821 signed by the NRA.
The instructions say the designated withholding agent is an independent third party unrelated to the NRA, or entities owned by the NRA. The CWA program requires a US bank account and enrollment in EFTPS.
They are printed on pages 1 to 3 of the same PDF, before the application form.