Header
Tax year, the Form 1120-IC-DISC line and schedule the amount is reported on, name and EIN, the product or product line with its activity code, and single or group of transactions.
1120-IC-DISC Sch. P
Intercompany Transfer Price or Commission
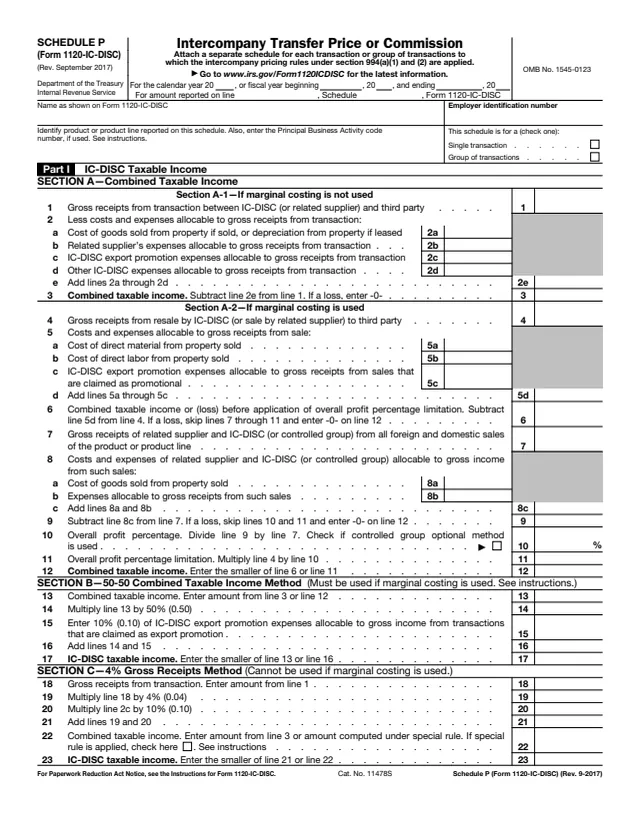
Schedule P (Form 1120-IC-DISC) shows the computation of taxable income used in figuring the transfer price from a related supplier to an interest charge domestic international sales corporation (IC-DISC), or the IC-DISC commission from a related supplier. It is attached to Form 1120-IC-DISC, the information return IC-DISCs, former DISCs and former IC-DISCs file.
The form says to attach a separate schedule for each transaction or group of transactions to which the intercompany pricing rules under section 994(a)(1) and (2) are applied. Part I figures IC-DISC taxable income under the 50-50 combined taxable income method or the 4% gross receipts method. Part II turns it into a transfer price, and Part III into a commission. The schedule's own instructions say not to complete it when the section 482 method is used.
This is the September 2017 revision. You can fill out Schedule P free in your browser on this page and download it without an account.
Tax year, the Form 1120-IC-DISC line and schedule the amount is reported on, name and EIN, the product or product line with its activity code, and single or group of transactions.
Combined taxable income when marginal costing is not used: gross receipts less allocable costs and expenses.
Combined taxable income when marginal costing is used, limited by the overall profit percentage on lines 7 to 11.
The 50-50 combined taxable income method: 50% of combined taxable income plus 10% of export promotion expenses.
The 4% gross receipts method: 4% of gross receipts plus 10% of export promotion expenses, with the special rule box on line 22.
Transfer price from the related supplier to the IC-DISC, or the IC-DISC commission from the related supplier.
Identify the product or product line and enter its Principal Business Activity code. The Instructions for Form 1120-IC-DISC list the codes, which are used only with Schedule P. Check single transaction or group of transactions.
Complete Section A-1 only if marginal costing is not used, or Section A-2 if it is. For line 2d the form says to include an apportionment of deductions that are not directly allocable, such as interest and stewardship expenses.
The form says marginal costing may be used only for sales, or commissions on sales, under the 50-50 method, and not for leases, services or certain sales giving rise to foreign base company sales income.
Complete Section B or Section C. If marginal costing is used, the form says Section B is the one to complete. On line 10, the overall profit percentage may use the optional method in Regulations section 1.994-2(c)(2).
If the 4% method is used and the special rule for transfer prices or commissions applies, check the line 22 box and attach a separate statement showing the limitation.
Part II subtracts line 25d from line 24 for the transfer price. Part III adds lines 27 through 29 for the commission. If the result goes on more than one line of Form 1120-IC-DISC, attach an explanation.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach a separate Schedule P to Form 1120-IC-DISC for each transaction or group of transactions. The line 7 instructions say to attach it when either method is used to figure the IC-DISC's taxable income.
The instructions say Form 1120-IC-DISC is filed by the 15th day of the 9th month after the IC-DISC's tax year ends, and no extensions are allowed.
The form says the pricing rules generally will not be permitted to the extent their application would result in a loss to the related supplier.
Under the 50-50 and 4% methods, the form says the transfer price is recomputed and reported on Schedule P for the year the IC-DISC resells the property.
The instructions say an IC-DISC using intercompany pricing uses the Part II transfer price in Schedule A of Form 1120-IC-DISC.
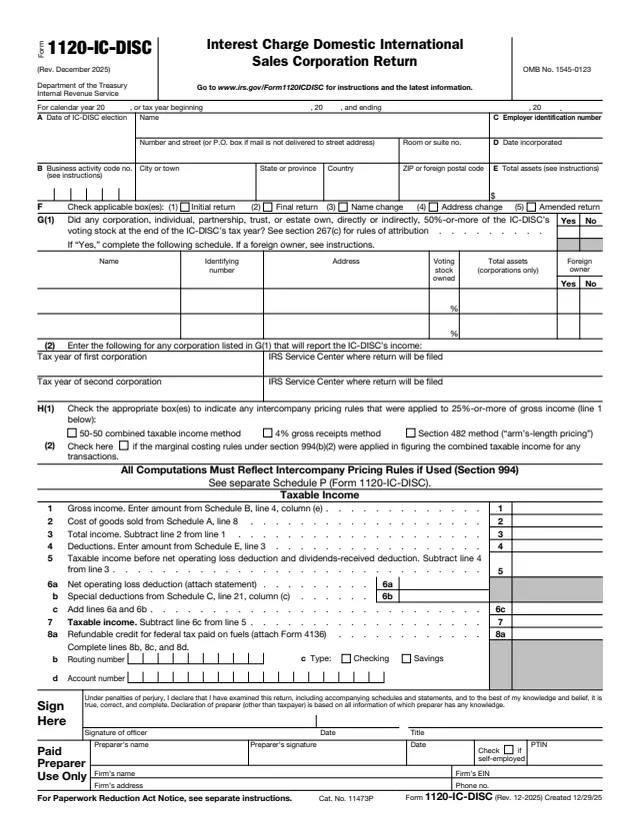
1120-IC-DISC
483 fields, 7 pages
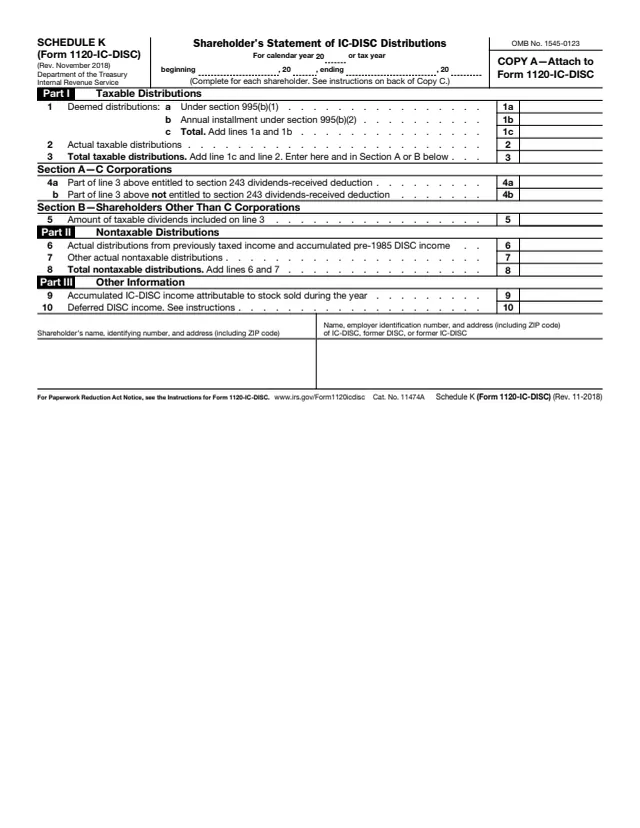
1120-IC-DISC Sch. K
60 fields, 5 pages
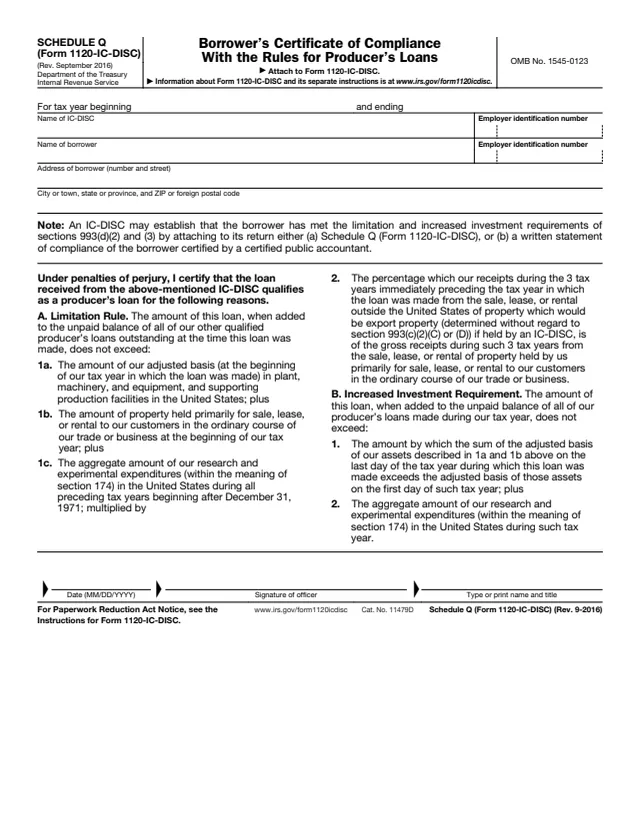
1120-IC-DISC
11 fields, 1 page
4876-A
74 fields, 2 pages
8404
30 fields, 2 pages

1120
481 fields, 6 pages
The IC-DISC completes the schedule and attaches it to its Form 1120-IC-DISC. The related supplier is the other party to the priced transaction. It is a corporate schedule, not a form for individuals.
No tool matches that search.
The instructions say it is a domestic corporation that has elected to be an IC-DISC and whose election is still in effect. The election is made on Form 4876-A.
The IC-DISC, to its Form 1120-IC-DISC. The header asks for the name as shown on Form 1120-IC-DISC.
No. The form says to attach a separate schedule for each transaction or group of transactions to which the intercompany pricing rules are applied.
The 50-50 combined taxable income method in Section B and the 4% gross receipts method in Section C. The form says not to complete Schedule P if the section 482 method is used.
In the Instructions for Form 1120-IC-DISC, which say the codes are used only with Schedule P (Form 1120-IC-DISC).