Items A to E
Type of taxpayer, the shareholder's name, address and identifying number, the IC-DISC's identifying number and name, and the shareholder's tax year.
8404
Interest Charge on DISC-Related Deferred Tax Liability
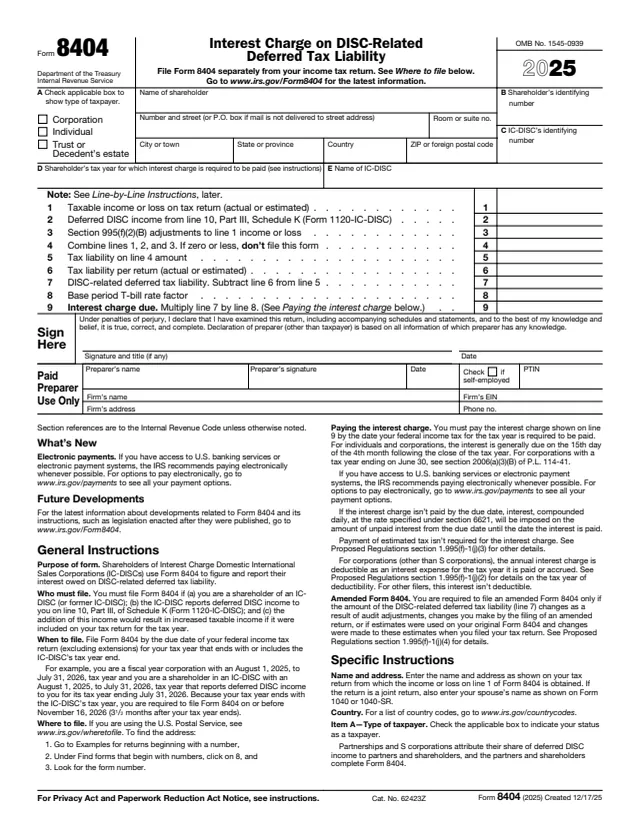
Form 8404, Interest Charge on DISC-Related Deferred Tax Liability, is used by shareholders of Interest Charge Domestic International Sales Corporations (IC-DISCs) to figure and report the interest they owe on DISC-related deferred tax liability.
The form compares the tax on the shareholder's income with and without the deferred DISC income reported on Schedule K (Form 1120-IC-DISC), and multiplies the difference by the base period T-bill rate factor. The form says to file it separately from the income tax return. The instructions are printed on the same two page PDF. This is the 2025 form, which gives a base period T-bill rate factor of 0.041641381 for a 365-day tax year.
You can fill out the PDF free in your browser on this page and download it without an account.
Type of taxpayer, the shareholder's name, address and identifying number, the IC-DISC's identifying number and name, and the shareholder's tax year.
Taxable income or loss on the return, deferred DISC income from Schedule K (Form 1120-IC-DISC), section 995(f)(2)(B) adjustments, and the combined total.
Tax liability on the line 4 amount, tax liability per the return, and the DISC-related deferred tax liability (line 5 minus line 6).
The base period T-bill rate factor and the interest charge due, which is line 7 times line 8.
The declaration under penalties of perjury with signature, title and date, and the paid preparer's name, signature, PTIN, firm name, EIN, address and phone.
Check the type of taxpayer and enter the name and address as shown on the tax return. Individuals enter their social security number in item B and other filers their EIN. Enter the IC-DISC's identifying number from Schedule K (Form 1120-IC-DISC), its name, and the tax year.
Enter the taxable income or loss from the federal income tax return for the tax year that ends with or includes the IC-DISC's tax year end. If the return isn't filed yet, the instructions say to estimate it from all information available.
Enter the deferred DISC income from line 10, Part III, of Schedule K (Form 1120-IC-DISC) and the net section 995(f)(2)(B) adjustments, with a statement if there is more than one. Combine lines 1, 2 and 3 on line 4.
Enter the tax liability with and without the deferred DISC income. For 2025, the instructions list the Form 1040 or 1040-SR line 22 and the Form 1120 Schedule J line 7 amounts as the starting point for line 6.
Subtract line 6 from line 5 to get the DISC-related deferred tax liability.
Enter the base period T-bill rate factor. For 2025 the instructions give 0.041641381 for a 365-day tax year and point to Rev. Rul. 2025-23 for a short or 52-53-week year. Multiply line 7 by line 8 on line 9.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
By the due date of the federal income tax return (excluding extensions) for the tax year that ends with or includes the IC-DISC's tax year end.
The form says to file it separately from the income tax return. For the address, the instructions point to www.irs.gov/wheretofile and the listing for forms that begin with the number 8.
The instructions say the line 9 charge is paid by the date the federal income tax for the year is required to be paid, generally the 15th day of the 4th month after the tax year ends for individuals and corporations.
If the charge isn't paid by the due date, the instructions say interest compounded daily at the section 6621 rate is imposed on the unpaid amount. Estimated tax payments aren't required for the charge.
The instructions say an amended form is required only if line 7 changes because of audit adjustments, an amended return, or changes to estimates used on the original Form 8404.
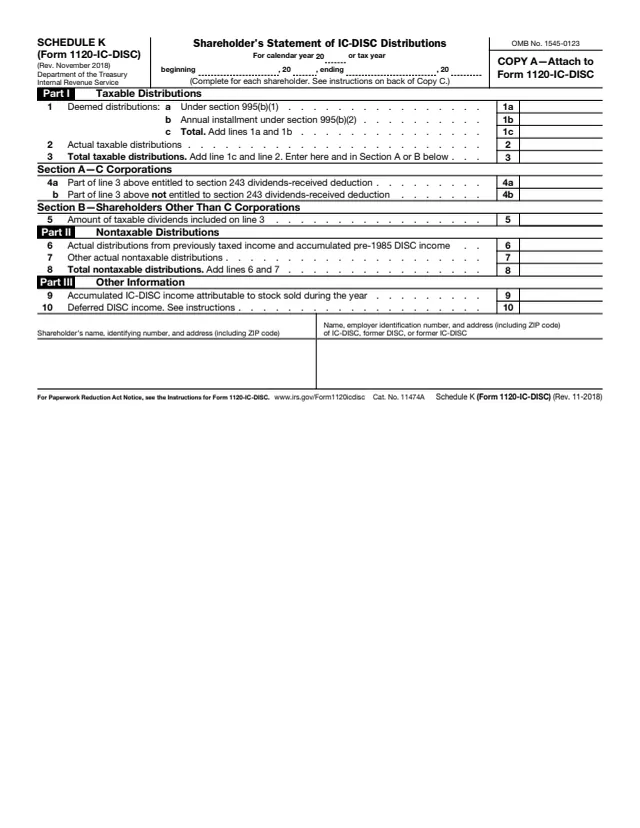
1120-IC-DISC Sch. K
60 fields, 5 pages
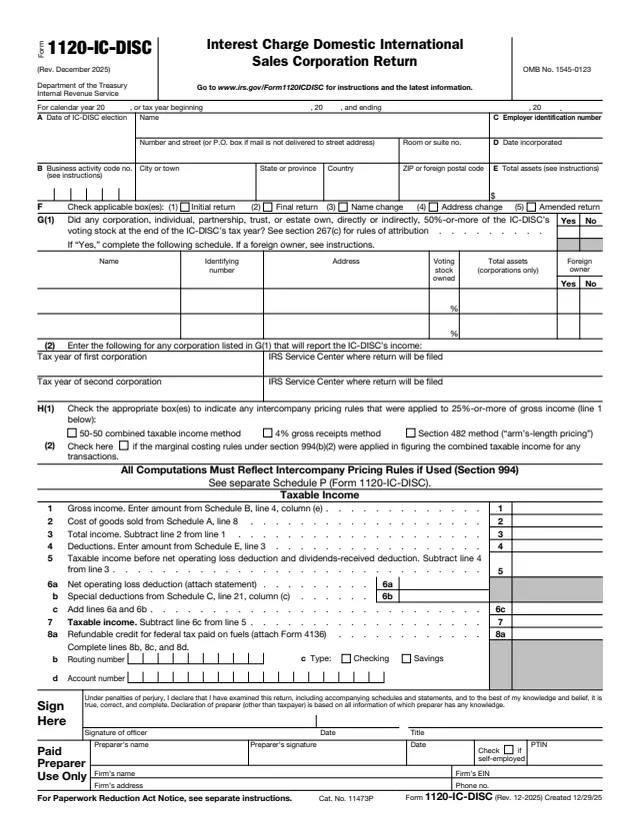
1120-IC-DISC
483 fields, 7 pages

1120
481 fields, 6 pages

1040
199 fields, 2 pages
1040-SR
200 fields, 4 pages
The instructions say Form 8404 is filed by a shareholder of an IC-DISC (or former IC-DISC) when three conditions are all met.
No tool matches that search.
A shareholder of an IC-DISC or former IC-DISC that reports deferred DISC income on Schedule K (Form 1120-IC-DISC), when adding that income would increase taxable income for the year.
No. The form says to file it separately from the income tax return.
By the due date of the federal income tax return, excluding extensions, for the tax year that ends with or includes the IC-DISC's tax year end.
The instructions give 0.041641381 for a 365-day tax year, and point to Rev. Rul. 2025-23 for a short tax year or a 52-53-week tax year.
The form says not to file it.
The instructions say that for corporations other than S corporations it is deductible as interest expense for the year paid or accrued, and that for other filers it isn't deductible.