Part I: corporation details
Name and address of the corporation, item A employer identification number and item B principal business classification.
4876-A
Election To Be Treated as an Interest Charge DISC
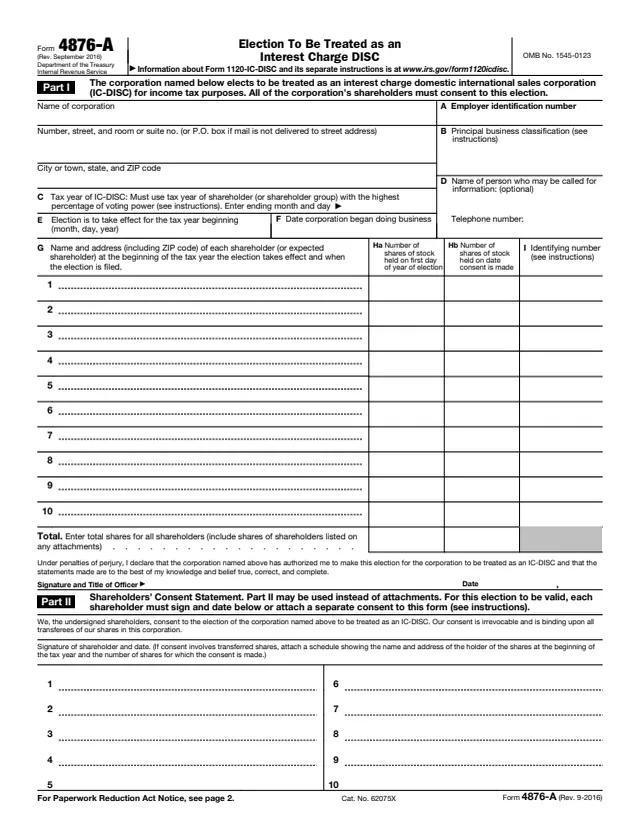
Form 4876-A is the election a corporation files to be treated as an interest charge domestic international sales corporation (IC-DISC) for income tax purposes. The instructions say the election remains in effect until terminated or revoked, and it applies to each shareholder who owns stock in the corporation while the election is in effect.
The form has two parts. Part I holds the corporation's details, its tax year, the date the election takes effect and a list of shareholders with their shares, signed by an officer. Part II is the shareholders' consent statement. The form says all of the corporation's shareholders consent to the election for it to be valid.
The instructions are printed on page 2 of the form. The annual return for an IC-DISC is Form 1120-IC-DISC. You can fill out Form 4876-A free in your browser on this page and download the result without an account.
Name and address of the corporation, item A employer identification number and item B principal business classification.
Item C tax year of the IC-DISC (ending month and day), item D an optional contact name and phone, item E the tax year the election takes effect, and item F the date the corporation began doing business.
Ten rows for each shareholder's name and address, shares held on the first day of the year of election (Ha), shares held on the date of consent (Hb) and identifying number (I), plus a total line.
A declaration under penalties of perjury that the corporation authorized the officer to make the election, with the signature, title and date.
Ten signature spaces where shareholders sign and date their consent. The form says the consent is irrevocable and binding upon all transferees of the shares.
Enter the corporation's name, address with any suite or room number (or a P.O. box if mail is not delivered to the street address) and EIN. For item B, the instructions point to the list of Codes for Principal Business Activity in the Instructions for Form 1120-IC-DISC.
Enter the ending month and day. The form says the IC-DISC uses the tax year of the shareholder (or shareholder group) with the highest percentage of voting power. The instructions cover tax year changes under sections 441(h) and 442.
Optionally name a person the IRS may call and a telephone number, then enter the start of the tax year the election takes effect and the date the corporation began doing business.
List each shareholder (or expected shareholder) at the beginning of the tax year the election takes effect and when it is filed. The instructions say to complete both Ha and Hb for each one. Column I is the SSN for an individual and the EIN for all others.
An authorized officer signs and dates Part I and enters a title. Enter the total shares for all shareholders, including any listed on attachments.
Shareholders sign Part II, or each gives a separate statement worded as the instructions show. For transferred shares, the form says to attach a schedule with the holder at the start of the tax year and the shares covered.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 4876-A with the IRS Service Center where the corporation will file its annual return, Form 1120-IC-DISC.
For the corporation's first tax year, within 90 days after the beginning of the tax year. For any other tax year, during the 90-day period immediately preceding the first day of that tax year.
The instructions say consents are normally attached to Form 4876-A. With reasonable cause, a consent may be filed within an extended period granted by an IRS Service Center, at the same service center.
If more shares are issued or ownership changes between filing and the effective date, the instructions call for a supplemental form marked "SUPPLEMENTAL" within the first 90 days of the tax year the election takes effect.
The instructions say the election remains in effect until terminated or revoked, and point to Regulations section 1.992-2(e).
The form estimates 4 hr., 4 min. for recordkeeping, 1 hr., 5 min. for learning about the law or the form, and 1 hr., 12 min. for preparing and sending it.
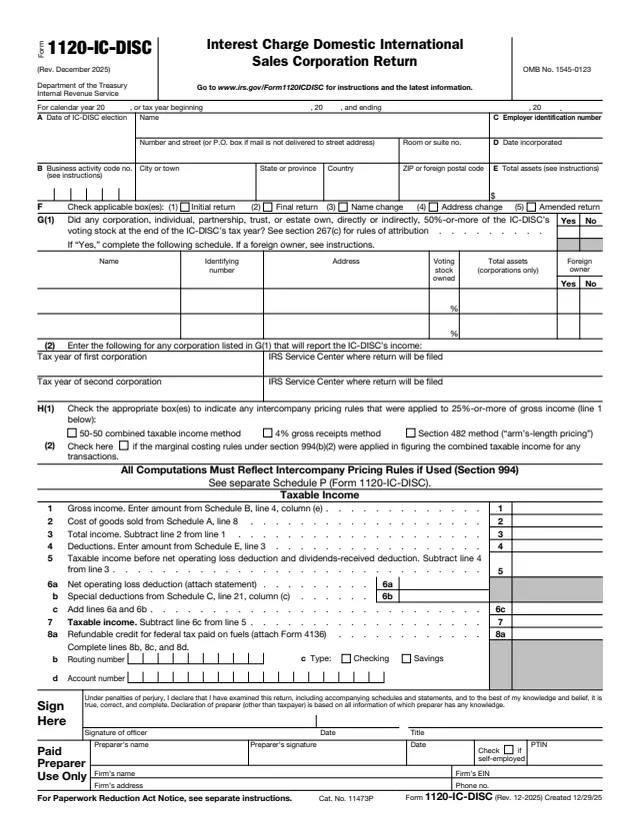
1120-IC-DISC
483 fields, 7 pages
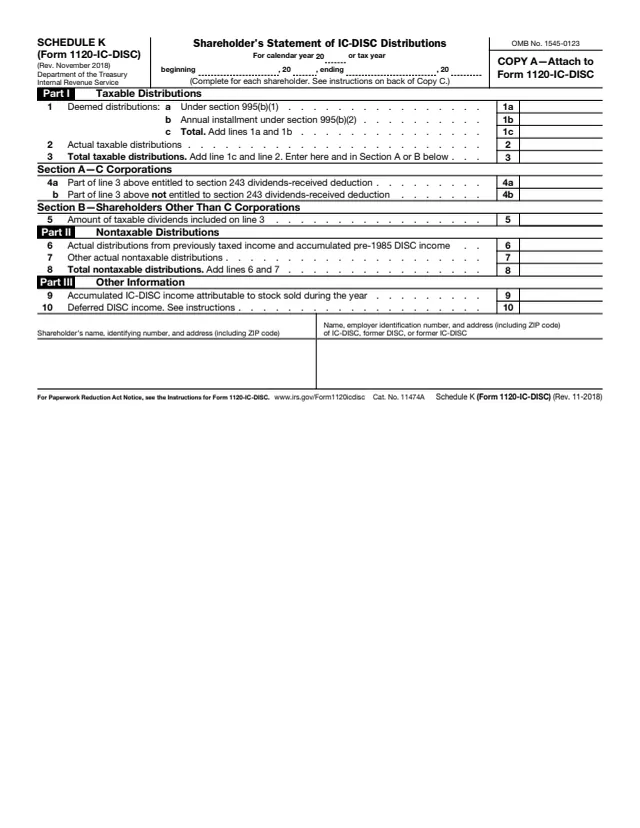
1120-IC-DISC Sch. K
60 fields, 5 pages
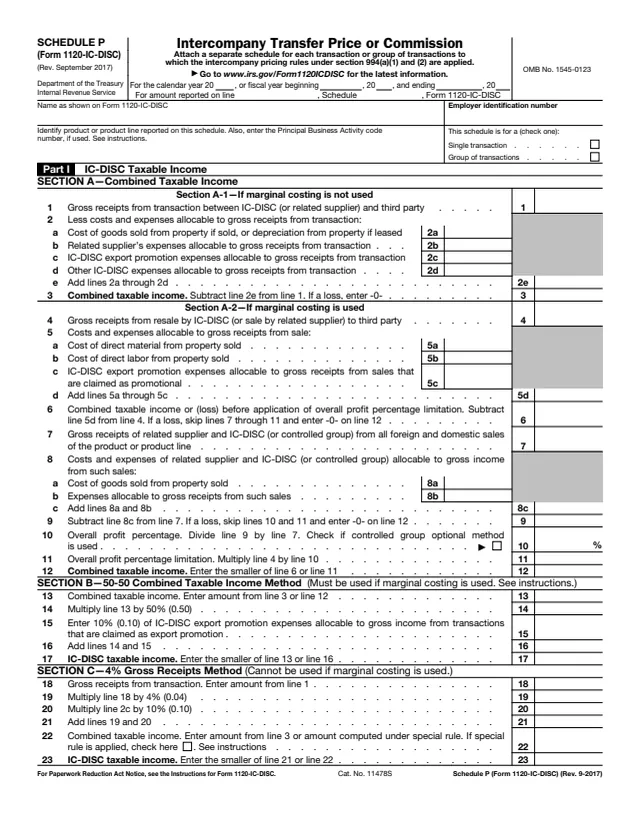
1120-IC-DISC Sch. P
56 fields, 2 pages
1120-IC-DISC
11 fields, 1 page
The instructions say a corporation files Form 4876-A to elect to be treated as an IC-DISC. Its shareholders consent in Part II or in separate statements.
No tool matches that search.
The instructions describe it as a domestic corporation that meets conditions on its organization and international sales and elects IC-DISC treatment. Tests include that at least 95% of gross receipts are qualified export receipts.
An authorized officer of the corporation, such as the president, vice president, treasurer, assistant treasurer or chief accounting officer. Shareholders sign the consent in Part II.
The instructions say the election is valid only if all shareholders sign either the Part II consent or a separate consent statement.
The instructions say S corporations, certain financial institutions and other corporations listed in section 992(d) are not eligible for IC-DISC treatment.
The instructions describe a supplemental Form 4876-A with "SUPPLEMENTAL" written across the top, listing only the new or additional owners, filed within the first 90 days of the tax year the election takes effect.
To the IRS Service Center where the corporation will file Form 1120-IC-DISC, according to the instructions.