Donee and donor information
Donee's name, address and telephone number, the donee's and donor's TINs, and the donor's name and address.
1098-C
Contributions of Motor Vehicles, Boats, and Airplanes
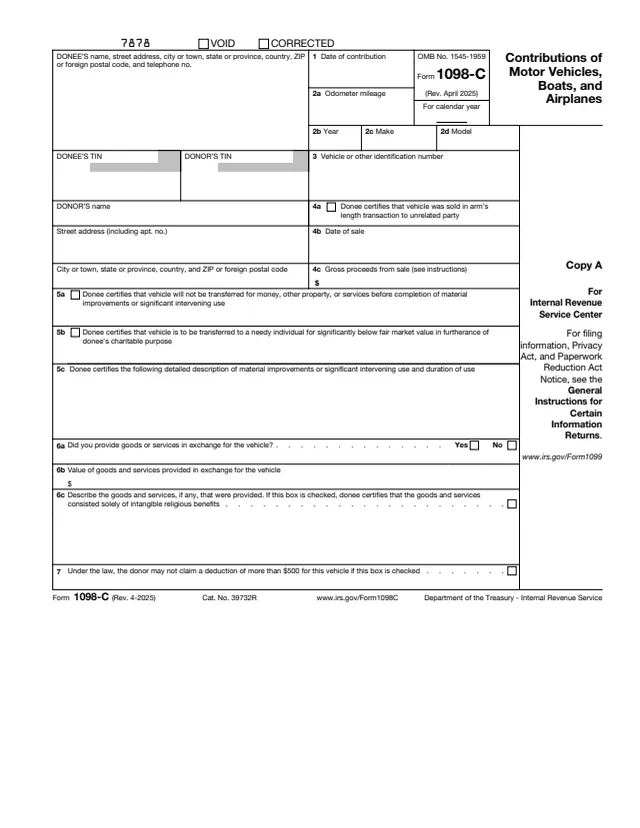
Form 1098-C is an information return a charity, called the donee organization, completes when it receives a donated motor vehicle, boat or airplane. The About page says a donee organization files a separate Form 1098-C with the IRS for each contribution of a qualified vehicle that has a claimed value of more than $500.
A qualified vehicle is any motor vehicle manufactured primarily for use on public streets, roads and highways, a boat or an airplane. The instructions say property held by the donor primarily for sale to customers, such as a car dealer's inventory, is not a qualified vehicle.
The form records the date of the gift, the vehicle's mileage, year, make, model and identification number, and what the charity did or plans to do with it. Copy A goes to the IRS and Copies B and C go to the donor. The instructions say the form is an online fillable form. You can fill it out free in your browser on this page and download it without an account.
Donee's name, address and telephone number, the donee's and donor's TINs, and the donor's name and address.
Date of contribution, odometer mileage, year, make and model, and the vehicle or other identification number.
Certification that the vehicle was sold in an arm's length transaction to an unrelated party, the date of sale and the gross proceeds.
Certifications for a significant intervening use or material improvement, or a transfer to a needy individual well below fair market value, with a description and duration of use.
Whether the donee gave goods or services for the vehicle, their value, and a description, with a box for intangible religious benefits.
The form says the donor may not claim a deduction of more than $500 for this vehicle if this box is checked.
Enter the date the charity received the vehicle. Enter mileage only for motor vehicles, then year, make and model. The instructions say mileage is in miles: kilometers x 0.62137 = miles.
Enter the VIN for a motor vehicle (17 characters), the hull identification number for a boat (12 characters) or the aircraft identification number for an airplane (6 characters).
Check box 4a if the vehicle was sold without a significant intervening use or material improvement and not to a needy individual. Enter the sale date and gross proceeds, generally the sales price, not reduced by expenses or fees.
Check 5a for a planned significant intervening use or material improvement and describe it in 5c. Check 5b for a transfer to a needy individual at a price significantly below fair market value, with no amount in box 4c.
Check Yes or No in 6a. If Yes, give a good faith estimate of the value in 6b and describe the goods and services in 6c. Check the 6c box if the donor received only intangible religious benefits.
Check box 7 if the vehicle has a claimed value of $500 or less or the donor did not provide a TIN. The instructions say then do not file Copy A with the IRS and do not furnish Copy B to the donor.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Copy A goes to the IRS. Copies B and C go to the donor; Copy C is for the donor's records. The instructions say a charity may give its own acknowledgment with the same information instead.
The instructions say the acknowledgment is contemporaneous if furnished no later than 30 days after the date of the sale (box 4a) or the date of the contribution (box 5a or 5b).
The instructions point to the General Instructions for Certain Information Returns for when and where to file. Filers qualified to file on paper may send the black-and-white Copy A printed from the IRS website with Form 1096.
The instructions list penalties for a donee that knowingly furnishes a false or fraudulent acknowledgment, for example the larger of $5,000 or the claimed value multiplied by 39.6% (0.396) when box 5a or 5b applies.
A donor's TIN may be truncated on written acknowledgments, but not on documents filed with the IRS. A filer's TIN may not be truncated on any form.
1096
55 fields, 3 pages
8283
117 fields, 2 pages
8453
23 fields, 2 pages
1098
41 fields, 4 pages
1098-F
35 fields, 4 pages
1098-Q
83 fields, 4 pages
The donee organization that received the vehicle completes the form. The donor receives Copies B and C and does not fill it out.
No tool matches that search.
The charity that received the vehicle, called the donee organization. The donor receives Copies B and C.
The instructions say not to file it for a qualified vehicle with a claimed value of $500 or less. The charity may still give the donor Copy C as the acknowledgment, with box 7 checked.
Motor vehicles manufactured primarily for use on public streets, roads and highways, boats and airplanes. Inventory held for sale to customers is not a qualified vehicle.
The donor instructions say generally no later than 30 days after the charity sold the vehicle (box 4a) or 30 days after the date of the contribution (box 5a or 5b).
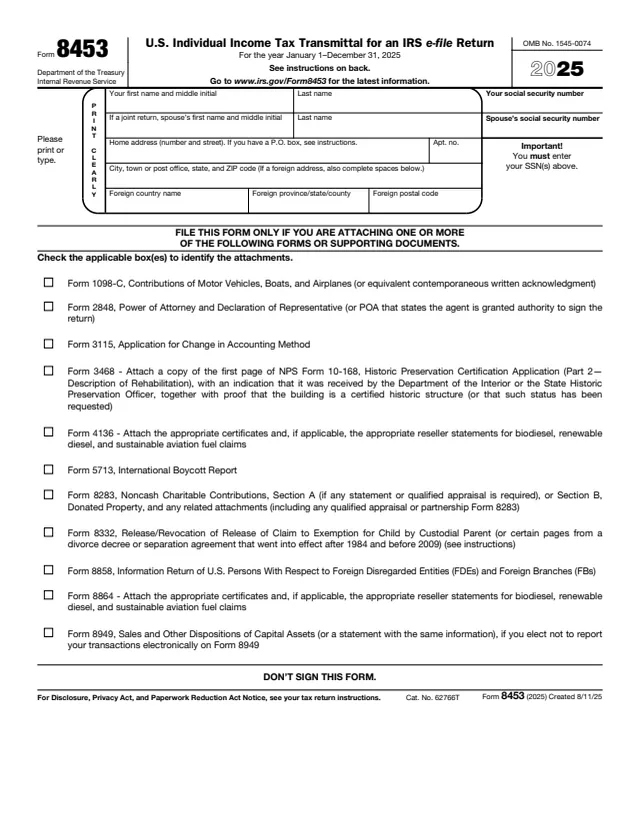
The donor instructions say Copy B is attached to the income tax return to take a deduction of more than $500 for the vehicle. An e-filer may attach it to Form 8453 and mail it, or include it as a PDF attachment if the software permits.
For the donor's protection, the form may show only the last four digits. The donor instructions say the issuer has reported the complete TIN to the IRS.