Header
The name of the partnership and its employer identification number, with Yes and No columns for the questions.
1065
Additional Information for Schedule M-3 Filers
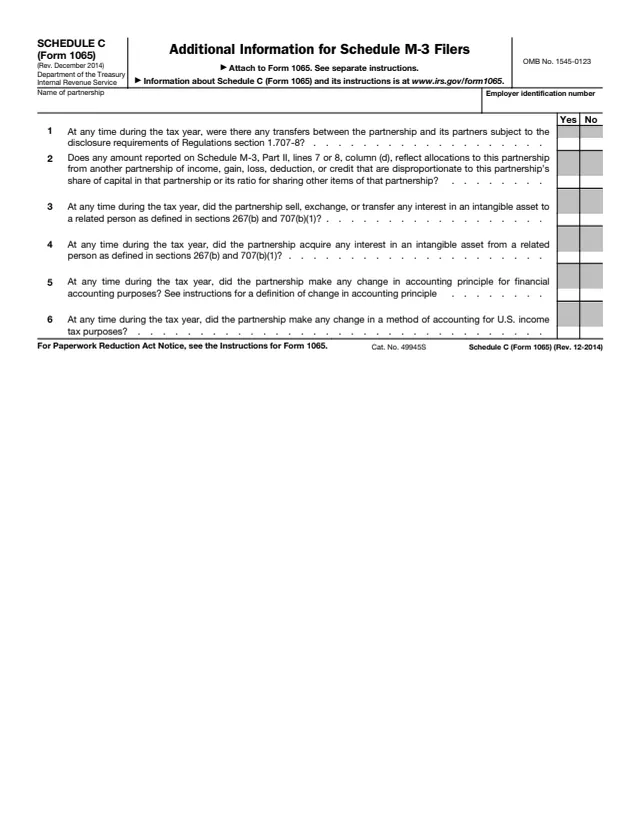
Schedule C (Form 1065), Additional Information for Schedule M-3 Filers, is a one-page schedule attached to Form 1065, U.S. Return of Partnership Income. The IRS About page says some filers of Schedule M-3 (Form 1065), Net Income (Loss) Reconciliation for Certain Partnerships, use Schedule C (Form 1065) to provide answers to additional questions.
After the partnership's name and employer identification number, the schedule asks six yes or no questions about the tax year: transfers between the partnership and its partners, disproportionate allocations from another partnership, sales or purchases of intangible assets with related persons, and changes in accounting principle or tax accounting method. The form says to see separate instructions.
The current revision is December 2014. You can fill out Schedule C free in your browser on this page and download it without an account.
The name of the partnership and its employer identification number, with Yes and No columns for the questions.
Whether there were transfers between the partnership and its partners subject to the disclosure requirements of Regulations section 1.707-8.
Whether amounts on Schedule M-3, Part II, lines 7 or 8, column (d), reflect allocations from another partnership that are disproportionate to this partnership's share of capital or sharing ratio there.
Whether the partnership sold, exchanged or transferred any interest in an intangible asset to a related person, or acquired one from a related person, as defined in sections 267(b) and 707(b)(1).
Whether the partnership made any change in accounting principle for financial accounting purposes.
Whether the partnership made any change in a method of accounting for U.S. income tax purposes.
Enter the name of the partnership and its employer identification number.
Check Yes or No for whether, at any time during the tax year, there were transfers between the partnership and its partners subject to the disclosure requirements of Regulations section 1.707-8.
Look at Schedule M-3, Part II, lines 7 and 8, column (d). Check Yes if any amount there reflects disproportionate allocations from another partnership; otherwise check No.
Check Yes or No for a sale, exchange or transfer of an intangible asset interest to a related person (line 3) and an acquisition of one from a related person (line 4), using the definitions in sections 267(b) and 707(b)(1).
Answer whether the partnership changed an accounting principle for financial accounting purposes (line 5) or a method of accounting for U.S. income tax purposes (line 6). The form says to see the instructions for the definition of change in accounting principle.
Attach the completed schedule to Form 1065.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1065, the partnership's return.
The form says to see separate instructions and that information about Schedule C (Form 1065) and its instructions is at www.irs.gov/form1065.
The form points to the Instructions for Form 1065 for the Paperwork Reduction Act Notice.
The PDF linked from the IRS About page for Form 1065 is the December 2014 revision.

1065
440 fields, 6 pages
1065 Sch. M-3
316 fields, 3 pages
1065 Sch. B-1
65 fields, 2 pages

1065
111 fields, 1 page
1065
45 fields, 1 page
The partnership completes the schedule about its own tax year and attaches it to its Form 1065, which goes to the IRS.
No tool matches that search.
The IRS About page says some filers of Schedule M-3 (Form 1065) use Schedule C to provide answers to additional questions. The form says to see separate instructions.
Six yes or no questions about the tax year: partner transfers under Regulations section 1.707-8, disproportionate allocations from another partnership, intangible assets sold to or bought from related persons, and accounting changes.
The form says to attach it to Form 1065.
The form says a related person as defined in sections 267(b) and 707(b)(1).
Yes. Line 2 asks about amounts reported on Schedule M-3, Part II, lines 7 or 8, column (d).