Boxes 1 to 6: income and rates
Income code, gross income, chapter indicator (3 or 4), chapter 3 and chapter 4 exemption codes and tax rates, withholding allowance and net income.
1042-S
Foreign Person's U.S. Source Income Subject to Withholding
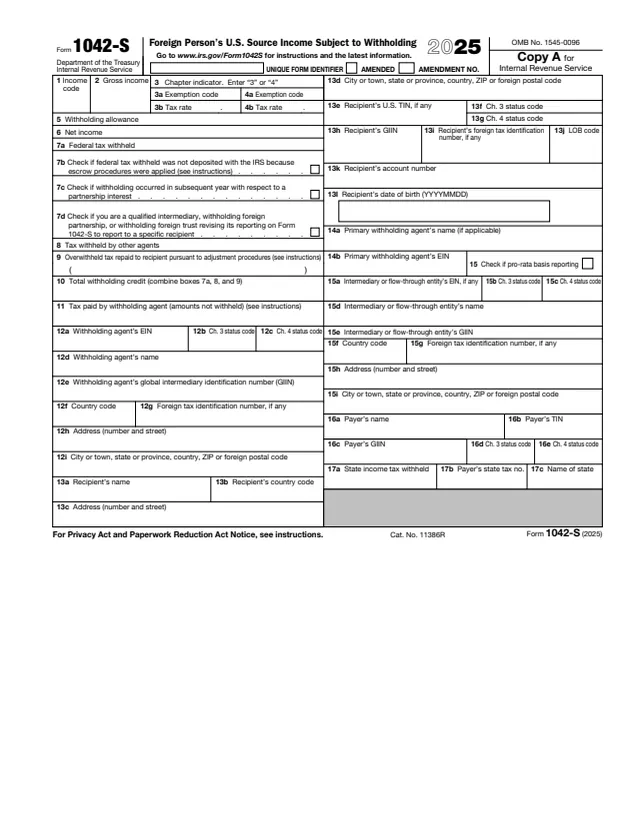
This is the 2025 edition of Form 1042-S, Foreign Person's U.S. Source Income Subject to Withholding. A withholding agent uses it to report income paid to a foreign person during 2025 and the U.S. tax withheld on it. The current instructions say either IRIS or FIRE may be used to e-file 2025 Forms 1042-S, due March 15, 2026.
The IRS page lists three uses: income and amounts withheld as described in the Instructions for Form 1042-S, specified federal procurement payments paid to foreign persons that are subject to withholding under section 5000C, and distributions of effectively connected income by a publicly traded partnership or nominee.
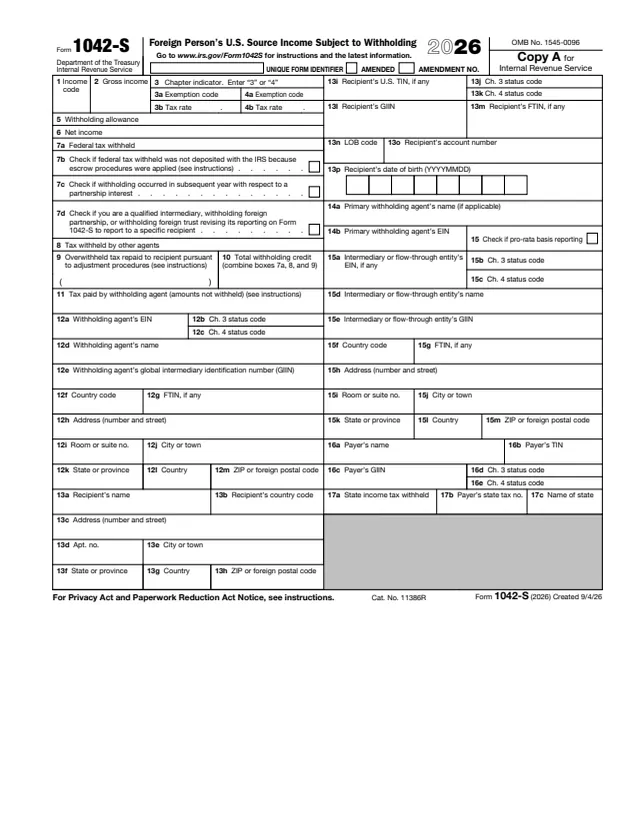
The IRS page also mentions a 2026 Form 1042-S, and the instructions now online are written for that 2026 form. The 2025 edition numbers its boxes differently: boxes 13a to 13d hold the recipient's name, country code and address, with city, state or province, country and postal code on one line. You can fill out the PDF free in your browser on this page and download it without an account.
Income code, gross income, chapter indicator (3 or 4), chapter 3 and chapter 4 exemption codes and tax rates, withholding allowance and net income.
Federal tax withheld, the checkboxes in boxes 7b to 7d, tax withheld by other agents, overwithheld tax repaid, total withholding credit (boxes 7a, 8 and 9) and tax paid by the withholding agent.
EIN, chapter 3 and chapter 4 status codes, name, GIIN, country code, foreign tax identification number and address. Box 12i holds city, state or province, country and ZIP or postal code together.
Name, country code, street address, a combined city, state or province, country and postal code line in 13d, U.S. TIN, status codes, GIIN, foreign tax identification number, LOB code, account number and date of birth.
Primary withholding agent's name and EIN, the pro-rata basis reporting box, the intermediary or flow-through entity in 15a to 15i, the payer in 16a to 16e, and state tax in 17a to 17c.
The backs of the copies list income codes, exemption codes, chapter 3 and chapter 4 status codes, pooled reporting codes and LOB codes.
The 2025 PDF has Copy A for the Internal Revenue Service and Copies B, C and D for the recipient, each with the same boxes.
Enter the unique form identifier. The instructions say it is numeric, exactly 10 digits and not the recipient's U.S. TIN or foreign TIN. An amended form repeats the original identifier and adds an amendment number.
Enter the income code, gross income in U.S. dollars, the chapter indicator, and the exemption codes and tax rates. The instructions show rates as two digits, a decimal point and two digits, for example 30.00.
Enter the tax actually withheld in box 7a, or -0- if none, then any amounts withheld by other agents or repaid. Box 10 is the total of boxes 7a, 8 and 9.
Enter the withholding agent's EIN, status codes, name, GIIN and address. On the 2025 form the city, state or province, country and postal code all go in box 12i.
Enter the recipient's name and country code, the street address in 13c and the rest of the address in 13d, then the TIN, status codes, GIIN, foreign TIN, LOB code, account number and date of birth in 13e to 13l.
The instructions online are written for the 2026 form, so match their box references to the 2025 box numbers printed on this PDF.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The current instructions say 2025 Forms 1042-S are due March 15, 2026. Forms are filed with the IRS and furnished to the recipient by March 15 of the year after the payments.
The current instructions say either IRIS or FIRE may be used to e-file 2025 Forms 1042-S, and that IRIS can be used for them beginning January 1, 2026.
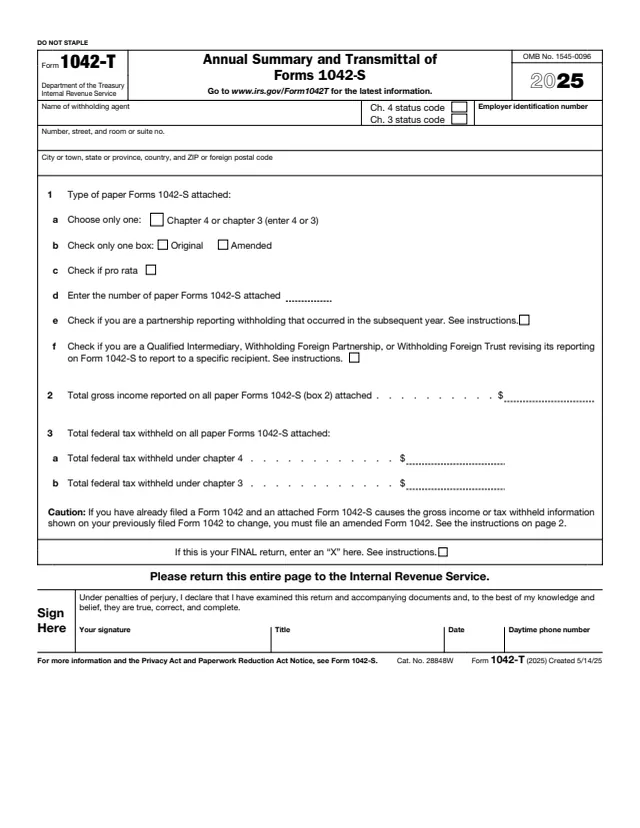
The instructions say Copy A is filed with the IRS, and paper Forms 1042-S are sent with Form 1042-T, Annual Summary and Transmittal of Forms 1042-S.
The 2025 form labels Copy B for the recipient's records, Copy C to attach to any Federal tax return the recipient files, and Copy D to attach to any state tax return.
The instructions name Form 8809 for more time to file Forms 1042-S and Form 15397 for a one-time 30-day extension to furnish recipient copies.
1042-S
300 fields, 7 pages
1042
134 fields, 2 pages
1042-T
19 fields, 2 pages
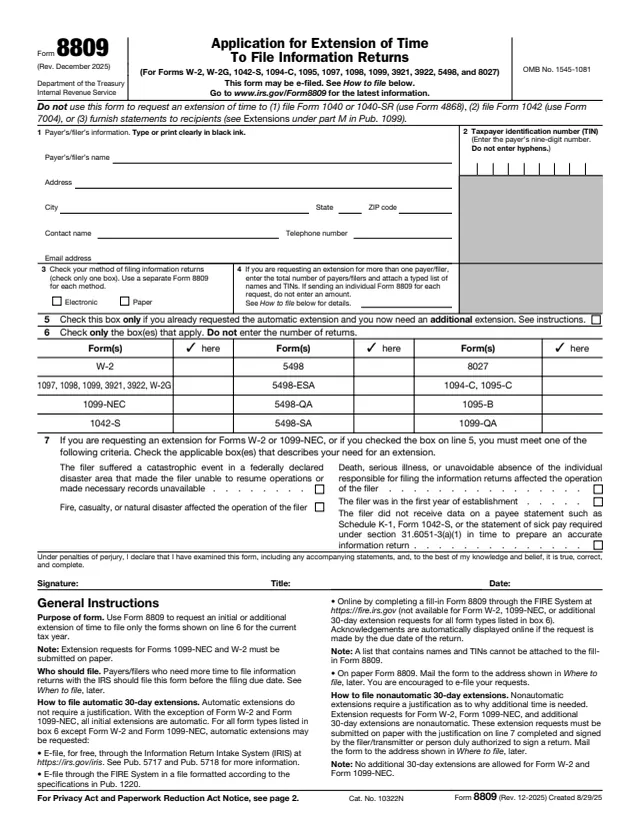
8809
32 fields, 2 pages
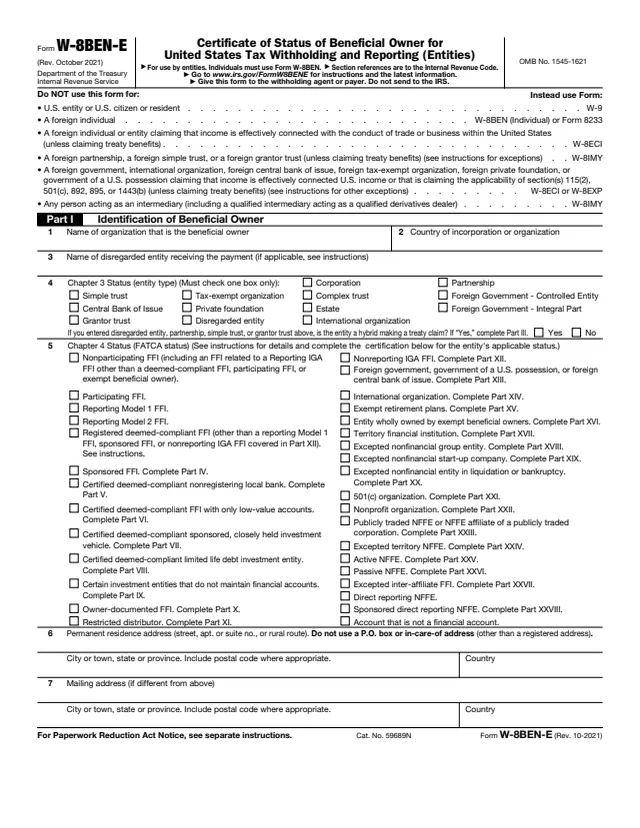
W-8BEN-E
179 fields, 8 pages
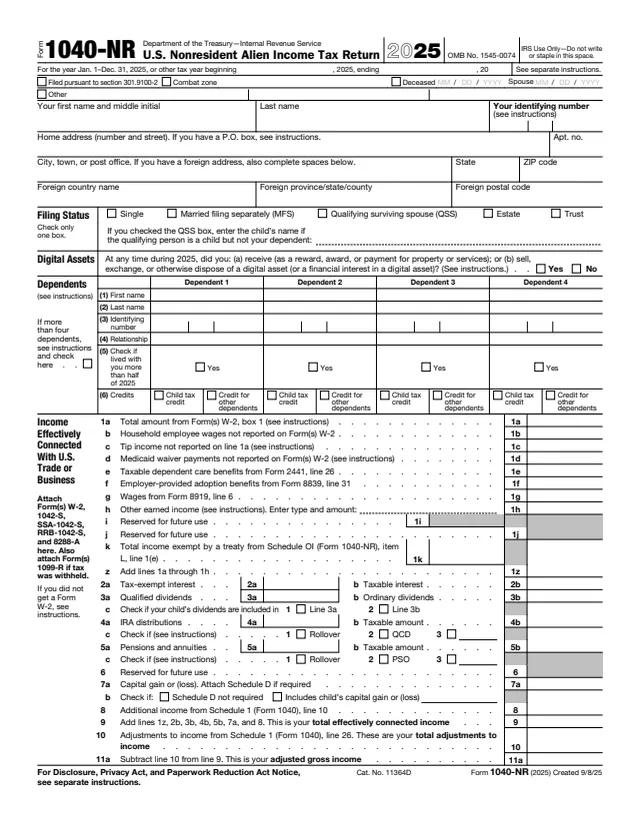
1040-NR
171 fields, 2 pages
A withholding agent completes the form for amounts paid in 2025. The foreign person or entity paid gets the recipient copies.
No tool matches that search.
It is the 2025 Form 1042-S, for amounts paid during 2025. The IRS page also mentions a 2026 Form 1042-S for later payments.
The current instructions say 2025 Forms 1042-S are due March 15, 2026.
The instructions online are written for the 2026 form, which separates the address fields into individual boxes. The 2025 form combines city, state or province, country and postal code in boxes 12i, 13d and 15i.
The 2025 form labels Copy B for the recipient's records, Copy C to attach to any Federal tax return the recipient files, and Copy D to attach to any state tax return.
The withholding agent that paid the income. The foreign person or entity that received it gets Copies B, C and D.