Payer and winner
Payer's name, address, TIN and telephone number, and the winner's name, address and TIN in box 9, which the instructions call required information.
W-2G
Certain Gambling Winnings
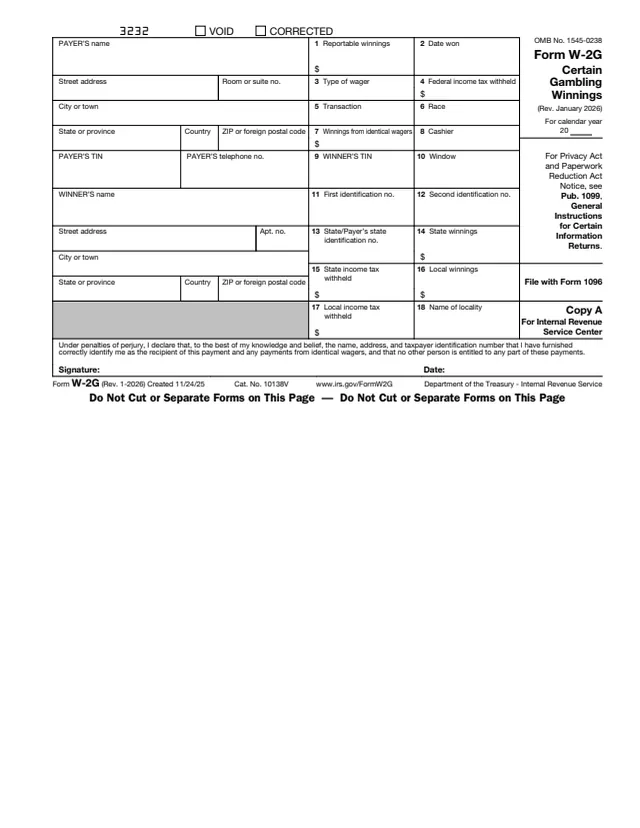
Form W-2G, Certain Gambling Winnings, is an information return. The IRS About page says it is filed to report gambling winnings and any federal income tax withheld on those winnings, and that the requirements for reporting and withholding depend on the type of gambling, the amount of the winnings and generally the ratio of the winnings to the wager.
The payer of the winnings completes and files it, not the winner. The instructions say to file Form W-2G with the IRS and provide a statement to the winner, Copies B and C. They cover five types of gambling: horse racing, dog racing, jai alai and other wagering transactions; sweepstakes, wagering pools and lotteries; bingo, keno and slot machines; poker tournaments; and sports wagering.
The instructions say Form W-2G is now a continuous-use form, updated as needed. This page has the January 2026 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
Payer's name, address, TIN and telephone number, and the winner's name, address and TIN in box 9, which the instructions call required information.
Reportable winnings, date won, type of wager and federal income tax withheld.
Transaction, race, winnings from identical wagers, cashier, and window. Which of these apply depends on the type of gambling.
First and second identification numbers, taken from two forms of identification presented by the person receiving the winnings.
State and local information: payer's state ID, state winnings, state tax withheld, local winnings, local tax withheld and name of locality. The instructions say these need not be completed for the IRS.
A signature under penalties of perjury, and Copies A, 1, B, C, 2 and D for the IRS, a state or local tax department, the winner and the payer.
Enter the payer's name, address, TIN and phone, then the winner's name, address and TIN. The instructions say backup withholding applies if the winner fails to give a TIN, and Form W-9 may be used to request it.
Enter the reportable winnings and the date of the winning event or transaction. For races and sporting events, the instructions say this is not the date the money was paid if it was paid later.
Enter the type of wager, such as a Daily Double, a lottery name and price, bingo, keno or slot machines, or "poker tournament." Then fill in the identifying boxes that apply to that type of gambling.
Enter federal income tax withheld, regular gambling withholding or backup withholding. The instructions give 24% for both, and 31.58% for certain noncash payments when the payer pays the withholding tax.
Enter numbers from two forms of identification, such as a driver's license, passport or completed and unmodified Form W-9. For most types the instructions say one must include a photograph; state lottery winnings are an exception.
The form says the winner signs it if they are the only person entitled to the winnings and the winnings are subject to regular gambling withholding, and returns it to the payer, who gives the winner their copies.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Copy A is for the Internal Revenue Service Center and is filed with Form 1096. The form says filing and furnishing instructions, including due dates and extension requests, are in Pub. 1099.
The instructions say a statement goes to the winner, and Copies B and C may be furnished. Copy B says to attach it to the winner's federal return if box 4 shows tax withheld. Copy 2 is for a state, city or local return.
If a state tax department requires a paper copy, the instructions say to use Copy 1. Copy D is for the payer.
The instructions say the payer reports the amount withheld in box 4 and files Form 945, Annual Return of Withheld Federal Income Tax, to report all gambling withholding and backup withholding.
The form lists the Technical Services Operation (TSO) at 866-455-7438 toll free or 304-263-8700 (not toll free) for questions about reporting on Form W-2G.
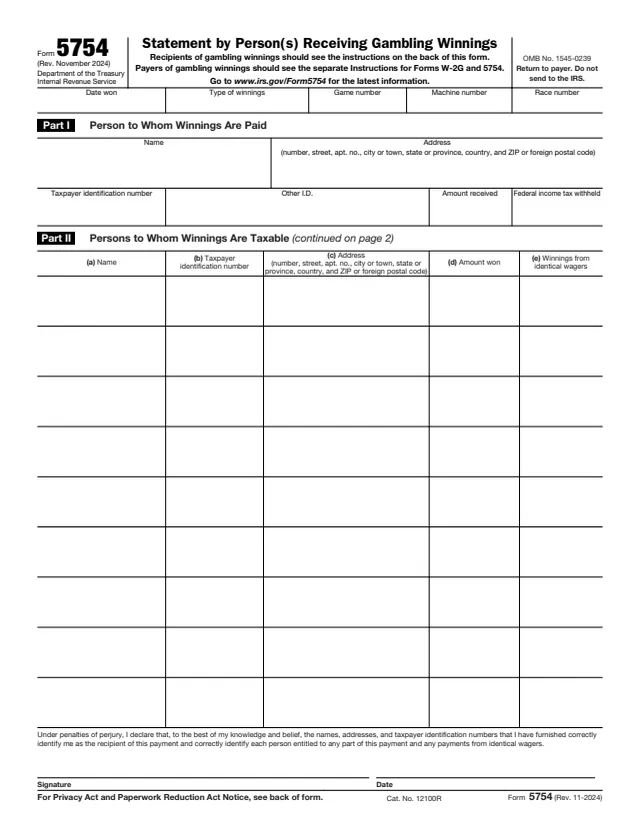
5754
76 fields, 2 pages
1096
55 fields, 3 pages
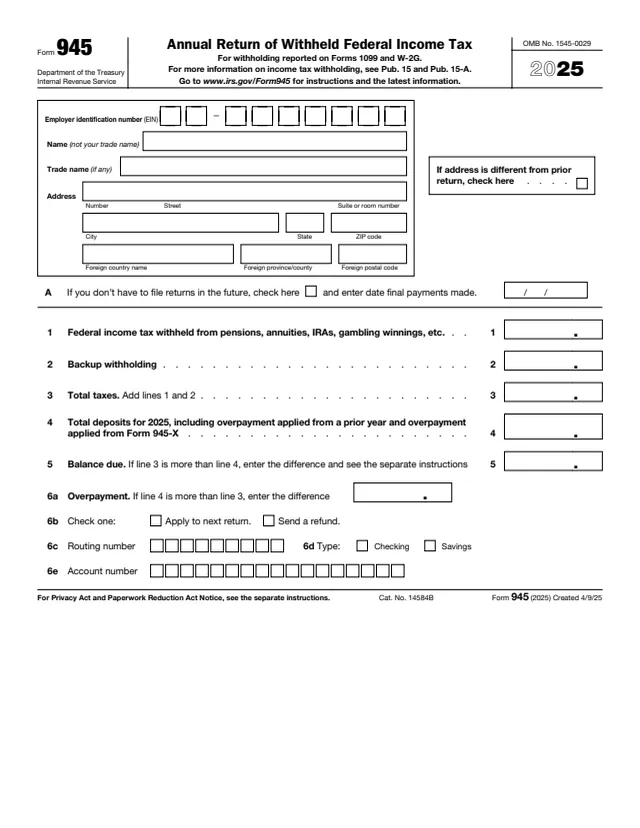
945
88 fields, 3 pages
1042-S
300 fields, 7 pages
W-9
23 fields, 6 pages
1040
73 fields, 2 pages
The payer of gambling winnings prepares and files Form W-2G. The winner receives Copies B, C and 2 and signs the form in some cases.
No tool matches that search.
The payer of the gambling winnings. The instructions say to file Form W-2G with the IRS and provide a statement to the winner, Copies B and C of the form.
The form says the winner signs if they are the only person entitled to the winnings and the winnings are subject to regular gambling withholding, then returns the signed form to the payer.
The instructions give 24% for regular gambling withholding, 31.58% for certain noncash payments when the payer pays the tax, and 24% for backup withholding.
The person receiving the winnings gives Form 5754 to the payer, who uses it to prepare a Form W-2G for each person listed as a winner.
No. The instructions say winnings paid to a nonresident alien individual or a foreign entity are not reported on Form W-2G, and the form says to use Form 1042-S.
The form's instructions to the winner say gambling winnings are generally reported under the "Other income" line of Schedule 1 (Form 1040), and box 4 is included on Form 1040 or 1040-SR as federal income tax withheld.
The form says filing and furnishing instructions, including due dates and extension requests, are in Pub. 1099, General Instructions for Certain Information Returns.