Page 1: firm and worker
Names, mailing addresses, phone and fax numbers, the firm's EIN, and the worker's social security number, plus the name, address, and TIN of whoever paid the worker if that was someone else.
SS-8
Determination of Worker Status for Purposes of Federal Employment Taxes and Income Tax Withholding
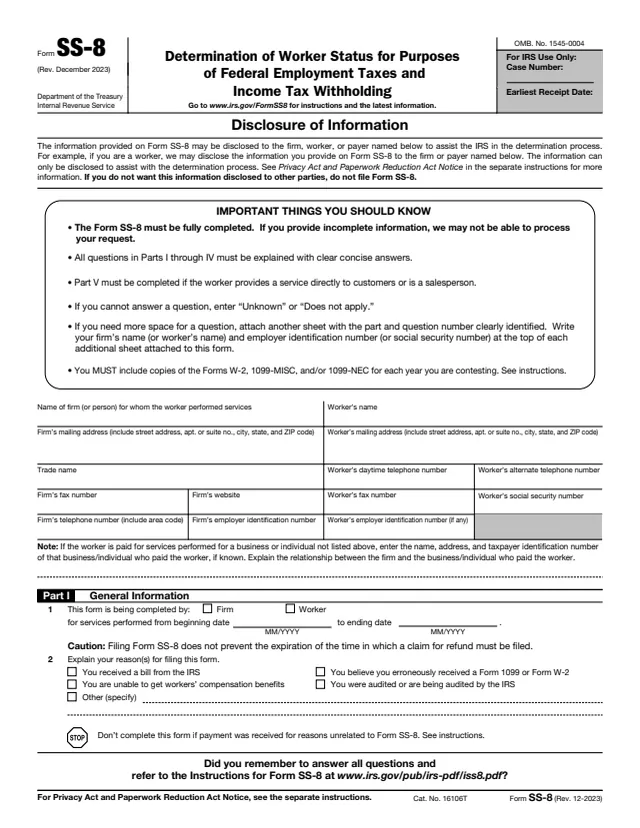
Form SS-8 is how a firm or a worker asks the IRS to determine the status of a worker under the common law rules for purposes of federal employment taxes and income tax withholding. The IRS About page says filing it means asking the IRS to establish whether the services provided to the firm are those of an employee or an independent contractor.
Page 1 holds the firm's and the worker's details and Part I, General Information. Part II covers Behavioral Control, Part III Financial Control, Part IV the Relationship of the Worker and Firm, and Part V applies to service providers and salespersons. The instructions say there is no fee for requesting a determination letter.
The form warns that the information on it may be disclosed to the firm, worker, or payer named on it to assist the determination. You can fill out Form SS-8 free in your browser on this page and download it without an account.
Names, mailing addresses, phone and fax numbers, the firm's EIN, and the worker's social security number, plus the name, address, and TIN of whoever paid the worker if that was someone else.
Who is completing the form and for what dates, the reason for filing, how the job was obtained, supporting documents, the firm's business, the job title and duties, and any written or oral agreement.
Training and instruction, who gives assignments and decides how they are done, reports, how often and where services are performed, meetings, and whether the worker can hire substitutes or helpers.
Supplies and equipment, leases, expenses and reimbursements, type of pay, advance pay, whom the customer pays, workers' compensation insurance, financial risk, and who sets the rate of pay and product prices.
Benefits, ending the relationship, work for others, agreements prohibiting competition, advertising, assembling products at home, how the worker is introduced to customers, and how the relationship ended.
Part V asks service providers and salespersons about customer leads, sales terms, territory, and products. The form is then signed under penalties of perjury.
Check Firm or Worker and enter the beginning and ending dates of service. The instructions say to give all the years services were provided, and that a determination can only be made for years with open statutes.
Check the reason for filing, such as a bill from the IRS, a Form 1099 or Form W-2 believed to be issued in error, being unable to get workers' compensation benefits, or an IRS audit.
Attach copies of the Forms 1099-MISC, 1099-NEC, and W-2 for all years in question. Without them, the instructions say to send a letter with a breakdown of earnings by year and copies of checks, paystubs, or bank statements.
The instructions say the IRS cannot make a determination unless all questions in Parts I through IV are completed. Enter Unknown or Does not apply where needed, and label any extra sheet with the part and question number and the name and EIN or SSN.
Complete Part V if the worker provided a service directly to customers, for example dry cleaning, massage therapy, or grocery delivery, or is a salesperson who sells to individuals or businesses.
The taxpayer signs and dates the form. The instructions say a stamped signature or a power of attorney representative's signature is not accepted, and an officer with personal knowledge of the facts signs for a corporation.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions give the address: Internal Revenue Service, Form SS-8 Determinations, P.O. Box 630, Stop 631, Holtsville, NY 11742-0630.
The instructions say the completed and signed form and attachments can be faxed to the IRS at 855-242-4481.
The instructions say not to submit Form SS-8 with a tax return, as that delays processing, and not to delay filing a return or responding to a request for payment while waiting for a determination.
The instructions say there is no fee for requesting a Form SS-8 determination letter.
The form says filing it does not prevent the expiration of the time in which a claim for refund must be filed. The instructions describe a protective claim on Form 1040-X with Protective Claim written at the top.
Information on the form may be shared with the other parties named on page 1. The form says that if you do not want it disclosed, do not file Form SS-8.
The About page says firms and workers file Form SS-8. Part I, line 1, asks whether the form is being completed by the firm or by the worker.
No tool matches that search.
The instructions say a technician reviews the facts and applies the law. The IRS generally issues a formal determination to the firm or payer and sends a copy to the worker.
The instructions say a determination letter applies only to the worker or class of workers requesting it and is binding on the IRS if the facts or law don't change. An information letter is advisory only.
No. The instructions say it is not a claim for refund of social security and Medicare taxes or federal income tax withholding.
No. The instructions say neither the determination process nor the review of records is an examination of any federal tax return, so examination appeal rights don't apply.
The instructions say the requester can identify facts from the original submission that were not fully considered, or submit additional information and ask the office to reconsider.
Yes. The instructions say to complete the form for one worker in the class and list the names, addresses, and SSNs, if available, of all workers potentially affected.