Header
The EIN, name, trade name and address, the calendar year of the return being corrected, and the date errors were discovered.
945-X
Adjusted Annual Return of Withheld Federal Income Tax or Claim for Refund
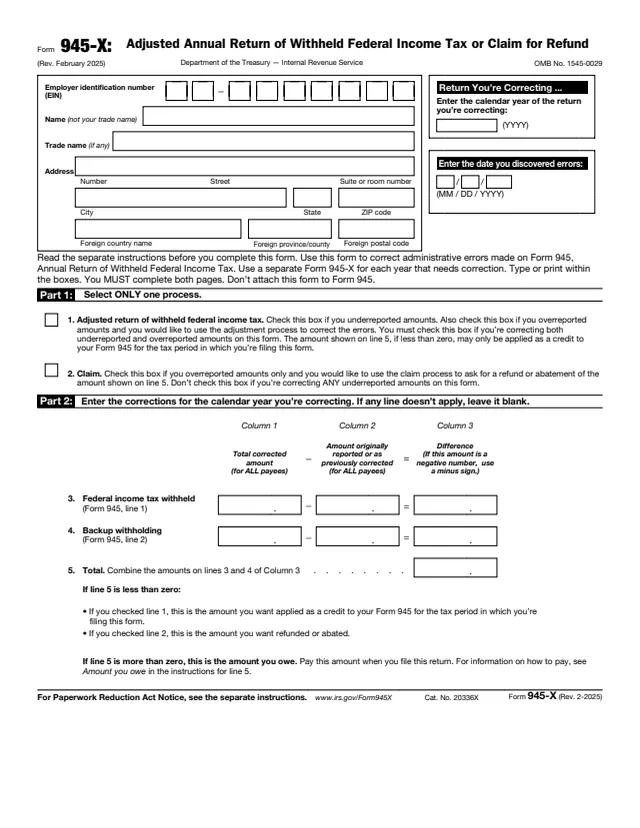
Form 945-X is used to correct administrative errors only on a previously filed Form 945, Annual Return of Withheld Federal Income Tax. The IRS says an administrative error occurs if the federal income tax (including backup withholding) reported on Form 945 is not the amount actually withheld from payees, for example because of a mathematical or transposition error.
The form works two ways. The adjustment process corrects underreported amounts, or applies an overreported amount as a credit on Form 945. The claim process asks for a refund or abatement of overreported amounts only. One Form 945-X covers one calendar year, and the form says not to attach it to Form 945.
This page has the February 2025 revision. You can fill out the PDF free in your browser on this page and download it without an account.
The EIN, name, trade name and address, the calendar year of the return being corrected, and the date errors were discovered.
Line 1 is the adjusted return of withheld federal income tax. Line 2 is the claim for a refund or abatement. The form says to select only one.
Line 3 corrects federal income tax withheld (Form 945, line 1) and line 4 corrects backup withholding (Form 945, line 2), each in three columns. Line 5 totals column 3.
Line 6 is checked when a correction includes both underreported and overreported amounts. Line 7 holds the detailed explanation of how the corrections were determined.
The signature, printed name and title, date and daytime phone, plus the Paid Preparer Use Only section.
Enter the EIN, name and address, the calendar year of the Form 945 being corrected and the date errors were discovered. The instructions say to enter the earliest date when errors were found at different times.
Check line 1 for underreported amounts, or for overreported amounts to be credited on Form 945. Check line 2 to claim a refund or abatement of overreported amounts only. The form says not to check line 2 when correcting any underreported amount.
Enter the total corrected amount for all payees in column 1, the amount originally reported or as previously corrected in column 2, and the difference in column 3. The instructions say to use a minus sign for a negative difference.
Combine column 3 of lines 3 and 4. The form says a positive amount is owed and paid when the return is filed. A negative amount is a credit on Form 945 under line 1, or the refund or abatement claimed under line 2.
Check line 6 if a correction mixes underreported and overreported amounts. On line 7, the instructions ask for the line numbers affected, the date the error was found, the amount and the cause of each error.
The form says to complete both pages and sign it. Enter the name, EIN and the calendar year being corrected at the top of page 2 as well.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 945-X when an administrative error on a previously filed Form 945 is discovered. For underreported tax, the due date is that of the return for the period in which the error was discovered (January 31 of the following year).
The instructions say overreported tax can generally be corrected within 3 years of the date Form 945 was filed or 2 years from the date the tax was paid, whichever is later. In the last 90 days of that period, only the claim process applies.
The instructions list a mailing address in Cincinnati, OH or Ogden, UT by state, a P.O. box in Ogden for filers with no legal residence or principal place of business in any state, and a separate address for private delivery services.
The instructions list EFTPS, IRS Direct Pay, credit or debit card, or a check or money order payable to "United States Treasury" with the EIN, "Form 945-X" and the year corrected written on it.
The form says not to attach Form 945-X to Form 945. Interest and penalties already assessed are requested back on Form 843, not on Form 945-X.
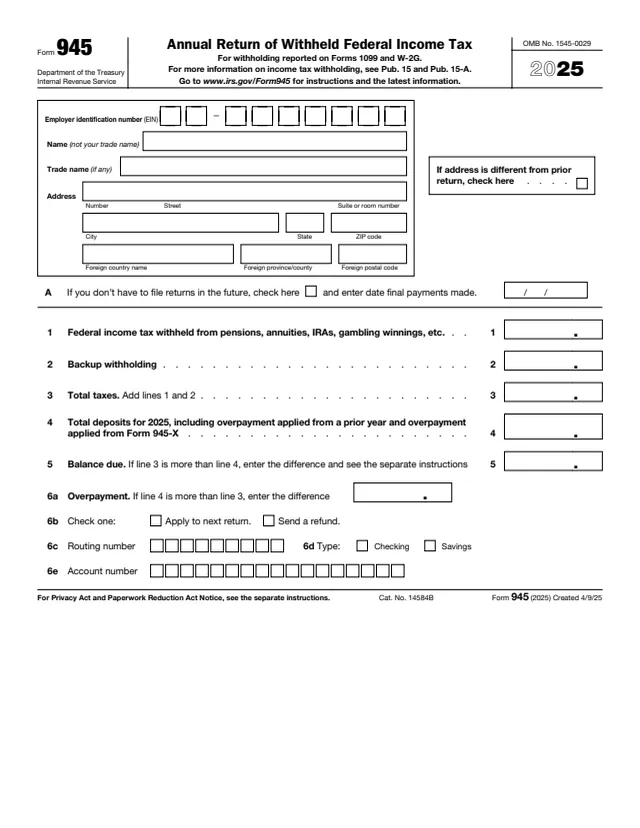
945
88 fields, 3 pages
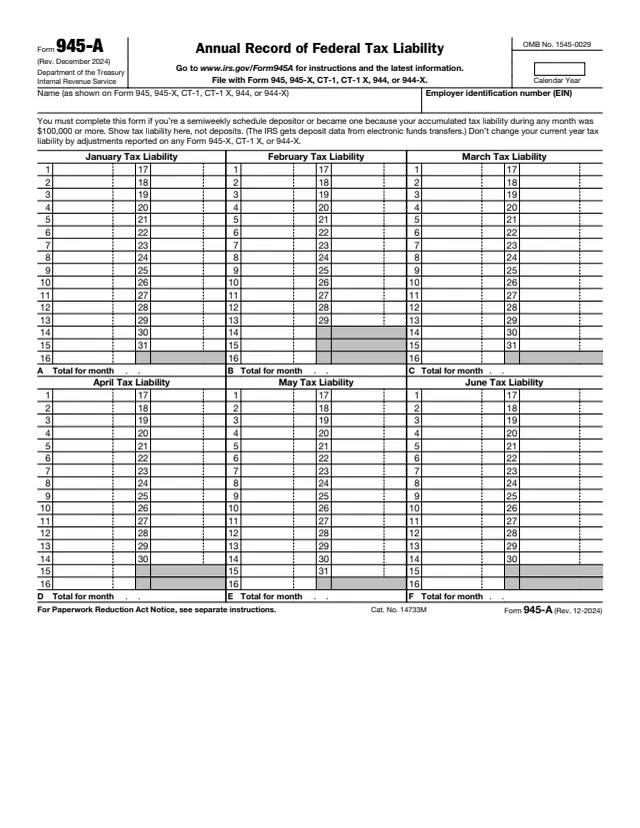
945-A
748 fields, 2 pages
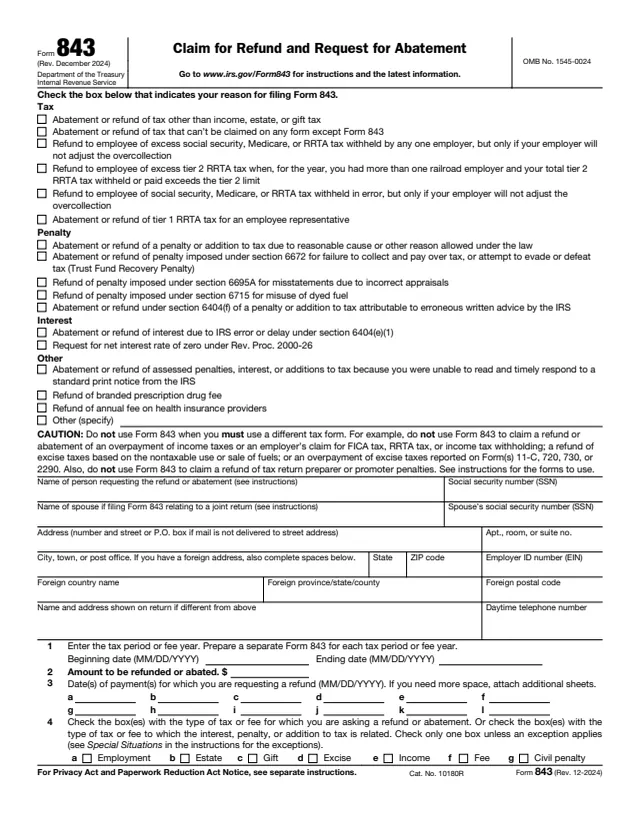
843
85 fields, 2 pages
941-X
352 fields, 6 pages
944-X
332 fields, 6 pages
943-X
321 fields, 6 pages
Form 945-X is filed by the business or other payer that filed the Form 945 being corrected, under its employer identification number. It is not filed by the payees whose tax was withheld.
No tool matches that search.
The IRS says it occurs if the federal income tax (including backup withholding) reported on Form 945 is not the amount actually withheld from payees, such as a mathematical or transposition error.
The instructions give an example of a payer that failed to withhold from a new payee in a prior year and say Form 945-X can't be filed for it, because the amount reported matched what was actually withheld.
Line 1 is the adjustment process, for underreported amounts or a credit applied to Form 945. Line 2 is the claim process, for a refund or abatement of overreported amounts only. The form says to select only one.
No. The form says not to attach it to Form 945, and the instructions say to generally file it separately.
No. The form says to use a separate Form 945-X for each year that needs correction.
The instructions list the IRS Business and Specialty Tax Line at 800-829-4933, or 800-829-4059 for TDD/TTY.