Header
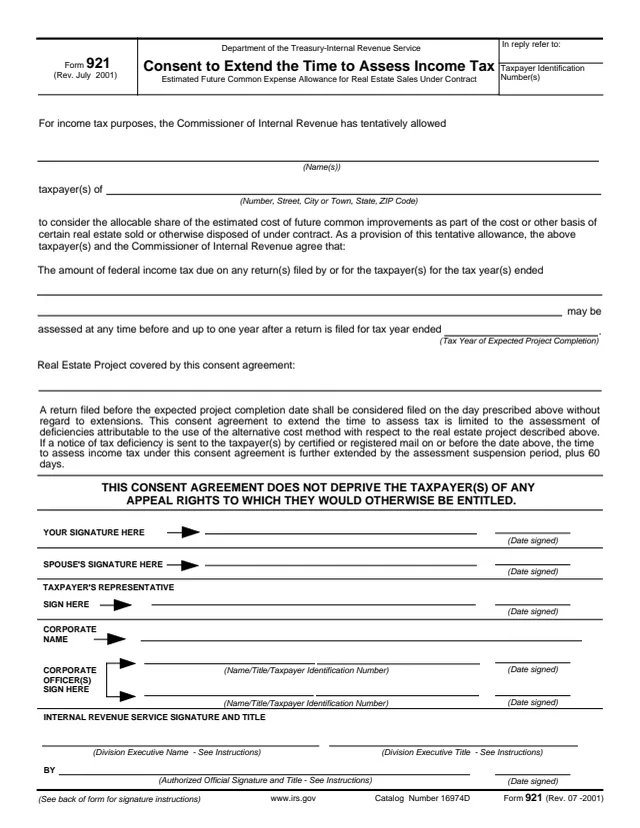
The title and subtitle, an "In reply refer to" box and the Taxpayer Identification Number.
921-A
Consent Fixing Period of Limitation on Assessment of Income and Profits Tax
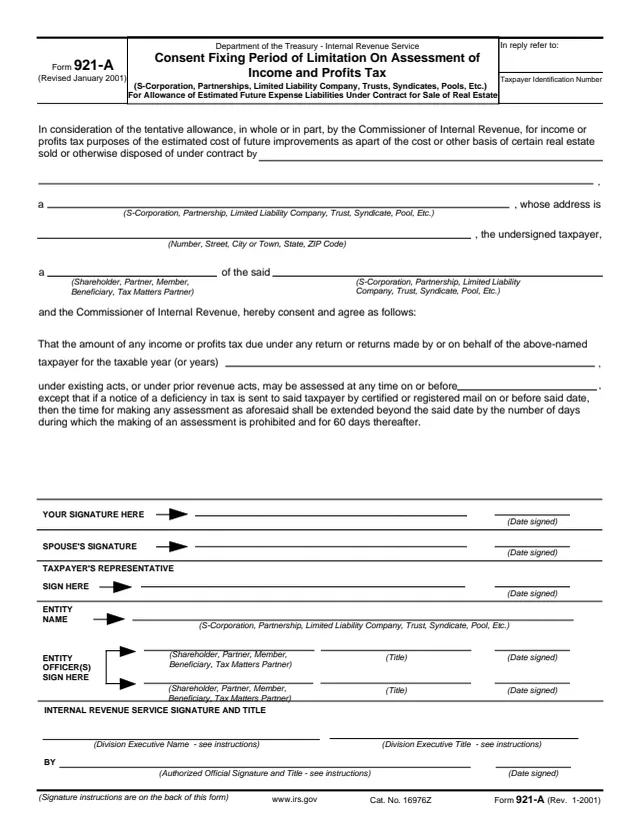
Form 921-A is a consent agreement between a taxpayer and the Commissioner of Internal Revenue. Its subtitle names the entities it is for (S-Corporation, Partnerships, Limited Liability Company, Trusts, Syndicates, Pools, Etc.) and says it is for the allowance of estimated future expense liabilities under a contract for sale of real estate.
The form says the consent is given in consideration of the tentative allowance of the estimated cost of future improvements as part of the cost or other basis of real estate the entity sold or otherwise disposed of under contract. The undersigned taxpayer, a shareholder, partner, member, beneficiary or tax matters partner of that entity, agrees that income or profits tax for the taxable years listed may be assessed at any time on or before a date written on the form. If a notice of deficiency is sent by certified or registered mail on or before that date, the time is extended by the days an assessment is prohibited and for 60 days after.
The back page holds signature instructions for taxpayers and for IRS employees. You can fill out the PDF free in your browser on this page and download it without an account.
The title and subtitle, an "In reply refer to" box and the Taxpayer Identification Number.
Blanks for the entity that sold or disposed of real estate under contract, its type and address, and the undersigned taxpayer's role in it.
Blanks for the taxable year or years covered and the date on or before which tax may be assessed, with the 60 day extension after a notice of deficiency.
Lines for the taxpayer, the spouse and the taxpayer's representative, then the entity name and two entity officer lines, each with the date signed.
The division executive's name and title and the authorized official's signature, then a back page of instructions for taxpayers and for IRS employees.
Enter the Taxpayer Identification Number. The "In reply refer to" box is also at the top.
Enter the name of the entity that sold the real estate, its type (S-Corporation, Partnership, Limited Liability Company, Trust, Syndicate, Pool, Etc.) and its address, then the taxpayer's role, such as shareholder, partner or member.
Enter the taxable year or years covered and the date on or before which tax may be assessed.
The taxpayer signs and dates. The instructions say both spouses sign for a joint return year, and a representative signs only with a power of attorney that specifically allows it.
Enter the entity name. Each officer signs with role and title and dates the line. The instructions say a corporate seal is not necessary.
The instructions for IRS employees say to enter the division executive's name and title for their division. The appropriate authorized official within the division signs and dates the line.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Tax for the listed years may be assessed on or before the date entered. After a notice of deficiency sent by certified or registered mail, the time extends by the days assessment is prohibited and for 60 days after.
If an attorney or agent signs, the instructions say a power of attorney not filed before has to accompany the form.
The instructions say a seal is not necessary. The seal space is for corporations whose charter or the law where they are incorporated requires one.
The IRS employee instructions cover Small Business/Self-Employed, Wage and Investment, Large and Mid-Size Business, Tax Exempt and Government Entities, and Appeals.
The form prints no mailing address or due date.
The form is an agreement, so it has several signers: the taxpayer, others on the taxpayer's side, and an IRS official. It is not a form an individual files on their own.
No tool matches that search.
A consent between a taxpayer and the Commissioner of Internal Revenue that fixes the period for assessing income or profits tax, tied to the allowance of estimated future expenses under a contract for sale of real estate.
Its subtitle lists S-Corporation, Partnerships, Limited Liability Company, Trusts, Syndicates, Pools, Etc.
A shareholder, partner, member, beneficiary or tax matters partner of the entity named on the form.
The instructions say both sign for a year with a joint return, unless one, acting under a power of attorney, signs as agent for the other.
The instructions say yes, when a power of attorney specifically allows it. One not filed before has to accompany the form.
The form says if it is sent by certified or registered mail on or before the agreed date, the time for assessment is extended by the days assessment is prohibited and for 60 days after.