Elections
Checkboxes at the top of Part I for the section 6013(g) election, the section 6013(h) election and the Regulations section 1.1411-10(g) election.
8960
Net Investment Income Tax—Individuals, Estates, and Trusts
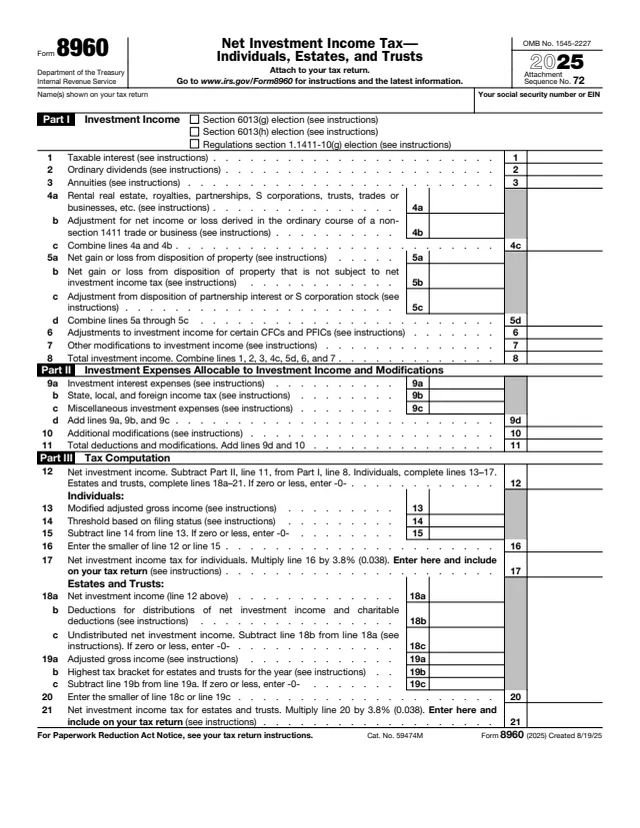
Form 8960 is used to figure the Net Investment Income Tax (NIIT). The About page says taxpayers use it to figure the amount of their NIIT, and the form title names individuals, estates and trusts. This page covers the 2025 form.
The instructions say to attach Form 8960 to your return if your modified adjusted gross income (MAGI) is greater than the applicable threshold amount. For individuals the threshold is based on filing status: $250,000 for married filing jointly or qualifying surviving spouse, $125,000 for married filing separately, and $200,000 for single or head of household. Estates and trusts use the dollar amount at which the highest tax bracket for estates and trusts begins.
The form adds up investment income in Part I, subtracts allocable expenses in Part II, and figures the tax at 3.8% in Part III. You can fill out Form 8960 free in your browser on this page and download the result without an account.
Checkboxes at the top of Part I for the section 6013(g) election, the section 6013(h) election and the Regulations section 1.1411-10(g) election.
Taxable interest, ordinary dividends and annuities.
Rental real estate, royalties, partnerships, S corporations, trusts and trades or businesses, gains and losses from property, adjustments for certain CFCs and PFICs, other modifications, and total investment income on line 8.
Lines 9a to 11 for investment interest expenses, state, local and foreign income tax, miscellaneous investment expenses and additional modifications.
Line 12 is net investment income. Lines 13 to 17 compare MAGI to the filing status threshold and figure the tax at 3.8%.
Lines 18a to 21 for undistributed net investment income, adjusted gross income, the highest tax bracket amount and the tax at 3.8%.
Enter the name shown on your tax return and your SSN or EIN. Check an election box only if it applies. The instructions say a section 1.1411-10(g) election also needs a statement attached to the return.
Enter taxable interest from Form 1040 or 1040-SR line 2b (Form 1041, line 1), ordinary dividends from line 3b (Form 1041, line 2a), and gross income from annuities other than the qualified plans and IRAs the instructions list.
Enter line 4a from Schedule 1 (Form 1040), lines 3, 5 and 6 (Form 1041, lines 3, 5 and 6), adjust on line 4b, report gains and losses on lines 5a to 5d, enter any adjustments on lines 6 and 7, and combine them on line 8.
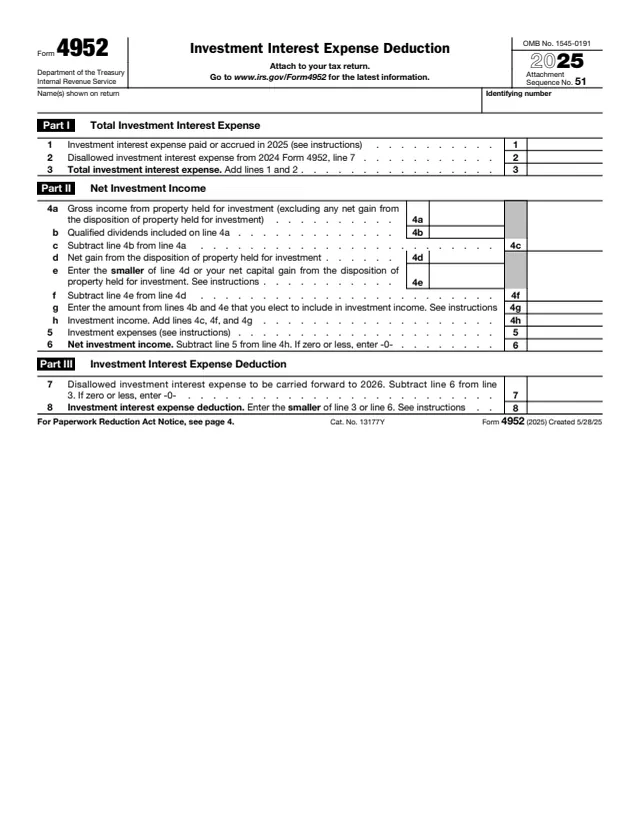
Enter investment interest expense (Schedule A (Form 1040), line 9, or Form 4952, line 8 for estates and trusts), state, local and foreign taxes allocable to net investment income, other investment expenses and modifications, then total them.
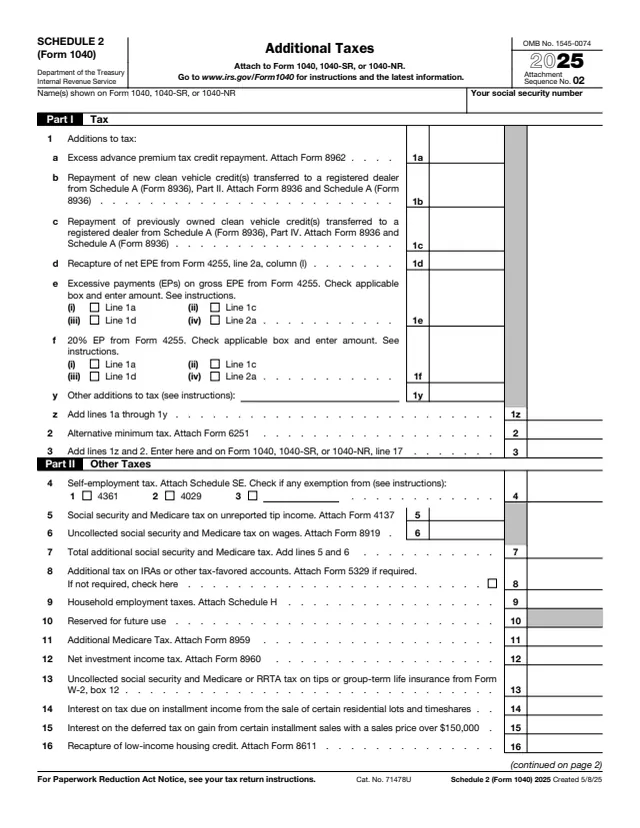
Subtract line 11 from line 8. Enter MAGI, which the instructions say is generally your AGI from Form 1040 or 1040-SR, and the threshold. Multiply the smaller of line 12 or line 15 by 3.8%. The instructions say line 17 goes on Schedule 2 (Form 1040), line 12.
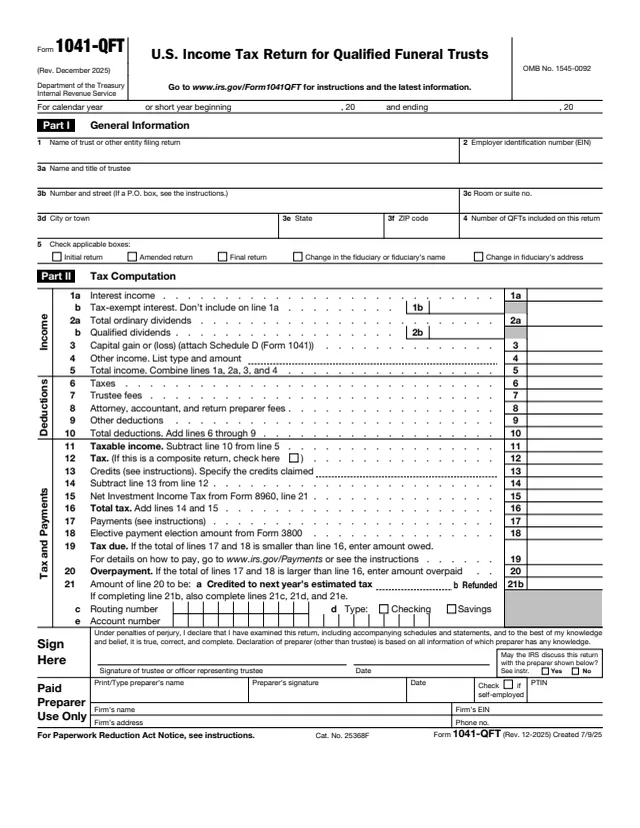
Reduce net investment income by distributions and charitable deductions, enter AGI and the highest bracket amount from the Form 1041 instructions, and multiply the smaller amount by 3.8%. Line 21 goes on Form 1041, Schedule G, line 5 or Form 1041-QFT, line 15.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. It carries Attachment Sequence No. 72.
The instructions give examples of excluded items: wages, unemployment compensation, Alaska Permanent Fund Dividends, alimony, social security benefits, tax-exempt interest, income from certain qualified retirement plan distributions and income subject to self-employment taxes.
The instructions say income from transactions involving digital assets may be subject to the tax on net investment income.
The instructions say Form 1040-NR filers include line 17 on their U.S. residency statement and see the Instructions for Form 1040-NR for the amount to report.
The instructions say to keep all records and worksheets for the items on Form 8960, and to keep records for the entire life of an investment to show how basis was figured.
1040
63 fields, 2 pages

1041
173 fields, 3 pages
1041-QFT
59 fields, 1 page
4952
17 fields, 4 pages

1040
199 fields, 2 pages
1040-NR
171 fields, 2 pages
The instructions say to attach Form 8960 to your return if your MAGI is greater than the applicable threshold amount. Individuals, estates and trusts each have their own lines in Part III.
No tool matches that search.
The form figures it at 3.8% (0.038) on line 17 for individuals and line 21 for estates and trusts.
The instructions list $250,000 for married filing jointly or qualifying surviving spouse, $125,000 for married filing separately, and $200,000 for single or head of household.
The instructions say it is the dollar amount at which the highest tax bracket for estates and trusts begins for the year, as shown in the instructions for Form 1041, Schedule G, line 1a, and Form 1041-QFT, line 12.
No. The instructions list wages, social security benefits and income subject to self-employment taxes among the examples of excluded items.
The instructions say the NIIT does not apply to nonresident alien individuals.
The instructions say Form 1040 or 1040-SR filers include line 17 on Schedule 2 (Form 1040), line 12. Form 1041 filers include line 21 on Schedule G, line 5, and Form 1041-QFT filers on line 15.