Lines 1 and 2: expenditures
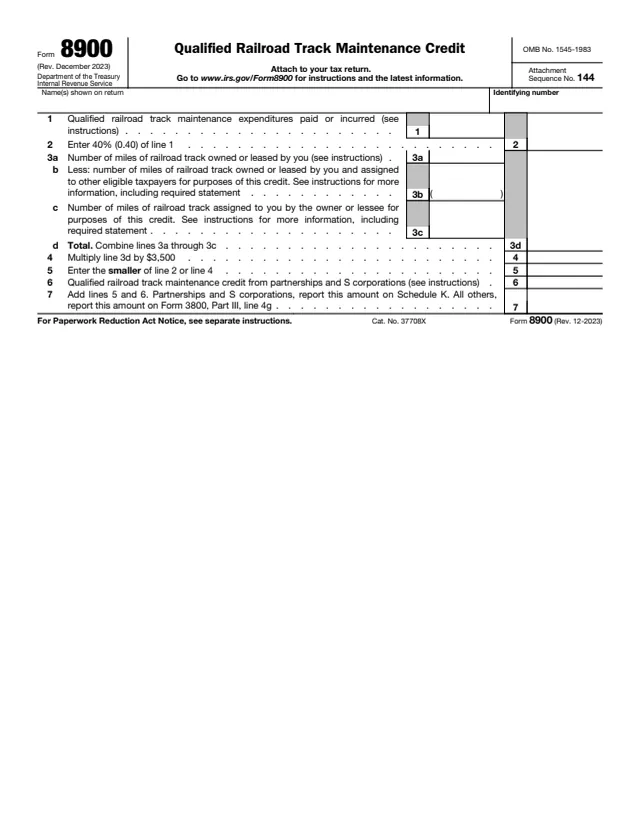
Line 1 is the qualified railroad track maintenance expenditures paid or incurred. Line 2 is 40% (0.40) of line 1.
8900
Qualified Railroad Track Maintenance Credit
Form 8900 is used to claim the railroad track maintenance credit (RTMC) for qualified railroad track maintenance expenditures (QRTME) paid or incurred during the tax year. The instructions say an assignor of miles of eligible railroad track files Form 8900 even if it does not claim any RTMC.
The instructions say to use the December 2023 revision for tax years beginning in 2023 or later, until a later revision is issued. That revision reflects a credit rate of 40%, reduced from 50% for tax years beginning after 2022, and the credit was extended to cover QRTME paid or incurred in all tax years beginning after 2022.
The credit on line 5 is the smaller of 40% of QRTME or $3,500 per mile of railroad track. You can fill out Form 8900 free in your browser on this page and download it without an account.
Line 1 is the qualified railroad track maintenance expenditures paid or incurred. Line 2 is 40% (0.40) of line 1.
Miles of railroad track owned or leased (3a), less miles assigned to other eligible taxpayers (3b), plus miles assigned to you by the owner or lessee (3c), combined on line 3d.
Line 3d multiplied by $3,500.
The smaller of line 2 or line 4.
Line 6 is the credit from partnerships and S corporations. Line 7 adds lines 5 and 6 and goes to Schedule K for partnerships and S corporations, or to Form 3800, Part III, line 4g for all others.
Enter QRTME paid or incurred during the tax year. The instructions say a payment by an assignee to a Class II or Class III railroad for an assignment of track miles is treated as QRTME paid or incurred by the assignee, not the assignor.
A Class II or Class III railroad enters the eligible railroad track miles it owns or leases. The instructions say 1 mile of single track is 1 mile, but 1 mile of double track is 2 miles.
The railroad enters miles assigned to other eligible taxpayers. Each mile can be assigned only once during the tax year, and an attached statement gives each assignee's name and taxpayer identification number and the miles assigned.
An assignee enters miles assigned to it, with an attached statement of the total miles and an attestation that it keeps each assignor's details in writing. The instructions say the assignee cannot reassign miles.
Multiply line 3d by $3,500, then enter the smaller of line 2 or line 4. A member of a controlled group enters its share on line 5, attaches a statement, and writes "See Attached" next to line 5.
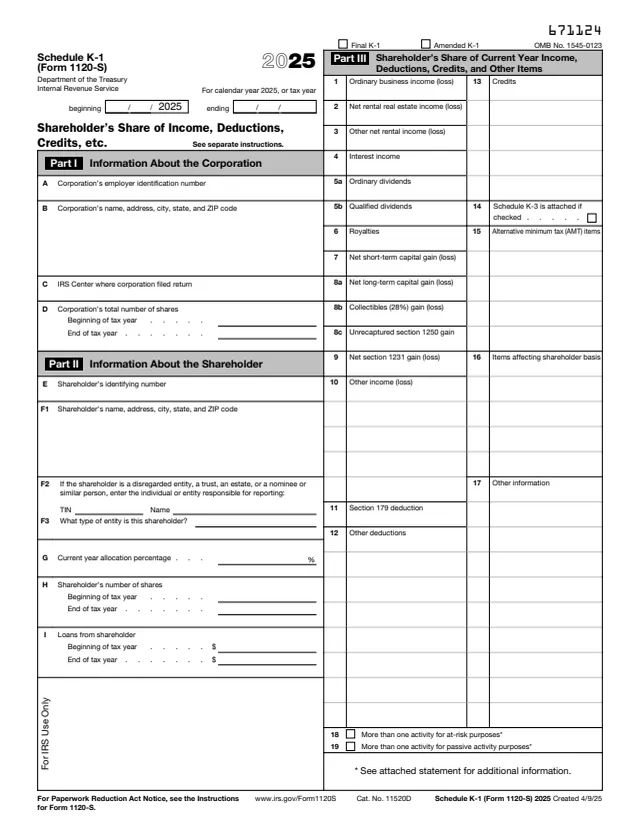
Enter credits from Schedule K-1 (Form 1065), box 15 (code AJ) and Schedule K-1 (Form 1120-S), box 13 (code AJ) on line 6, then add lines 5 and 6 on line 7.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. Its attachment sequence number is 144.
Partnerships and S corporations report it on Schedule K. All others report it on Form 3800, Part III, line 4g.
The instructions say to use the amount of RTMC to reduce the basis of a qualifying railroad structure asset or intangible asset, limited to the QRTME capitalized for the asset.
The instructions say all members of a controlled group of corporations or a group of businesses under common control are treated as a single taxpayer, and each member's credit is proportionate to its share of the group's QRTME.
The instructions say to use the December 2023 revision for tax years beginning in 2023 or later, until a later revision is issued, and prior revisions for earlier tax years.

3800
1,921 fields, 9 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages

1065
111 fields, 1 page
1120-S
114 fields, 1 page
The instructions say eligible taxpayers use the form to claim the credit. They are businesses tied to Class II or Class III railroads, as these terms are defined by the Surface Transportation Board.
No tool matches that search.
The instructions say the rate on line 2 is 40% for tax years beginning after 2022, reduced from 50%.
Yes. Line 4 multiplies the miles on line 3d by $3,500, and line 5 takes the smaller of line 2 or line 4.
The instructions say an assignor of miles of eligible railroad track files Form 8900 even if it does not claim any RTMC, with the statement described for line 3b.
The instructions say they are not required to if their only source for this credit is a partnership or S corporation. They can report it on Form 3800, Part III, line 4g.
The instructions list six: BNSF, Canadian National, Canadian Pacific Kansas City, CSX, Norfolk Southern and Union Pacific.
Yes. The instructions say 1 mile of single track is 1 mile, but 1 mile of double track is 2 miles.