Part I, lines 1 to 4
The taxable REIT subsidiary making the election: its name, address, employer identification number (EIN), date incorporated or organized, and state or country of incorporation or organization.
8875
Taxable REIT Subsidiary Election
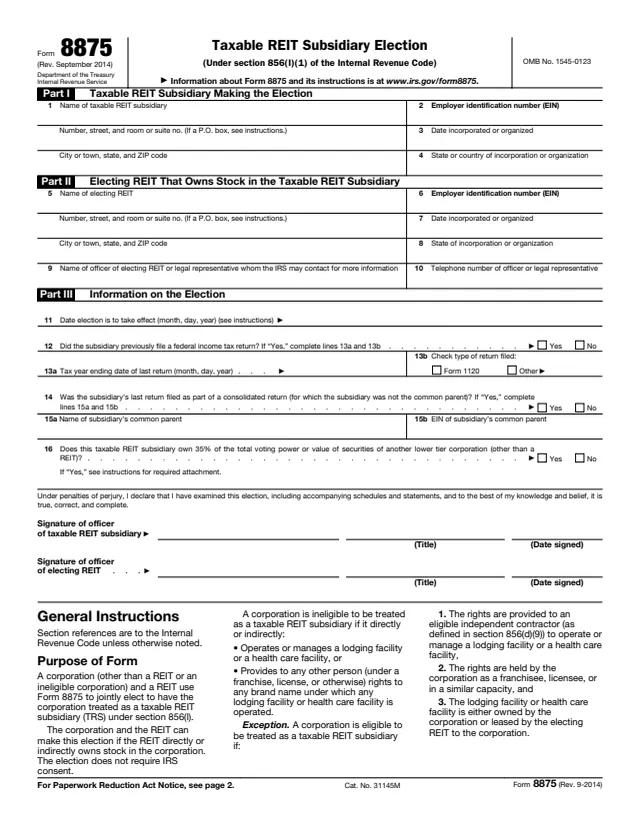
Form 8875 is the Taxable REIT Subsidiary Election under section 856(l) of the Internal Revenue Code. The instructions say a corporation (other than a REIT or an ineligible corporation) and a REIT use it to jointly elect to have the corporation treated as a taxable REIT subsidiary (TRS). The corporation and the REIT can make the election if the REIT directly or indirectly owns stock in the corporation, and the election does not require IRS consent.
The form is completed and signed by both entities: Part I describes the subsidiary, Part II describes the electing REIT, and Part III gives the effective date and details about earlier returns and lower tier corporations. The instructions are printed on the form itself, on pages 1 and 2.
You can fill out Form 8875 free in your browser on this page and download it without an account.
The taxable REIT subsidiary making the election: its name, address, employer identification number (EIN), date incorporated or organized, and state or country of incorporation or organization.
The electing REIT that owns stock in the subsidiary: its name, address, EIN, date incorporated or organized, and state of incorporation or organization.
The name and telephone number of an officer of the electing REIT, or a legal representative, whom the IRS may contact for more information.
The date the election is to take effect, whether the subsidiary filed a federal income tax return before, the tax year end and type of its last return, and the common parent if that return was part of a consolidated return.
Asks whether the TRS owns 35% of the total voting power or value of securities of another lower tier corporation (other than a REIT). A Yes answer needs an attached statement.
A penalties of perjury declaration, then the signature, title and date for an officer of the taxable REIT subsidiary and an officer of the electing REIT.
Include the suite, room or other unit number after the street address. Use a P.O. box only if the Post Office does not deliver to the street address. If the REIT shares the TRS's address, the instructions say to enter "Same as corporation" in Part II.
Enter each entity's EIN. The instructions say a TRS without an EIN applies for one online or with Form SS-4, and enters "Applied for" if the EIN has not arrived by the time the return is due.
The instructions say the date cannot be more than 2 months and 15 days before the filing date or more than 12 months after it. A date outside that window is moved to the nearest limit. With no date, the election is effective on the date Form 8875 is filed.
Answer Yes or No on line 12. If Yes, give the tax year ending date of the last return and check Form 1120 or Other. On line 14, if the last return was part of a consolidated return, give the common parent's name and EIN.
If the TRS owns 35% of the total voting power or value of another corporation's securities (other than a REIT), the instructions say to attach a statement with that corporation's name and EIN.
An officer of the taxable REIT subsidiary and an officer of the electing REIT each sign, enter their title and date the form.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 8875 with the Department of the Treasury, Internal Revenue Service, Ogden, UT 84201, and not to attach it to the corporation's or REIT's tax returns.
The instructions say the election can be made at any time during the tax year, but the effective date depends on when Form 8875 is filed. See line 11.
The election is irrevocable unless both the corporation and the REIT consent. They jointly file a new Form 8875 with REVOCATION written across the top, complete Parts I and II and both sign. It is effective on the date filed.
If the TRS later acquires securities that bring it to 35% or more of another corporation, the instructions say to file a copy marked "Automatic Taxable REIT Subsidiary" within 30 days of the end of the REIT's tax year quarter in which that happened.
If the TRS's EIN changes because of a change in status, such as a merger, the election ends automatically and a new one is made with the new EIN. A new address or responsible party is reported on Form 8822-B.

1120
481 fields, 6 pages
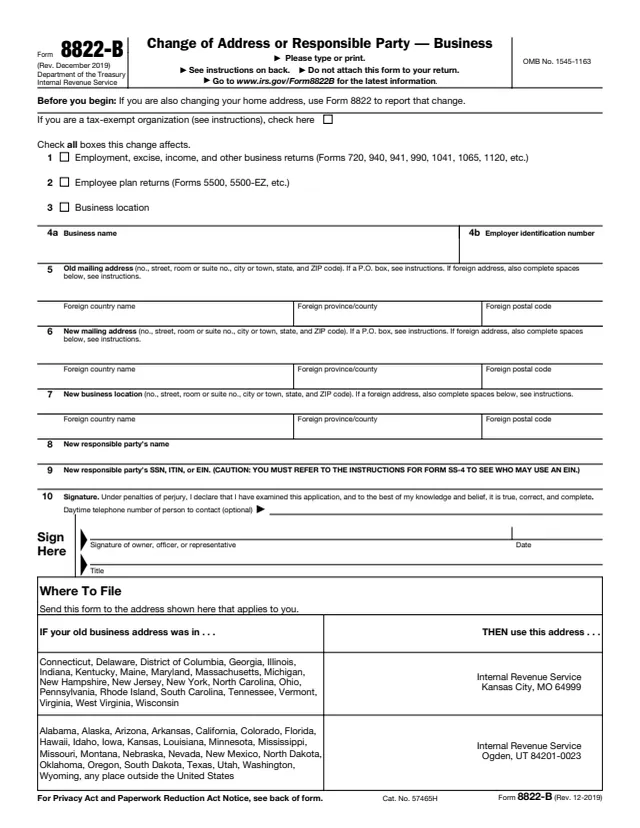
8822-B
22 fields, 2 pages
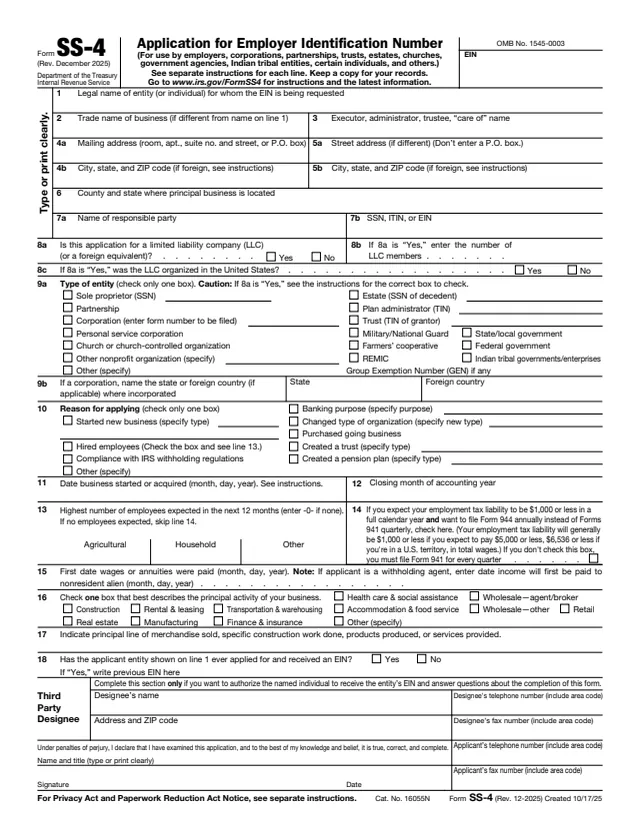
SS-4
89 fields, 2 pages
8869
31 fields, 1 page
8832
70 fields, 8 pages
Form 8875 is a business election made jointly by a corporation and a REIT that owns stock in it. It is not filed by individuals.
No tool matches that search.
The instructions say a corporation and a REIT use it to jointly elect to have the corporation treated as a taxable REIT subsidiary under section 856(l).
No. The instructions say the election does not require IRS consent. A revocation filed jointly by both parties also does not require IRS consent.
The instructions give Department of the Treasury, Internal Revenue Service, Ogden, UT 84201. It is not attached to either entity's tax return.
On the date entered on line 11, within the limits of 2 months and 15 days before filing and 12 months after filing. If no date is given, it is effective on the date the form is filed.
Only if both the corporation and the REIT consent. They jointly file a new Form 8875 with REVOCATION across the top, Parts I and II completed and both signatures.
The instructions say each electing REIT seeking to treat the corporation as a taxable REIT subsidiary files a separate Form 8875.