Line 1: tips received
Tips received by employees for services on which the employer paid or incurred employer social security and Medicare taxes during the tax year.
8846
Credit for Employer Social Security and Medicare Taxes Paid on Certain Employee Tips
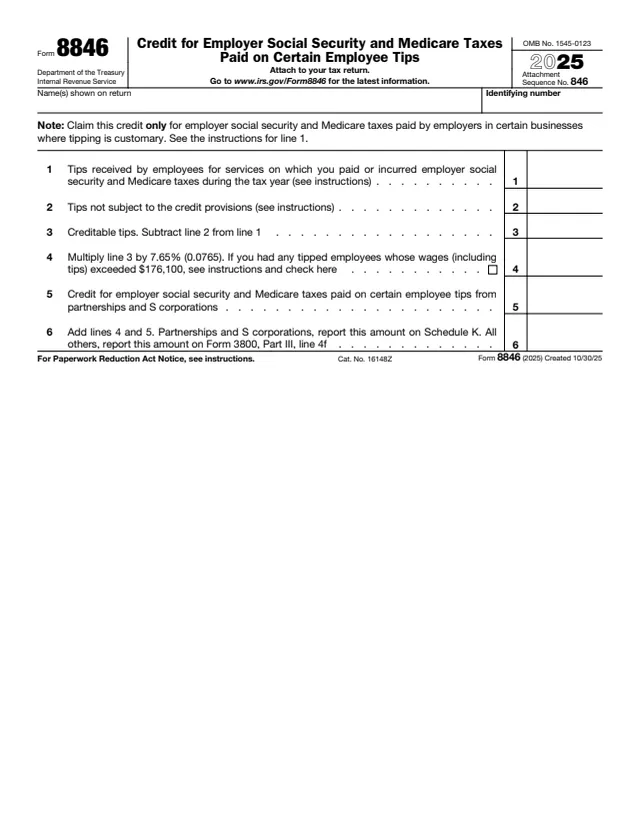
Form 8846 is used by certain employers to claim a credit for social security and Medicare taxes paid or incurred by the employer on certain employees' tips. The instructions printed with the form say the credit is part of the general business credit, and that for tax years beginning after 2024 it was extended to certain beauty service businesses, in addition to food or beverage businesses.
The form has six lines: tips on which employer taxes were paid, tips not subject to the credit, creditable tips, the credit at 7.65%, credit passed through from partnerships and S corporations, and the total. The total goes on Schedule K for partnerships and S corporations, and on Form 3800, Part III, line 4f for all others.
The instructions say the credit can be claimed, or an election made not to claim it, any time within 3 years from the due date of the return, on the original or an amended return. This page covers the 2025 form. You can fill out Form 8846 free in your browser on this page and download it without an account.
Tips received by employees for services on which the employer paid or incurred employer social security and Medicare taxes during the tax year.
Tips used to meet the hourly rates in the instructions: $5.15 an hour for food or beverage employees and $7.25 an hour for beauty service employees.
Line 3 subtracts line 2 from line 1. Line 4 multiplies line 3 by 7.65% (0.0765), with a box to check if any tipped employee's wages (including tips) exceeded $176,100.
Credit for employer social security and Medicare taxes paid on certain employee tips from partnerships and S corporations.
Lines 4 and 5 added. The form says partnerships and S corporations report it on Schedule K, and all others on Form 3800, Part III, line 4f.
Enter the tips received by employees for services on which employer social security and Medicare taxes were paid or incurred during the tax year, for the food or beverage and beauty services the instructions describe.
For each employee and month, figure the wages payable at $5.15 or $7.25 an hour minus the wages (excluding tips) actually paid, and enter the total. If wages already meet that rate, the instructions say to enter zero.
Subtract line 2 from line 1. The instructions give an example where $450 of tips is reduced by $140, leaving $310 taken into account for that month.
Multiply line 3 by 7.65% (0.0765). If any tipped employee's wages and tips exceeded the 2025 social security wage base of $176,100, check the box and attach a computation using 0.0145 for tips subject only to Medicare tax.
Enter any credit from partnerships and S corporations on line 5, add lines 4 and 5 on line 6, and carry the total to Schedule K or to Form 3800, Part III, line 4f.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the tax return. It has attachment sequence number 846.
The instructions say the credit can be claimed, or an election made not to claim it, any time within 3 years from the due date of the return, on the original or an amended return.
The instructions say the income tax deduction for employer social security and Medicare taxes is reduced by the amount on line 4.
For an employee whose wages and tips paid in 2026 exceeded the 2026 social security wage base of $184,500 by the end of the 2025 fiscal year, the instructions apply the same line 4 method.
For the difference between tips and service charges, the instructions point to Revenue Ruling 2012-18.
The form is filed by a business that employs tipped workers and is attached to the business's own tax return. The employees who receive the tips do not file it.
No tool matches that search.
The instructions describe employers whose employees received customary tips for food or beverage service, or, for tax years beginning after 2024, for barbering, hair care, nail care, esthetics, or body and spa treatment services.
Line 4 multiplies creditable tips by 7.65% (0.0765). For tips above the 2025 social security wage base of $176,100, the instructions use 0.0145 for the part subject only to Medicare tax.
The instructions say they are not required to complete or file it if their only source for the credit is a partnership or S corporation. They report it directly on Form 3800, Part III, line 4f.
Tips used to meet the minimum wage figures in the instructions: $5.15 an hour, the rate in effect on January 1, 2007, for food or beverage employers, and $7.25 an hour for beauty service employers.
No. The instructions say the 0.9% Additional Medicare Tax is imposed only on the employee, with no employer share, so it has no effect on the credit.
The instructions say any time within 3 years from the due date of the return, on the original return or an amended return.


