Type of filer
Two boxes: REMIC, or issuer of collateralized debt obligation (CDO).
8811
Information Return for Real Estate Mortgage Investment Conduits (REMICs) and Issuers of Collateralized Debt Obligations
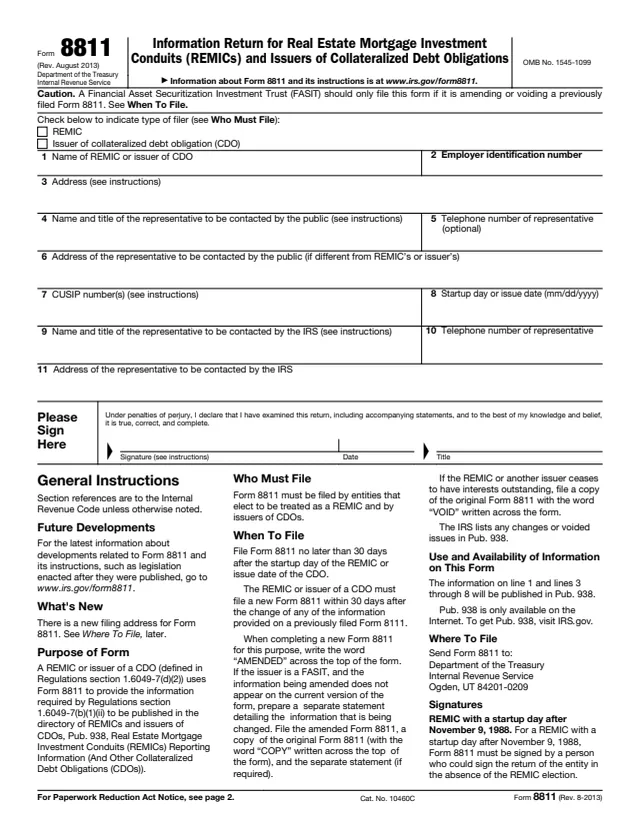
Form 8811, Information Return for Real Estate Mortgage Investment Conduits (REMICs) and Issuers of Collateralized Debt Obligations, is filed by entity issuers, not by individual investors. The IRS About page says REMICs and issuers of collateralized debt obligations (CDO) use this form to provide information required by Regulations section 1.6049-7(b)(1)(ii).
The form says that information is published in the directory of REMICs and issuers of CDOs, Pub. 938, Real Estate Mortgage Investment Conduits (REMICs) Reporting Information (And Other Collateralized Debt Obligations (CDOs)). Lines 1 and 3 through 8 appear in Pub. 938. Lines 9 through 11 name the representative the IRS may contact, and that information does not appear in Pub. 938.
This page hosts the August 2013 revision, and the instructions are printed on the form. You can fill out Form 8811 free in your browser on this page and download the result without an account.
Two boxes: REMIC, or issuer of collateralized debt obligation (CDO).
The name of the REMIC or issuer of the CDO, its employer identification number and its address.
The name and title of the representative to be contacted by the public, an optional telephone number, and an address if different from the issuer's.
The CUSIP number(s), and the startup day or issue date in mm/dd/yyyy format.
The name, title, telephone number and address of the representative to be contacted by the IRS.
A declaration under penalties of perjury, with the signature, date and title.
Check the REMIC box or the issuer of CDO box.
The instructions say to enter the number, street, room or suite number (or P.O. box number), city or town, state and ZIP code. A website address is allowed only if it goes directly to a page with all of that address information.
Enter the official or representative designated to give holders the information needed to figure the interest and original issue discount (OID) they report. The instructions say not to complete line 6 if it would repeat the line 3 address.
Enter the Committee on Uniform Security Identification Procedure (CUSIP) number assigned to each class of REMIC regular interest or to each CDO.
Enter the startup day or issue date. The instructions say the startup day is the day the REMIC issued all of its regular and residual interests, and when a sponsor contributes property over any period of 10 consecutive days, the REMIC may designate any one of those days. For non-REMIC debt, the issue date is defined in section 1275(a)(2).
Enter the official the IRS may contact with questions about the form, then sign. The instructions say a REMIC that is a corporation or trust is signed by a corporate officer or a trustee, respectively.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to file no later than 30 days after the startup day of the REMIC or the issue date of the CDO.
The form says to send it to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0209. The What's New section notes this is a new filing address.
The form says a new Form 8811 is filed within 30 days after any of the information changes, with the word AMENDED written across the top.
If the information being amended is not on the current form, the instructions say to file the amended form, a copy of the original marked COPY across the top, and a separate statement detailing the change.
If the REMIC or other issuer ceases to have interests outstanding, the form says to file a copy of the original Form 8811 with the word VOID written across it. The IRS lists changes and voided issues in Pub. 938.
The form estimates 3 hr., 6 min. for recordkeeping, 35 min. for learning about the law or the form, and 40 min. for preparing, copying, assembling and sending it.
1099-OID
111 fields, 7 pages
1099-INT
127 fields, 7 pages
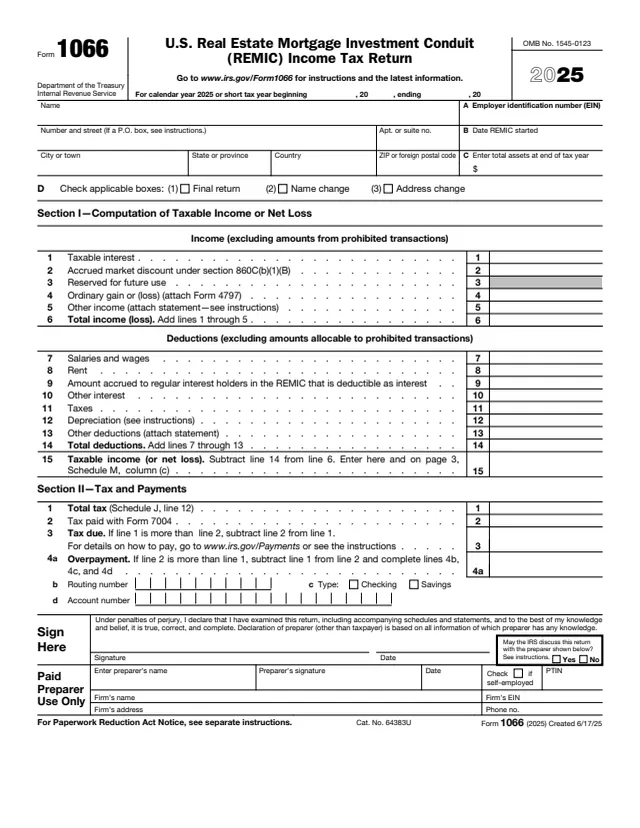
1066
123 fields, 4 pages
1066 Sch. Q
35 fields, 2 pages
The form says it is filed by entities that elect to be treated as a REMIC and by issuers of CDOs. The filer checks one box at the top to show which type it is.
No tool matches that search.
The form says entities that elect to be treated as a REMIC and issuers of CDOs file it. It is not a form individual investors file.
The form says the information on line 1 and lines 3 through 8 will be published in Pub. 938. The IRS contact on lines 9 to 11 will not appear there.
The form says no later than 30 days after the startup day of the REMIC or the issue date of the CDO. A new form is filed within 30 days after any information changes.
The form lists Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0209.
The form says that if the REMIC or other issuer ceases to have interests outstanding, a copy of the original Form 8811 is filed with the word VOID written across the form.
The form cautions that a FASIT should only file it if it is amending or voiding a previously filed Form 8811.