Establishment and employer
Name, address and employer identification number of the establishment, the amended or final return boxes, the employer's name and address, and a five-digit establishment number.
8027
Employer's Annual Information Return of Tip Income and Allocated Tips
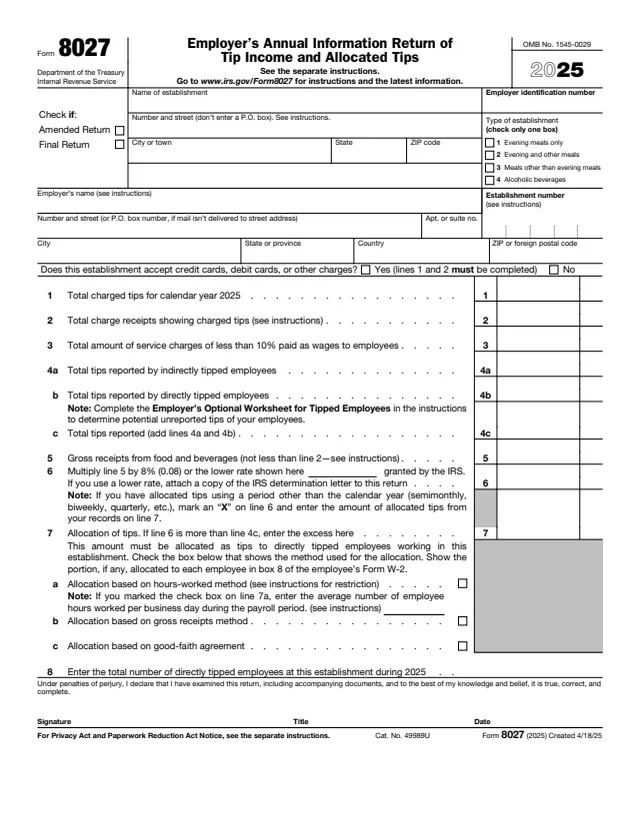
Form 8027 is the Employer's Annual Information Return of Tip Income and Allocated Tips. The IRS says employers use it to annually report receipts and tips from their large food or beverage establishments, and to determine allocated tips for tipped employees.
The form is filed by the employer, not by the tipped employees. It covers one establishment per form: charged tips, charge receipts, service charges paid as wages, tips reported by directly and indirectly tipped employees, gross receipts from food and beverages, and any tip allocation. Any allocated tips then go in box 8 of each affected employee's Form W-2.
This page holds the 2025 form, for calendar year 2025. You can fill out the PDF free in your browser on this page and download the result without an account.
Name, address and employer identification number of the establishment, the amended or final return boxes, the employer's name and address, and a five-digit establishment number.
Four boxes, check only one: evening meals only, evening and other meals, meals other than evening meals, and alcoholic beverages.
A yes or no question on whether the establishment accepts credit cards, debit cards or other charges, then total charged tips and total charge receipts showing charged tips.
Service charges of less than 10% paid as wages, tips reported by indirectly and directly tipped employees with their total on line 4c, and gross receipts from food and beverages.
Line 6 multiplies line 5 by 8% or a lower rate granted by the IRS. Line 7 holds any excess over line 4c, with boxes for the hours-worked, gross receipts or good-faith agreement method.
The total number of directly tipped employees at the establishment during 2025, then the declaration under penalties of perjury with signature, title and date.
Enter the name customers know the establishment by, its address and the EIN. The instructions say the EIN should match the Forms W-2 and Form 941 for the employees there, and not to enter a P.O. box for the establishment address.
Check the one type box that best describes the establishment. Assign a five-digit number, for example 00001, and the instructions say to use the same number for that establishment each year.
Check Yes or No for charges. If Yes, the instructions say to enter an amount on lines 1 and 2, even if zero: tips shown on charge receipts, and food and beverage sales on charge receipts that showed a tip.
Enter service charges of less than 10% distributed to employees, tips reported by indirectly tipped employees such as cooks and bussers, tips reported by directly tipped employees such as waitstaff and bartenders, their total, and gross receipts.
Multiply line 5 by 8% (0.08) or the lower rate, attaching the IRS determination letter for a lower rate. If line 6 is more than line 4c, enter the excess on line 7 and check the allocation method used.
Enter the cumulative number of directly tipped employees who worked there during the year. Sign with your title and date. The instructions list who may sign for a sole proprietor, corporation, partnership, LLC, trust or estate.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
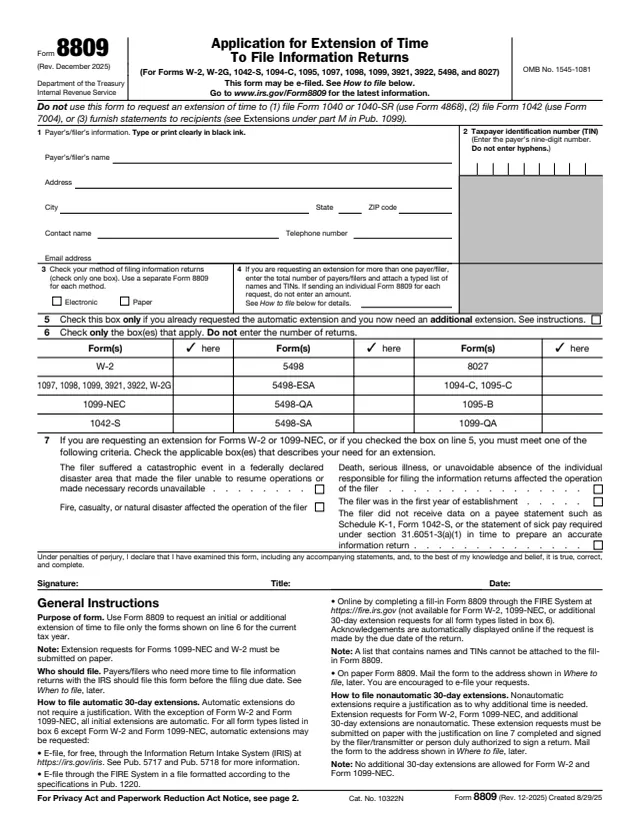
The instructions say to file Form 8027 by March 2, 2026, or by March 31, 2026, if you file electronically. Form 8809 can request an extension of time to file.
Department of the Treasury, Internal Revenue Service, Ogden, UT 84201. The instructions note that the Grand Rapids address for lower rate petitions is not where Form 8027 is mailed.
The instructions say an employer required to file 10 or more information returns during the year files electronically, through the FIRE system. Pub. 1239 has the electronic filing specifications.
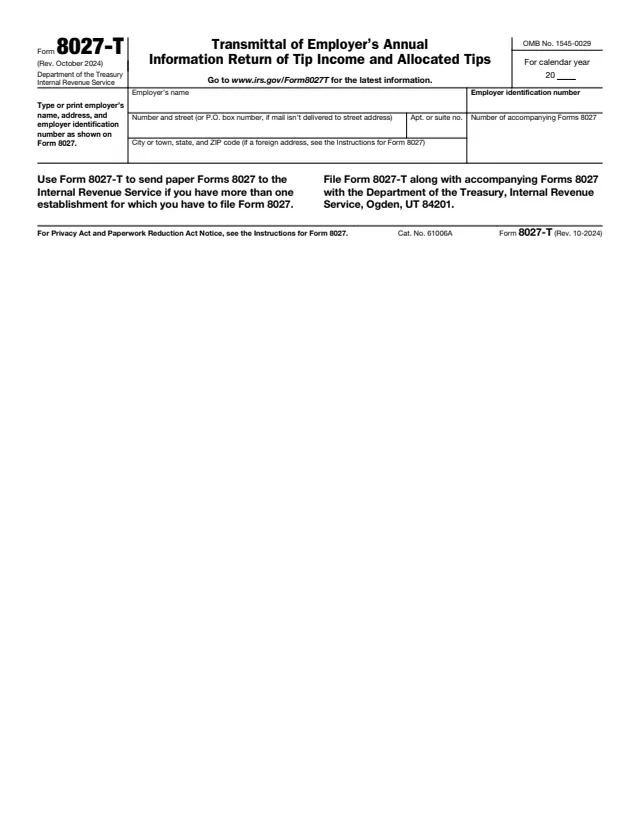
File a separate Form 8027 for each. On paper, Form 8027-T goes with them as a transmittal, with the forms in establishment number order. Form 8027-T is not filed with electronic returns.
If they apply: a copy of a timely filed Form 8809, the lower rate determination letter, and an approved Form 8508 waiver. The instructions say not to attach any other documents.
Allocated tips go in box 8 of each employee's Form W-2. The instructions say they are not subject to withholding and are not included in boxes 1, 3, 5 and 7.
8027-T
7 fields, 1 page
8809
32 fields, 2 pages
W-2
568 fields, 11 pages
W-2c
540 fields, 9 pages
8846
9 fields, 2 pages
8508
165 fields, 2 pages
The instructions say Form 8027 is filed by an employer who operates a large food or beverage establishment. Employees report their tips to the employer; they do not file this form.
No tool matches that search.
No. The instructions say the employer who operates a large food or beverage establishment files it. Employees report their tips to the employer, and any allocated tips appear on their Form W-2.
It asks whether the employer normally employed more than 10 employees on a typical business day in the preceding calendar year. The instructions include an optional worksheet: if its line 7 is more than 80 hours, the test is met.
The instructions say the 8% rate, or a lower rate the IRS granted, is used for tip allocation purposes only. It does not mean employees report only 8%; they report the actual tips they receive.
The instructions say the employer, or a majority of the employees, may petition for a lower rate, but not lower than 2%, by writing to the IRS National Tip Reporting Compliance office in Grand Rapids, MI.
No. The instructions say service charges distributed to employees are wages, not tips, and are not reported as tips on Form 8027. Service charges of less than 10% paid as wages go on line 3.
It is the transmittal filed with paper Forms 8027 when an employer reports for more than one establishment. It is not filed with electronically filed Forms 8027.