7207

Advanced Manufacturing Production Credit

Agency
IRS
Revision
Rev. December 2025
Fillable fields
490
Pages
5
Official source
IRS form page
Checked
October 21, 2026
Fill 7207 online
Page 1 of form 7207

Form 7207: Advanced Manufacturing Production Credit

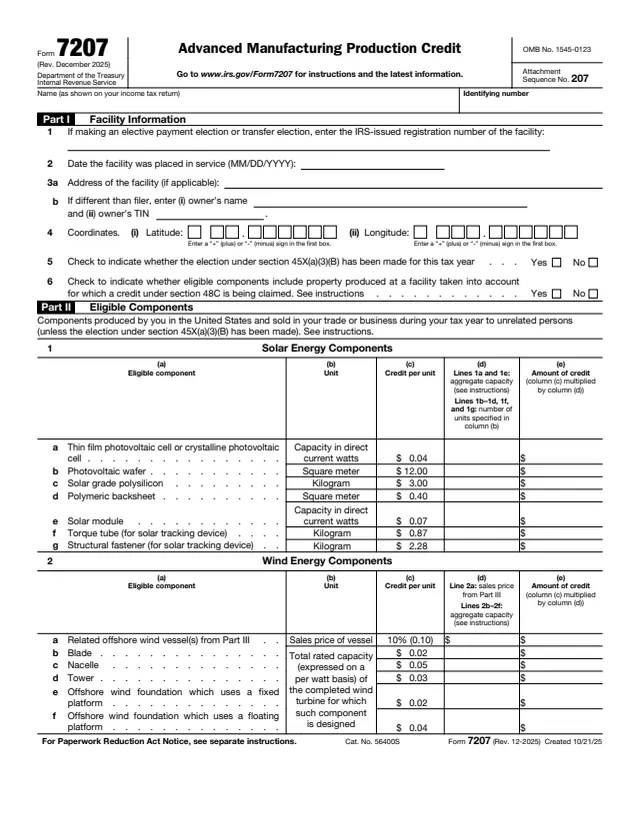
Form 7207, Advanced Manufacturing Production Credit, is used to claim the credit under section 45X. The instructions say it covers eligible components produced by the taxpayer within the United States (including U.S. territories) and sold during the tax year in the taxpayer's trade or business to unrelated persons. The IRS About page says the form figures the credit for applicable components produced and sold during the tax year.

Eligible components are grouped on the form as solar energy components, wind energy components, inverter components, electrode active materials, battery components and critical minerals. Each line prints its unit and its credit per unit. The instructions say a separate Form 7207 is filed for each facility operated to produce and sell eligible components.

This page hosts the December 2025 revision. You can fill out Form 7207 free in your browser on this page and download it without an account.

What's on Form 7207

Part I: Facility Information

Registration number if electing payment or transfer, placed-in-service date, facility address, owner's name and TIN if different, latitude and longitude, and Yes or No questions on the section 45X(a)(3)(B) election and section 48C.


Part II, lines 1 through 3

Solar energy components, wind energy components and inverter components. Each row shows the unit and the credit per unit, for example $0.04 per direct current watt for a photovoltaic cell.

Part II, lines 4 through 6

Electrode active materials and applicable critical minerals at 10% (0.10) of costs incurred, battery components per kilowatt-hour, and metallurgical coal at 2.5% (0.025).

Part II, lines 7 and 8

Credit from partnerships, S corporations, estates and trusts on line 7, then the total on line 8a, with lines 8b and 8c for estates and trusts.

Part III: Related Offshore Wind Vessels

Up to 49 vessels per page, each with name, purpose, official number, new or retrofitted, and sales price. The total goes to Part II, line 2a, column (d).

Part IV: Critical mineral costs

Lines 1 through 73 list each applicable critical mineral with its purity or conversion test. Line 74 totals the costs and goes to Part II, line 6a, column (d).

How to fill out Form 7207

  1. 1

    Part I

    Enter the pre-filing registration number if applicable, the placed-in-service date, the facility address and coordinates, and the owner's name and TIN if different from the filer. Answer the Yes or No questions on lines 5 and 6.

  2. 2

    Solar, wind and inverter lines

    In column (d), enter aggregate capacity or units as the instructions describe. For example, cells sold times the wattage of each. Multiply column (c) by column (d) and enter the result in column (e).

  3. 3

    Electrode, battery and mineral lines

    Enter costs incurred for electrode active materials on line 4a. Enter battery capacity in kilowatt-hours on lines 5a through 5c. Complete Part IV and carry its line 74 total to line 6a.

  4. 4

    Part III for vessels

    List each related offshore wind vessel sold during the tax year, then enter the total of all Parts III on Part II, line 2a, column (d). Attach more Parts III if needed.

  5. 5

    Line 7

    The instructions say credit from Schedules K-1 is reported on a separate Form 7207, with "Credits From Pass-Through Entities" entered on line 2 of Part I, and the amount on line 7.

  6. 6

    Lines 8a through 8c

    Add column (e), lines 1 through 7. The form says partnerships and S corporations report line 8a on Schedule K, estates and trusts go to line 8b, and all others report it on Form 3800, Part III, line 1b.

Why fill Form 7207 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, attachments and limits

Where it goes

The total flows to Form 3800, Part III, line 1b, or to Schedule K for partnerships and S corporations. The form carries Attachment Sequence No. 207.

One form per facility

The instructions say to file a separate Form 7207 for each facility operated to produce and sell eligible components.

Certification statements

The instructions include appendices to submit with Form 7207: a Contract Manufacturing Certification Statement, a related person election certification, and a supplier certification for electrode active materials or applicable critical minerals.

Pre-filing registration

The instructions say a pre-filing registration is completed for each manufacturing facility before an elective payment election or transfer election is made on Form 3800.

Phase-out

The instructions say the credit phases out for eligible components sold after 2029, except applicable critical minerals, at 75% for 2030, 50% for 2031, 25% for 2032 and 0% after December 31, 2032.

Other limits

The instructions say the credit is not available for wind energy components produced and sold after December 31, 2027, and describe restrictions for prohibited foreign entities for tax years beginning after July 4, 2025.

Who files Form 7207?

  • Producers of eligible components

    Taxpayers that produce solar, wind, inverter, battery, electrode active material or critical mineral components in the United States and sell them to unrelated persons.

  • Partnerships, S corporations, estates and trusts

    The instructions say the separate-form-per-facility rule also applies to these entities when they produce eligible components. Partnerships and S corporations report line 8a on Schedule K.

  • Applicable entities

    The instructions say certain tax-exempt and governmental entities can elect to treat the credit as a payment of tax and file Form 7207, Form 3800 and Form 990-T or another applicable return.

  • Electing and transferring taxpayers

    Line 1 asks for the IRS-issued registration number of the facility when an elective payment election or transfer election is made. The instructions describe a pre-filing registration for each facility.

  • Partners and shareholders with only a K-1

    The instructions say that if your only source of the credit is a Schedule K-1, you don't need to file Form 7207 and report the credit on Form 3800, Part III, line 1b.

The form is filed by the business that produces and sells eligible components, attached to its income tax return. The instructions say partners, shareholders and beneficiaries whose only source of the credit is a Schedule K-1 generally report it on Form 3800 instead.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 7207

What does Form 7207 claim?

The instructions say it claims the advanced manufacturing production credit under section 45X for eligible components produced within the United States and sold to unrelated persons in the taxpayer's trade or business.

Is one Form 7207 enough for several facilities?

No. The instructions say a separate Form 7207 is filed for each facility operated to produce and sell eligible components.

Do partners or S corporation shareholders file Form 7207?

The instructions say they generally don't if their only source of the credit is the pass-through entity. They report it on Form 3800, Part III, line 1b.

How is aggregate capacity figured for solar cells?

The instructions multiply the number of components sold by the wattage of each. Their example: 500 100-watt cells and 1,500 200-watt cells give 350,000.

What are Parts III and IV for?

Part III lists each related offshore wind vessel sold with its sales price. Part IV lists the costs of producing each applicable critical mineral, totaled on line 74.

Can the credit be paid out or transferred?

The instructions describe an elective payment election under section 6417 and a transfer election under section 6418, both after a pre-filing registration, and point to the Instructions for Form 3800.