What you need to know
Pages 1 to 3: what an offer is, the conditions before an offer is considered, bankruptcy and open audits, tax refunds, doubt as to liability, tax liens, trust fund taxes and other facts.
656-B
Form 656 Booklet Offer in Compromise
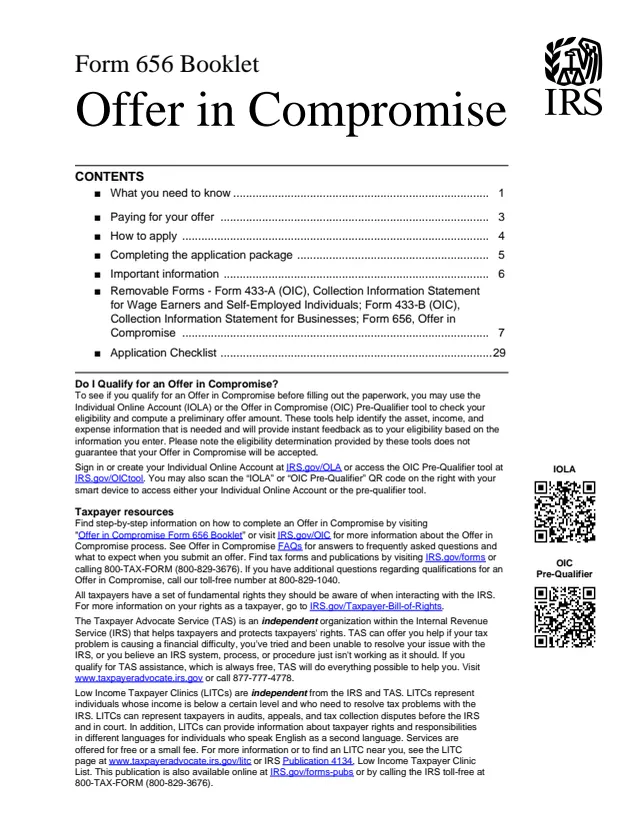
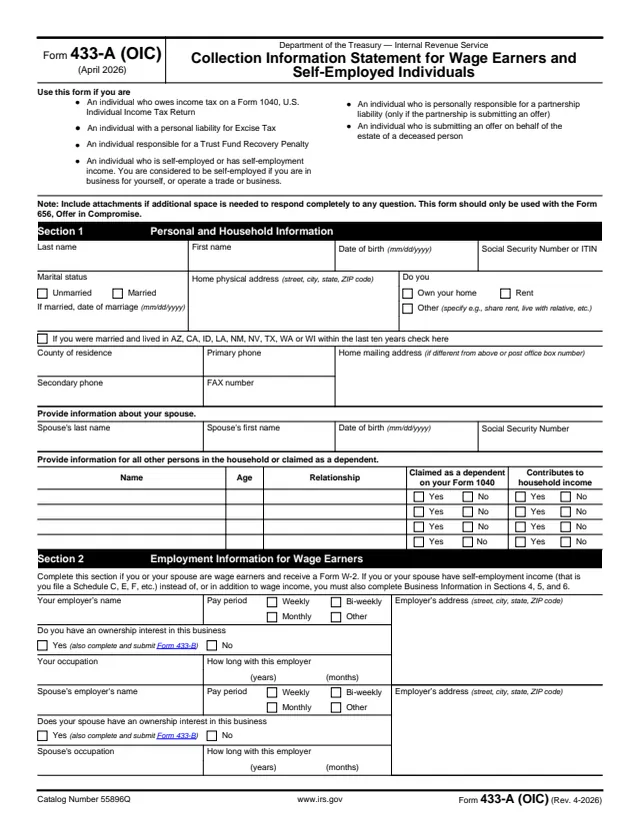
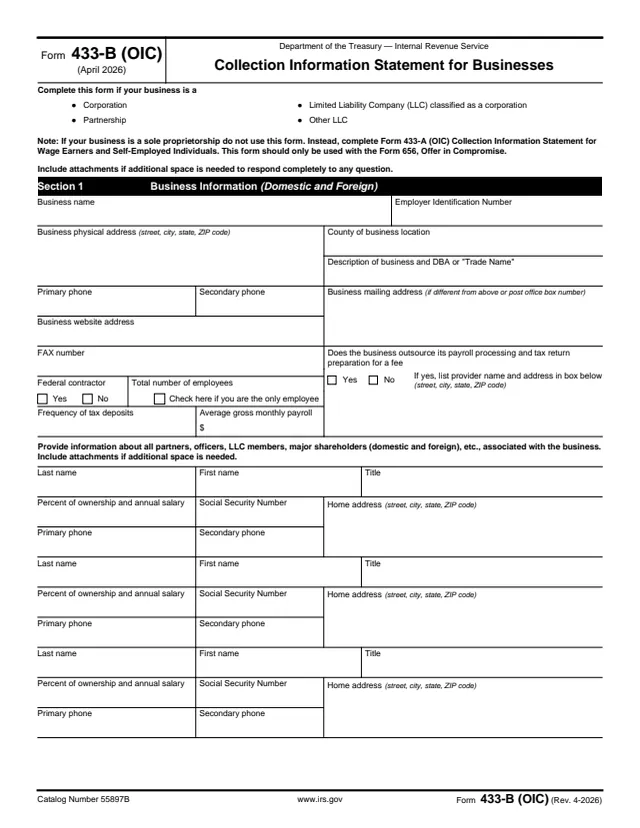
Form 656-B is the Form 656 Booklet for an offer in compromise. The booklet describes an offer as an agreement between the taxpayer and the IRS that settles a tax debt for less than the full amount owed. It holds the instructions plus three removable forms: Form 433-A (OIC) for wage earners and self-employed individuals, Form 433-B (OIC) for businesses, and Form 656, and it ends with an application checklist.
The booklet suggests checking eligibility first with the Individual Online Account (IOLA) at IRS.gov/OLA or the OIC Pre-Qualifier tool at IRS.gov/OICtool, and says that submitting an application does not ensure the IRS will accept the offer. An offer based on a legitimate doubt that the tax is owed uses Form 656-L instead.
You can fill out the PDF free in your browser on this page and download the result without an account.
Pages 1 to 3: what an offer is, the conditions before an offer is considered, bankruptcy and open audits, tax refunds, doubt as to liability, tax liens, trust fund taxes and other facts.
The $205 application fee, the Lump Sum and Periodic Payment options, what the application includes, and applying online through the Individual Online Account.
Ten sections on household, employment, personal and business assets, self-employment, monthly income and expenses, the minimum offer calculation, other information and signatures.
Seven sections on business information, business assets, income, expenses, the minimum offer calculation, other information and signatures.
Nine sections: individual or business information, reason for offer, payment terms, designation of payment, source of funds and compliance, offer terms, signatures and paid preparer.
Page 29: a checklist to include with the application, and the mailing addresses by state.
Tax returns, bank statements, income statements such as Form W-2 and Form 1099, mortgage, credit and retirement account statements, and the household's monthly gross income and expenses.
Individuals and sole proprietors use Form 433-A (OIC); corporations, partnerships and LLCs use Form 433-B (OIC). Each has a section that calculates the minimum offer amount.
Attach copies of the documents listed at the end of each form. The booklet says not to send original documents.
It names the tax years and types of tax, the offer amount and the payment terms. The booklet says the offer amount is to be equal to or greater than the amount calculated on Form 433-A (OIC) or 433-B (OIC).
Pay through EFTPS or the Individual Online Account, or by a separate check, cashier's check or money order for each fee and payment, payable to the "United States Treasury". Low-Income Certification applicants send no money.
Apply online through the Individual Online Account, or mail the package to the Centralized Offer in Compromise Unit in Memphis or Brookhaven based on your state, and keep a copy.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
AL, AZ, CA, CO, GA, HI, ID, KY, LA, MD, MS, ND, NM, NV, OK, OR, SD, TN, TX, UT, VA, WA: Memphis IRS Center COIC Unit, P.O. Box 30803, AMC, Memphis, TN 38130-0803, 844-398-5025.
AK, AR, CT, DC, DE, FL, IA, IL, IN, KS, MA, ME, MI, MN, MO, MT, NC, NE, NH, NJ, NY, OH, PA, PR, RI, SC, VT, WI, WV, WY, or a foreign address: Brookhaven IRS Center COIC Unit, P.O. Box 9007, Holtsville, NY 11742-9007, 844-805-4980.
Individuals may apply through their Individual Online Account. The booklet says not to mail a duplicate application if it was already submitted online.
Each Form 656 carries the $205 application fee and initial payment, unless an individual meets the Low-Income Certification guidelines.
The booklet says to reply promptly to IRS requests for more information, since a late reply leads to the offer being returned without appeal rights. Penalties and interest keep accruing while the offer is considered.
The booklet says an accepted offer may be defaulted if required returns are not filed and taxes not paid on time within the five years after acceptance.
656
115 fields, 8 pages
433-A
425 fields, 8 pages
433-B
267 fields, 6 pages
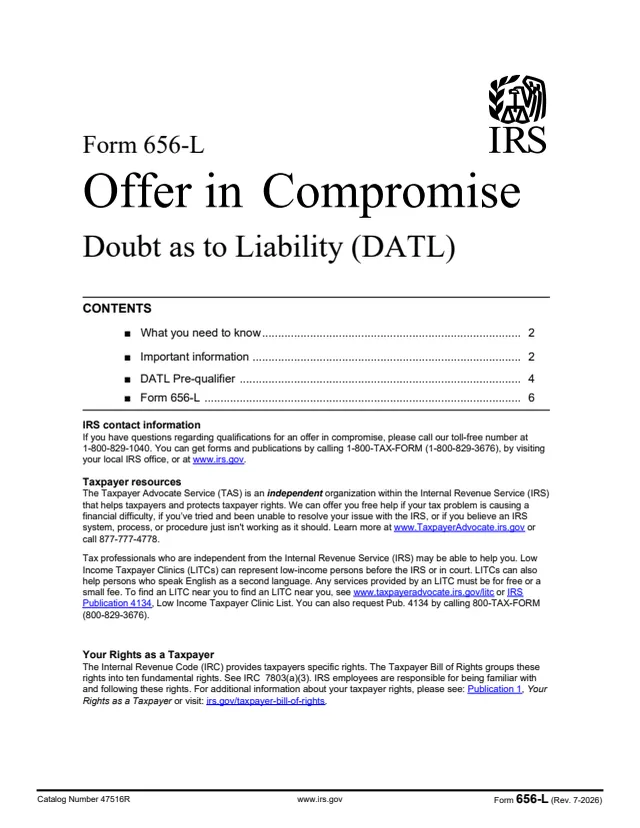
656-L
117 fields, 10 pages

2848
92 fields, 2 pages
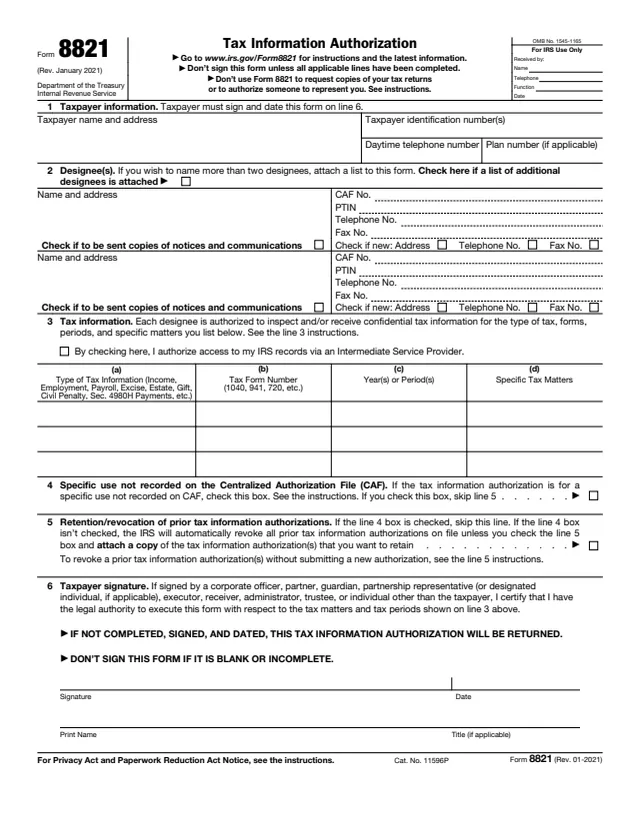
8821
45 fields, 1 page
The taxpayer asking the IRS to settle a tax debt completes the forms in the booklet and sends them to the IRS.
No tool matches that search.
The instructions for an offer in compromise, removable copies of Form 433-A (OIC), Form 433-B (OIC) and Form 656, and an application checklist with the mailing addresses.
All required tax returns filed, a bill received for at least one tax debt in the offer, the current year's required estimated tax payments made, and, for business owners with employees, required federal tax deposits for the current quarter and the two preceding quarters.
The booklet lists a $205 application fee plus an initial payment based on the payment option chosen. Both are waived for individuals who meet the Low-Income Certification guidelines.
The booklet says the IRS may keep any tax refund, including interest, for a tax return assessed before the date it accepts the offer, by offsetting it against the tax debt. The refund does not count as a payment toward the offer.
The booklet points to Form 656-L, Offer in Compromise (Doubt as to Liability), and says not to submit both types of offer at the same time.
To the Centralized Offer in Compromise Unit in Memphis or Brookhaven, depending on your state, as listed on page 29, unless it was submitted online through the Individual Online Account.