Name and identifying number
The name or names shown on the return and the identifying number.
5884
Work Opportunity Credit
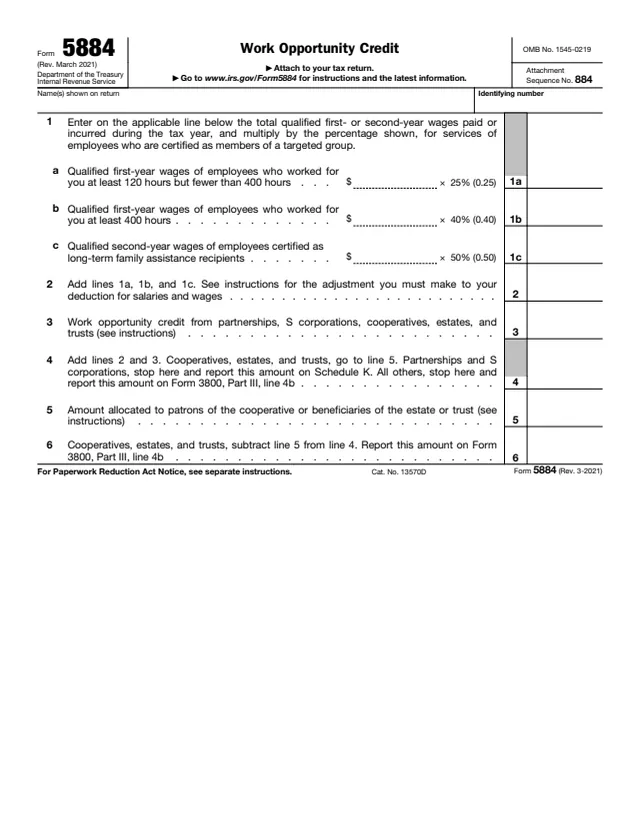
Form 5884 is the form employers use to figure the work opportunity credit. The IRS About page says employers file it to claim the credit for qualified first- and/or second-year wages they paid to or incurred for targeted group employees during the tax year.
The form is attached to the employer's tax return. The credit on line 4 or line 6 then goes to Schedule K for partnerships and S corporations, or to Form 3800, General Business Credit, Part III, line 4b for other filers. The instructions say each employee is certified by the state workforce agency (SWA) as a member of a targeted group, either by the day the individual begins work or through Form 8850.
This page hosts the March 2021 revision, whose instructions describe the credit for employees who began work before 2026. Certain tax-exempt organizations use Form 5884-C instead. You can fill out the PDF free in your browser on this page and download it without an account.
The name or names shown on the return and the identifying number.
Qualified first-year wages for employees who worked at least 120 hours but fewer than 400 hours, times 25% (0.25), and for employees who worked at least 400 hours, times 40% (0.40).
Qualified second-year wages of employees certified as long-term family assistance recipients, times 50% (0.50).
The current year credit, credit passed through from partnerships, S corporations, cooperatives, estates and trusts, and the total.
For cooperatives, estates and trusts: the amount allocated to patrons or beneficiaries and the amount left for Form 3800.
The instructions say a certification is requested from and issued by the SWA for each employee, proving the employee is a member of a targeted group.
Enter qualified wages on the matching line and multiply by the percentage shown. The instructions cap first-year wages at $6,000 for most targeted groups, $3,000 for a summer youth employee and $10,000 per year for a long-term family assistance recipient, with separate limits for qualified veterans.
Add lines 1a, 1b and 1c. The instructions say the deduction for salaries and wages is generally reduced by the line 2 amount.
Enter credits from Schedule K-1 (Form 1065) box 15 code J, Schedule K-1 (Form 1120-S) box 13 code J, Schedule K-1 (Form 1041) box 13 code F, or Form 1099-PATR box 11.
Add lines 2 and 3. Partnerships and S corporations stop and report on Schedule K. Cooperatives, estates and trusts complete lines 5 and 6. All others report line 4 on Form 3800, Part III, line 4b.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return.
The instructions say the credit can be claimed, or the employer can elect not to claim it, any time within 3 years from the due date of the return, on either the original return or an amended return.
If Form 8850 is used, the instructions say it is signed by the employer and the individual and submitted to the SWA of the state where the business is located by the 28th calendar day after the date the individual begins work.
The instructions say wages used for the coronavirus-related employee retention credit, the credit for qualified sick and family leave wages, or the 2020 qualified disaster employee retention credit on Form 5884-A cannot also be used on Form 5884 for the periods they list.
Members of a controlled group or businesses under common control are treated as a single employer. A member enters its share on line 2 and attaches a statement showing how it was figured.

3800
1,921 fields, 9 pages
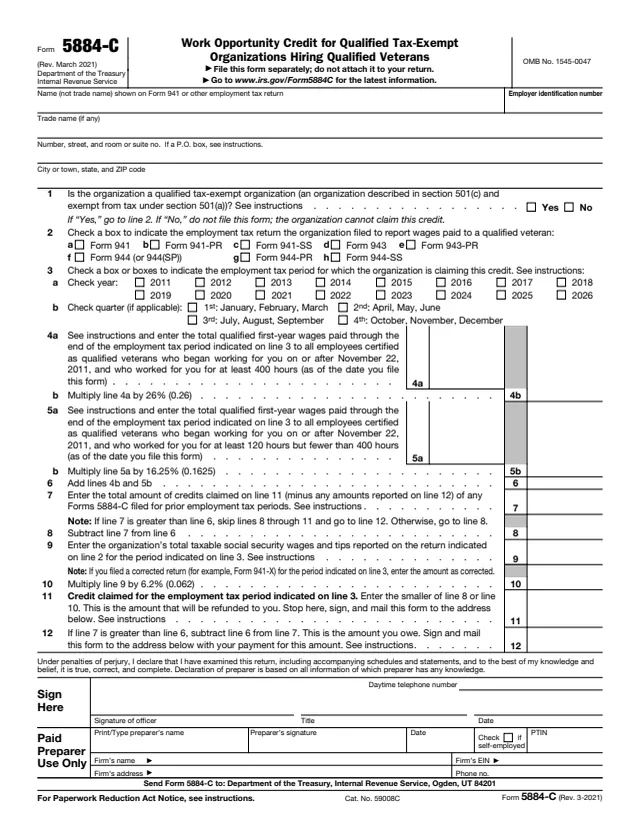
5884-C
55 fields, 4 pages
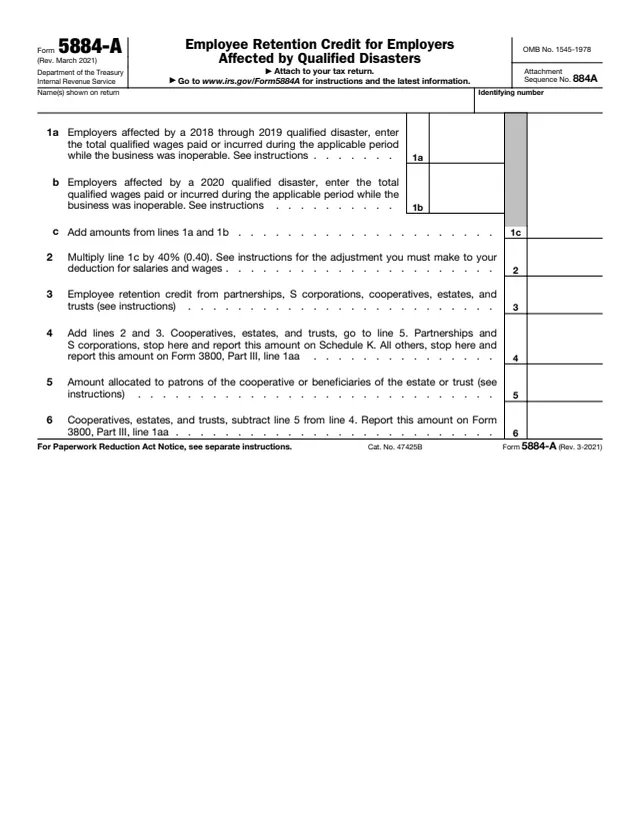
5884-A
10 fields, 1 page

1065
111 fields, 1 page
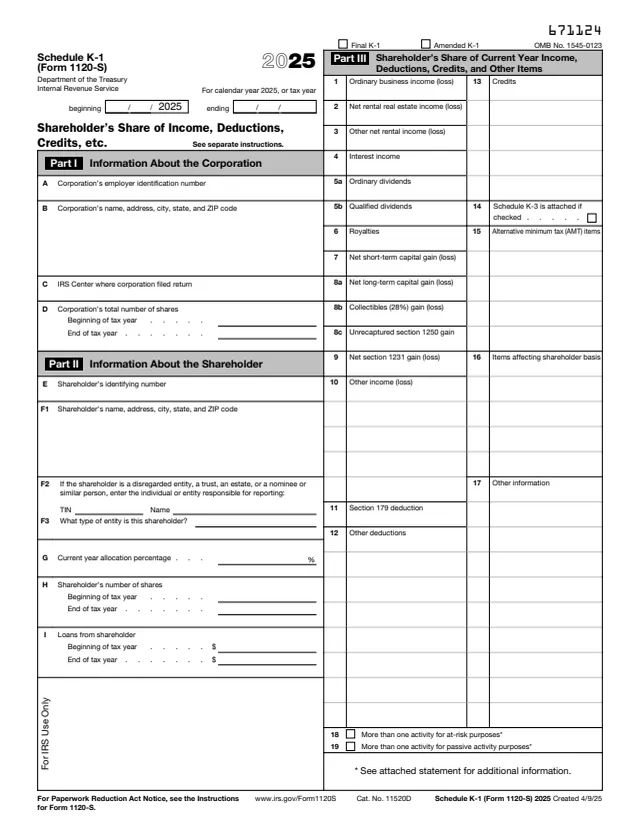
1120-S
114 fields, 1 page
8582-CR
52 fields, 2 pages
Form 5884 is completed by an employer and attached to its tax return. The instructions say partnerships, S corporations, cooperatives, estates and trusts file it to claim the credit.
No tool matches that search.
Employers claiming the work opportunity credit. The instructions say partnerships, S corporations, cooperatives, estates and trusts file it to claim the credit.
No. The form says to attach it to the tax return.
Line 1a uses 25% (0.25), line 1b uses 40% (0.40) and line 1c uses 50% (0.50), as printed on the form.
The instructions list groups such as long-term family assistance recipients, TANF recipients, qualified veterans, qualified ex-felons, designated community residents, vocational rehabilitation referrals, summer youth employees, SNAP recipients, SSI recipients and qualified long-term unemployment recipients.
The instructions say qualified wages are zero if the employee did not work at least 120 hours, worked for the employer before, is a dependent or relative, or if 50% or less of the wages were for work in the trade or business.
The instructions point certain tax-exempt organizations to Form 5884-C for wages paid to qualified veterans.