Header and line A
Names shown on the tax return, Social Security number, an EIN if any, and a yes or no question: did you actively participate in the operation of this farm during 2025?
4835
Farm Rental Income and Expenses
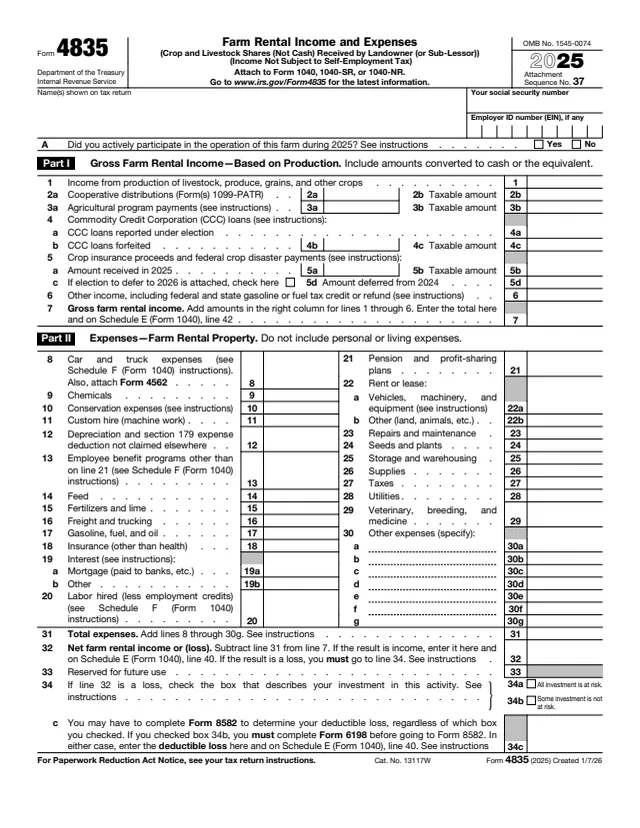
Form 4835, Farm Rental Income and Expenses, covers crop and livestock shares (not cash) received by a landowner or sub-lessor. The IRS says landowners and sub-lessors that do not materially participate in the operation or management of the farm (for self-employment tax purposes) file it to report farm rental income based on crops or livestock produced by the tenant. The form's heading reads "Income Not Subject to Self-Employment Tax."
The instructions add that the form is used only if the activity was a rental activity for purposes of the passive activity loss limitations. It is attached to Form 1040, 1040-SR or 1040-NR, and its totals carry to Schedule E (Form 1040). This page has the 2025 form, with its instructions printed on pages 2 and 3.
You can fill out the PDF free in your browser on this page and download it without an account.
Names shown on the tax return, Social Security number, an EIN if any, and a yes or no question: did you actively participate in the operation of this farm during 2025?
Income from production, cooperative distributions from Forms 1099-PATR, agricultural program payments, Commodity Credit Corporation loans, crop insurance and federal crop disaster payments, and other income.
The total of the right column of lines 1 through 6, also entered on Schedule E (Form 1040), line 42.
Expense lines from car and truck costs, chemicals and depreciation through rent, repairs, taxes, utilities and veterinary costs, plus seven lines for other expenses. Personal or living expenses are excluded.
Total expenses, then net farm rental income or loss. Income on line 32 also goes on Schedule E (Form 1040), line 40. Line 33 is reserved for future use.
Two boxes, all investment at risk or some investment not at risk, and line 34c for the deductible loss.
The instructions say active participation generally means taking part in management decisions, such as approving new tenants, deciding on rental terms and approving capital or repair spending, in a significant and bona fide sense. They also say there is no active participation if your interest, including your spouse's, was less than 10% by value at any time during the year.
Report income from livestock, produce, grains and other crops based on production. The instructions say that under both the cash and accrual methods, livestock or crop share rentals are reported in the year they are converted into money or its equivalent.
Enter total cooperative distributions from Form 1099-PATR on 2a and the taxable amount on 2b, then agricultural program payments, the full amount of any CCC loans forfeited, and crop insurance proceeds. The instructions say a cash method filer may be able to postpone eligible crop insurance proceeds by checking line 5c and attaching a statement.
Enter each expense on its line. The instructions say conservation expenses on line 10 are deductible only if consistent with an approved conservation or recovery plan, and cannot exceed 25% of gross income from farming. Capitalized costs go in parentheses on line 30g, with "263A" written to the left.
Subtract line 31 from line 7. Income goes here and on Schedule E (Form 1040), line 40. If line 31 is more than line 7, the instructions say not to enter the loss on line 32 and to go to line 34. Prior year unallowed passive losses are marked "PAL" beside line 32.
For a loss, check box 34a or 34b. The form says Form 8582 may be needed either way, and that a filer who checks 34b completes Form 6198 before Form 8582. The deductible loss goes on line 34c and on Schedule E (Form 1040), line 40.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR or 1040-NR.
Line 7 goes on Schedule E (Form 1040), line 42. Net income on line 32, or the deductible loss on line 34c, goes on Schedule E, line 40.
This is the 2025 form. Line A asks about participation during 2025, and line 5c is for an election to defer crop insurance proceeds to 2026.
The instructions say that with net income on line 32, the tax may be less if figured using Schedule J (Form 1040).
The instructions say an EIN is needed only with a qualified retirement plan or a requirement to file an employment, excise, estate, trust, partnership, or alcohol, tobacco and firearms tax return.
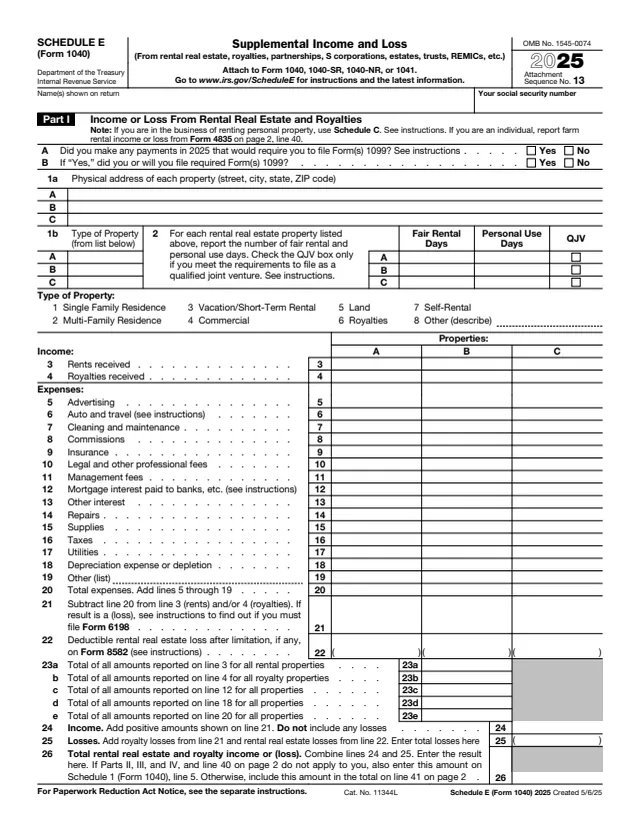
1040
185 fields, 2 pages
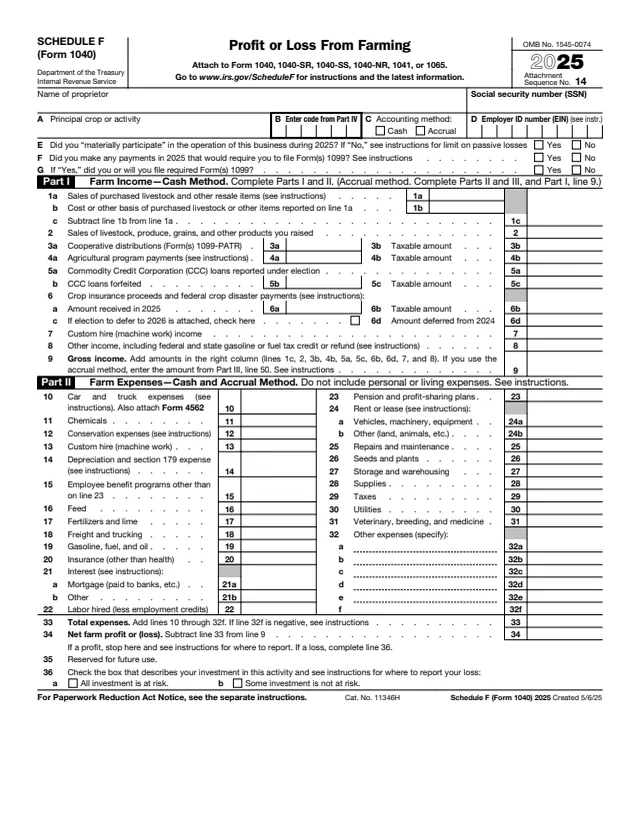
1040
89 fields, 2 pages
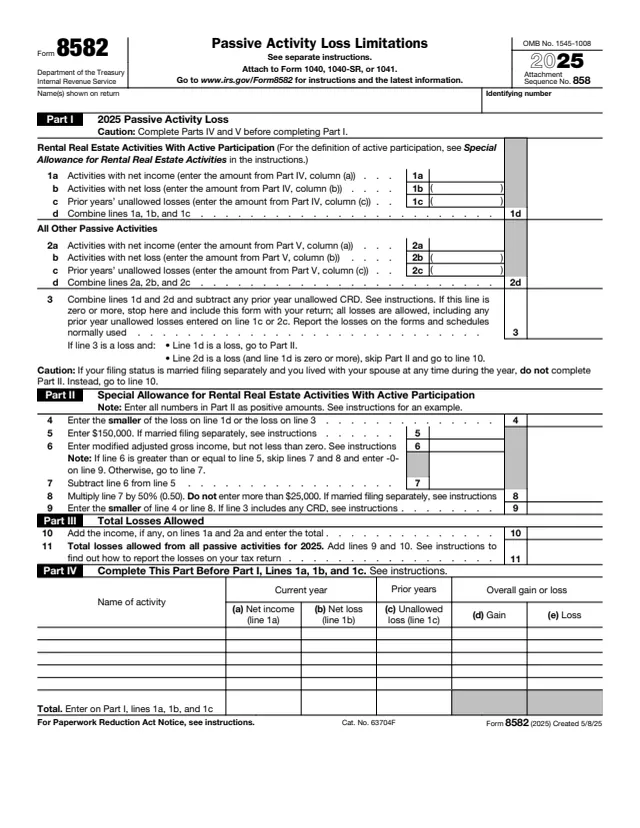
8582
205 fields, 3 pages
6198
34 fields, 1 page
4562
277 fields, 3 pages
8825
221 fields, 2 pages
The form is filed by an individual landowner or sub-lessor with their own income tax return.
No tool matches that search.
A landowner or sub-lessor who did not materially participate (for self-employment tax purposes) in the operation or management of the farm and received rent based on crops or livestock produced by the tenant.
The form's heading reads "Income Not Subject to Self-Employment Tax."
The instructions say to use Schedule F (Form 1040) instead. Tenants also use Schedule F.
The instructions say cash rent for pasture or farmland based on a flat charge is reported on Schedule E (Form 1040), Part I.
No. The instructions say partnerships and S corporations report crop and livestock share rent on Form 8825.
Gross farm rental income on line 7 goes on Schedule E (Form 1040), line 42. Net income on line 32, or the deductible loss on line 34c, goes on Schedule E, line 40.