Header and opening lines
Taxpayer name, taxpayer identification number and tax year, the main rule in English and Spanish, and pointers to IRS.gov/espanol and IRS.gov/eitc.
14820
Documents You Need to Send to Claim the Earned Income Credit on the Basis of a Qualifying Child or Children for Tax Year 2026
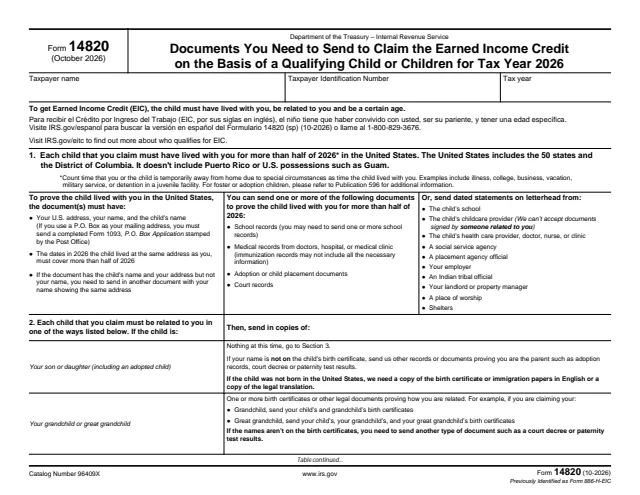
Form 14820, Documents You Need to Send to Claim the Earned Income Credit on the Basis of a Qualifying Child or Children for Tax Year 2026, is a two-page IRS list of the documents that support a claim for the Earned Income Credit (EIC) with a qualifying child. Its footer says it was previously identified as Form 886-H-EIC.
The form opens with its main rule: "To get Earned Income Credit (EIC), the child must have lived with you, be related to you and be a certain age." It then has three numbered sections, one for each of those tests, with the documents to send for each, and ends with a checklist of things to review before sending copies.
The top of page 1 has spaces for the taxpayer name, taxpayer identification number and tax year. The form points to IRS.gov/eitc for more on who qualifies. You can fill in the header free in your browser on this page and download the form without an account.
Taxpayer name, taxpayer identification number and tax year, the main rule in English and Spanish, and pointers to IRS.gov/espanol and IRS.gov/eitc.
The form says each child claimed must have lived with the taxpayer for more than half of 2026 in the United States, which includes the 50 states and the District of Columbia, not Puerto Rico or possessions such as Guam.
What a document has to show, such as the U.S. address, both names and dates covering more than half of 2026, then school, medical, adoption, placement or court records, or dated statements on letterhead.
A table of relationships, from son or daughter to foster child, with the birth certificates, court papers or agency statements to send for each.
Three age rows: under age 19, age 19 but under 24 and a full-time student, and any age and permanently and totally disabled, with the documents for each.
The closing list of things to check, including that the documents prove all three tests, are for 2026, are translated if not in English, and are not signed by a relative.
Enter the taxpayer name, taxpayer identification number and tax year at the top of page 1.
Pick records or dated letterhead statements that show the taxpayer's U.S. address, both names and dates in 2026. If a P.O. Box is the mailing address, the form asks for a completed Form 1093, P.O. Box Application, stamped by the Post Office.
Find the child's relationship in section 2. For a son or daughter the form says "Nothing at this time" unless the taxpayer's name is not on the birth certificate or the child was not born in the United States.
For a child under age 19 at the end of 2026 and younger than the taxpayer, the form says "Nothing at this time." For a student age 19 but under 24, it asks for school records for any part of five months. For a disabled child, it asks for a letter from a doctor, other health care provider, social service program or government agency.
Before sending, check the items at the end of page 2. The form notes one record can prove more than one test, for example a school record that shows the address and lists the taxpayer as the parent.
Send copies of the documents. A document not in English is sent as a legally translated document.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form speaks of "sending copies of your documents to us," meaning the IRS. It prints no mailing address.
The form says: "We must have proof for all three: you are related to the child, the child lived with you and the child's age." It adds that without them the EIC can't be claimed with that child, though the taxpayer may still be eligible for the EIC without a qualifying child.
The form says the IRS can't accept documents signed by someone related to the taxpayer, for example a sister who provides childcare.
The checklist says the documents are for 2026 and not the current year.
The form says to visit IRS.gov/espanol for Form 14820 (sp) (10-2026) or call 1-800-829-3676.
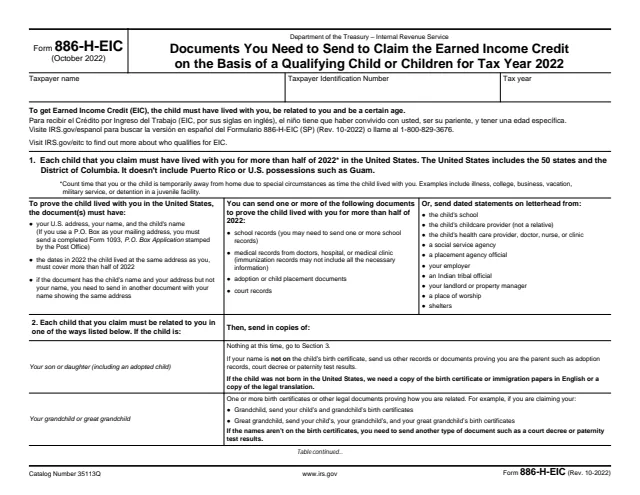
886-H-EIC
8 fields, 2 pages
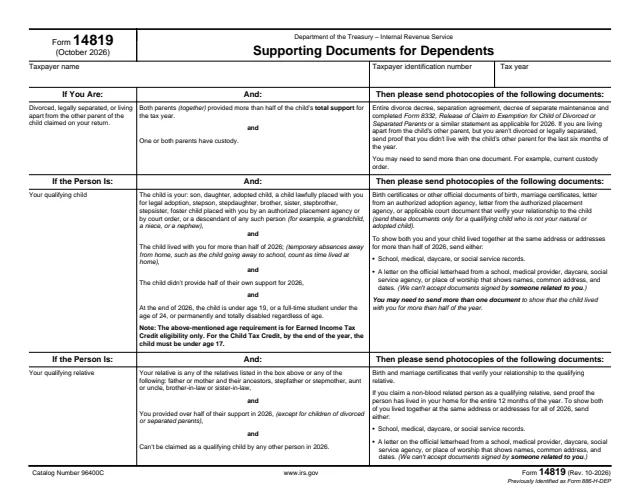
14819
3 fields, 2 pages
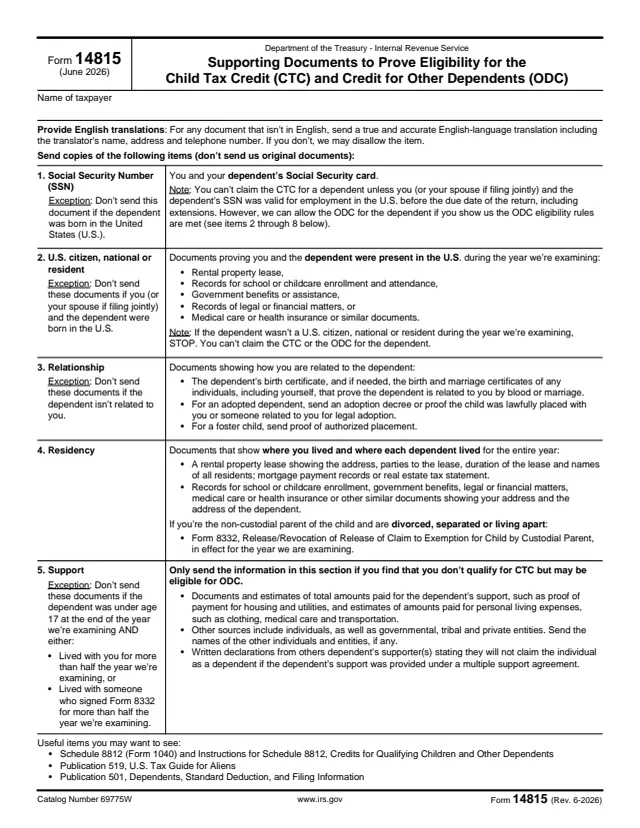
14815
1 field, 1 page
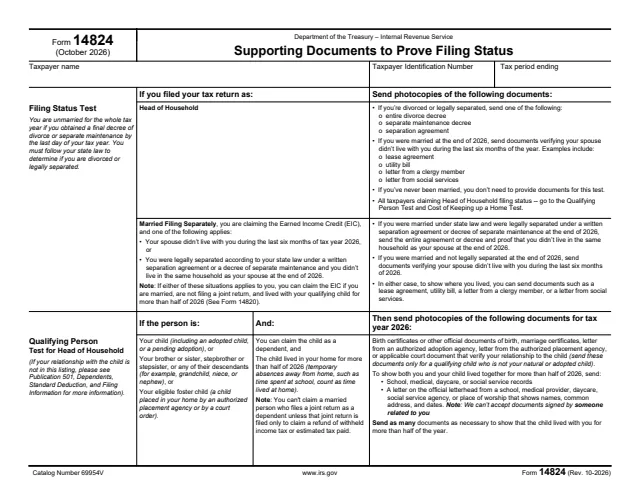
14824
3 fields, 2 pages
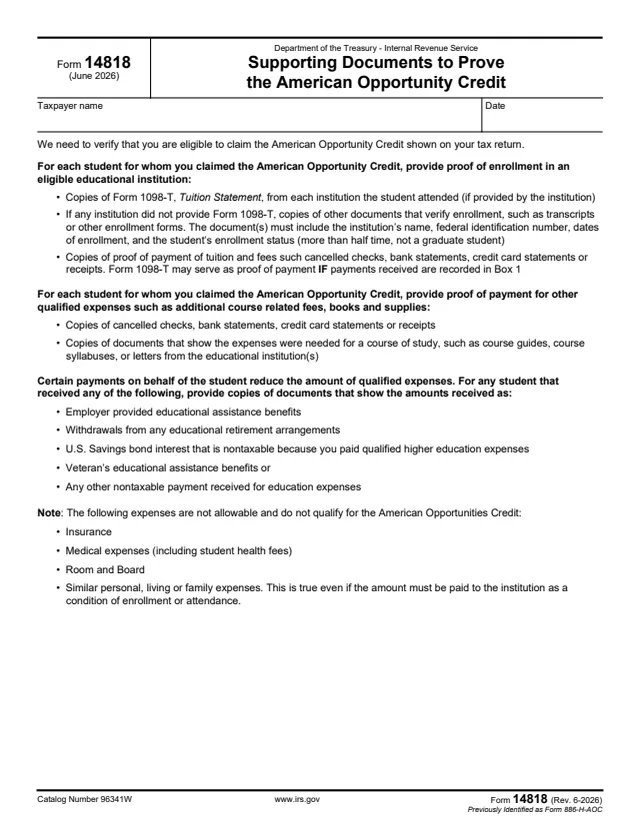
14818
2 fields, 1 page
The form is addressed to a taxpayer who claims the EIC with a qualifying child. The taxpayer sends copies of the listed documents to the IRS.
No tool matches that search.
The IRS. The form refers to sending copies of the documents "to us" and prints no mailing address.
That the child lived with the taxpayer for more than half of 2026 in the United States, is related to the taxpayer, and meets the age rule.
For relationship, the form says "Nothing at this time" for a son or daughter, unless the taxpayer's name is not on the birth certificate or the child was not born in the U.S. For age, a child under 19 at the end of 2026 and younger than the taxpayer needs nothing at this time.
The form says to count time away due to special circumstances, such as illness, college, business, vacation, military service or detention in a juvenile facility, as time the child lived with the taxpayer.
No. The form says the IRS can't accept documents signed by someone related to the taxpayer, and gives a sister who provides childcare as an example.
The footer says Form 14820 was previously identified as Form 886-H-EIC.